

Company Coverage
Trip.com (9961 HK): Antitrust Penalty Finalised; Regulatory Overhang Clears Despite Near-Term Domestic Pressure
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$357.00
HK$508.00
+42.3%
HK$475.00
Analyst
Highlights
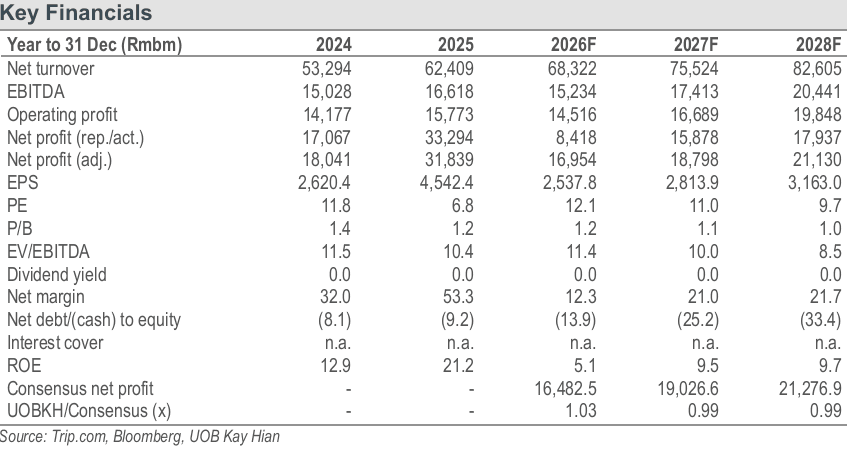
- Trip.com’s Rmb5.18b penalty formally concludes the antitrust investigation and removes a key regulatory overhang. Compliance-related adjustments may create near-term pressure on domestic operations and contribute to a softer 2Q26 revenue growth of 3-8% yoy. However, the impact on core earnings should remain limited, supported by over 30% growth in the international business and the company’s strong brand, integrated platform and customer stickiness.
- Maintain BUY with a higher target price of HK$508.00 (US$65.00).
Analysis
- Trip.com antitrust penalty finalised; key regulatory overhang removed. China’s State Administration for Market Regulation imposed total penalties of Rmb5.18b on Trip.com for abusing its dominant market position through mandatory hotel exclusivity arrangements and enforcing lowest-price requirements. The total comprises Rmb1.66b in confiscated illegal gains and a Rmb3.52b fine, equivalent to 7.5% of the company’s 2025 domestic sales of Rmb46.96b. Trip.com was also ordered to cease the relevant practices and refund Rmb122m of order reserve funds deducted from hotel operators. We expect the penalty to result in a material one-off impact on reported earnings, while the formal conclusion of the investigation should remove a key regulatory uncertainty surrounding the company.
Limited impact on core earnings outlook. We expect the penalty and related business adjustments to create some near-term disruption to Trip.com’s domestic operations. However, given the relatively weak performance of the domestic business and the company’s increasing focus on international expansion, we believe the impact on core earnings should be limited. The pure international business remains the key growth driver, with revenue expected to grow over 30% yoy, including around 45% growth from Trip.com’s own international business. International hotel revenue is expected to rise by around 50% yoy, transportation revenue and volume by around 40% yoy, while packaged-tour revenue is expected to more than double and contribute over 10% of Trip.com’s revenue.
Highlights
- Trip.com’s Rmb5.18b penalty formally concludes the antitrust investigation and removes a key regulatory overhang. Compliance-related adjustments may create near-term pressure on domestic operations and contribute to a softer 2Q26 revenue growth of 3-8% yoy. However, the impact on core earnings should remain limited, supported by over 30% growth in the international business and the company’s strong brand, integrated platform and customer stickiness.
- Maintain BUY with a higher target price of HK$508.00 (US$65.00).
Analysis
- Trip.com antitrust penalty finalised; key regulatory overhang removed. China’s State Administration for Market Regulation imposed total penalties of Rmb5.18b on Trip.com for abusing its dominant market position through mandatory hotel exclusivity arrangements and enforcing lowest-price requirements. The total comprises Rmb1.66b in confiscated illegal gains and a Rmb3.52b fine, equivalent to 7.5% of the company’s 2025 domestic sales of Rmb46.96b. Trip.com was also ordered to cease the relevant practices and refund Rmb122m of order reserve funds deducted from hotel operators. We expect the penalty to result in a material one-off impact on reported earnings, while the formal conclusion of the investigation should remove a key regulatory uncertainty surrounding the company.
Limited impact on core earnings outlook. We expect the penalty and related business adjustments to create some near-term disruption to Trip.com’s domestic operations. However, given the relatively weak performance of the domestic business and the company’s increasing focus on international expansion, we believe the impact on core earnings should be limited. The pure international business remains the key growth driver, with revenue expected to grow over 30% yoy, including around 45% growth from Trip.com’s own international business. International hotel revenue is expected to rise by around 50% yoy, transportation revenue and volume by around 40% yoy, while packaged-tour revenue is expected to more than double and contribute over 10% of Trip.com’s revenue.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$357.00
HK$508.00
+42.3%
HK$475.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link: https://research-api.uobkayhian.com/assets/disclaimer/df64a6ea-7980-447c-ae9e-fd19b93257dc, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


