
Company Coverage
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales
BUY (Maintained)
Current price:
Target price:
Upside:
HK$14.97
HK$29.00
+93.7%
Analyst
Highlights
- 2026 sales will probably miss the 3.45m target on the ongoing run rate.
- Geely targets doubling exports from about 1m to 2m within 1-2 years on model launches, eg iHEV, Zeekr, and overseas capacity.
- Fast-charging, L3 ADAS, and iHEV technologies will drive growth.
- Exports and premium models underpin net profit per vehicle.
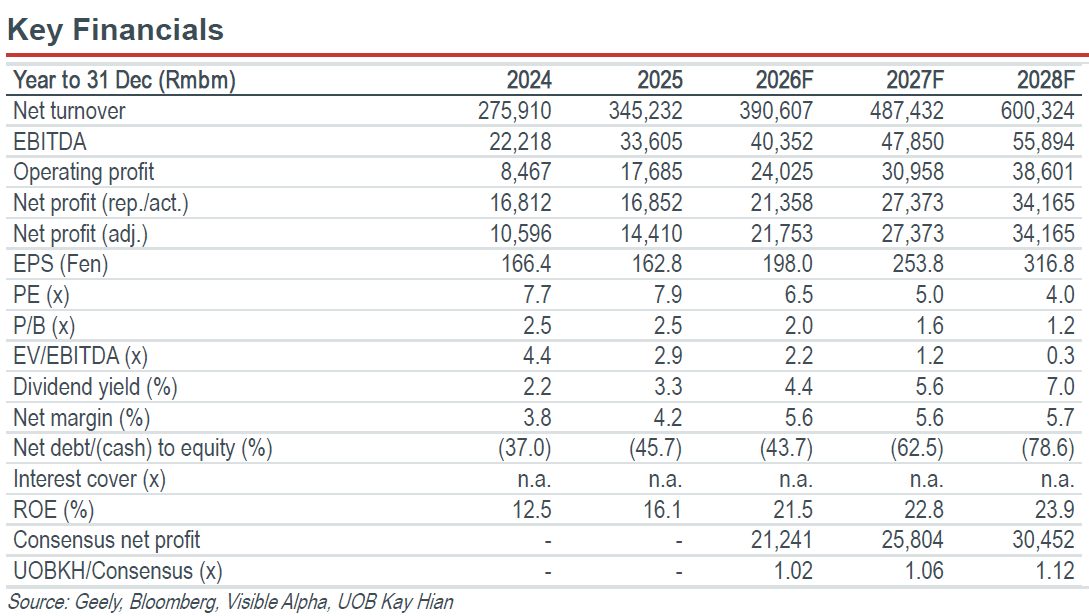
- We raise 2026 EPS by 7%, keep 2027 EPS unchanged, and trim 2028 EPS by 3%, based on lower sales estimates of higher profit per vehicle.
- We estimate 3Q26 net profit at Rmb5,525m (+39.5% yoy/+7.9% qoq).
- Maintain BUY and target price of HK$29.00 (10x 2027F PE).
Analysis
- 2026 sales will probably miss the 3.45m-unit target, based on ongoing run rate. 9M26 sales of 2.235m units (+3.0% yoy) make up 64.8% of the full-year target. It requires average sales of 404,840 units/month (+42.2% yoy) in 4Q26 to reach the company’s full-year target of 3.45m units, which seems unlikely. We now expect Geely’s 2026 sales at 3.00m-3.45m units on the ongoing run rate, vs its target of 3.45m units (+14.1% yoy).
- Domestic sales dragged by high oil prices, and Geely will add BEVs in 2H26. Domestic sales fell 23.3% yoy to 1,437,811 units in 9M26, which management attributed to higher oil prices dampening internal combustion engine (ICE) car and plug-in hybrid electric vehicle (PHEV) sales, with Galaxy skewed towards PHEVs. The new EV models, eg Galaxy TT and new E5, will boost sales in 2H26. Channel inventory level stands at below one month, implying no need for further destocking, except for certain models in transition. Looking into 2027, Geely expects to increase its market share from 11% in 2026 as China’s auto sales stop falling.
- Exports are offsetting part of the domestic weakness. 9M26 exports of 797,670 units (+169% yoy) are 80% of the full-year target of 1m units. Exports exceeded 100,000 units a month from June. September export dipped 3% mom to 106,685 units, which management attributed to production at Proton in Malaysia. Management expects export at around 100,000 units a month in 4Q26, with the mix shifting to premium models such as the Zeekr 9X. The preliminary 2027 export target is 1m-2m units. The long-term aim is two-thirds of sales overseas, vs 35% in 2026.
Highlights
- 2026 sales will probably miss the 3.45m target on the ongoing run rate.
- Geely targets doubling exports from about 1m to 2m within 1-2 years on model launches, eg iHEV, Zeekr, and overseas capacity.
- Fast-charging, L3 ADAS, and iHEV technologies will drive growth.
- Exports and premium models underpin net profit per vehicle.
- We raise 2026 EPS by 7%, keep 2027 EPS unchanged, and trim 2028 EPS by 3%, based on lower sales estimates of higher profit per vehicle.
- We estimate 3Q26 net profit at Rmb5,525m (+39.5% yoy/+7.9% qoq).
- Maintain BUY and target price of HK$29.00 (10x 2027F PE).
Analysis
- 2026 sales will probably miss the 3.45m-unit target, based on ongoing run rate. 9M26 sales of 2.235m units (+3.0% yoy) make up 64.8% of the full-year target. It requires average sales of 404,840 units/month (+42.2% yoy) in 4Q26 to reach the company’s full-year target of 3.45m units, which seems unlikely. We now expect Geely’s 2026 sales at 3.00m-3.45m units on the ongoing run rate, vs its target of 3.45m units (+14.1% yoy).
- Domestic sales dragged by high oil prices, and Geely will add BEVs in 2H26. Domestic sales fell 23.3% yoy to 1,437,811 units in 9M26, which management attributed to higher oil prices dampening internal combustion engine (ICE) car and plug-in hybrid electric vehicle (PHEV) sales, with Galaxy skewed towards PHEVs. The new EV models, eg Galaxy TT and new E5, will boost sales in 2H26. Channel inventory level stands at below one month, implying no need for further destocking, except for certain models in transition. Looking into 2027, Geely expects to increase its market share from 11% in 2026 as China’s auto sales stop falling.
- Exports are offsetting part of the domestic weakness. 9M26 exports of 797,670 units (+169% yoy) are 80% of the full-year target of 1m units. Exports exceeded 100,000 units a month from June. September export dipped 3% mom to 106,685 units, which management attributed to production at Proton in Malaysia. Management expects export at around 100,000 units a month in 4Q26, with the mix shifting to premium models such as the Zeekr 9X. The preliminary 2027 export target is 1m-2m units. The long-term aim is two-thirds of sales overseas, vs 35% in 2026.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$14.97
HK$29.00
+93.7%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

29 Sept 2026
Alibaba Group (9988 HK): APSARA Conference 2026 Key Takeaways

29 Sept 2026
