Company Coverage
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027
BUY (Maintained)
Current price:
Target price:
Upside:
HK$322.00
HK$508.00
+57.8%
Analyst
Highlights
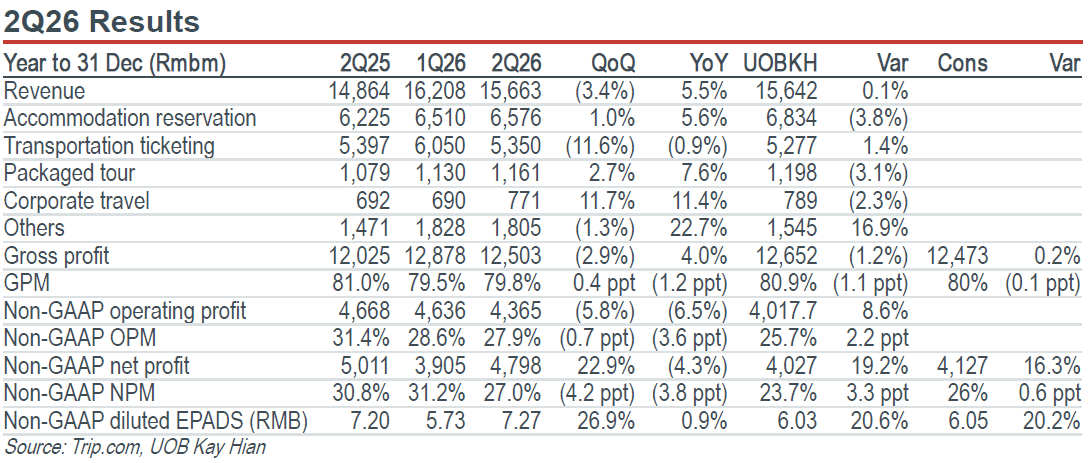
- Trip.com reported in-line 2Q26 results. Total net revenue rose 6% yoy to Rmb15.6b, in line with our expectation. Non-GAAP operating profit declined 6.5% but was above estimates. Non-GAAP net income fell 4.3% yoy to Rmb4.8b, but beat our and consensus estimates by 16-19%. Trip.com guided 3Q26 revenue growth of 1-6% yoy, reflecting weaker domestic travel demand and ongoing regulatory adjustments, with further pressure expected in 4Q26 from a full-quarter regulatory impact.
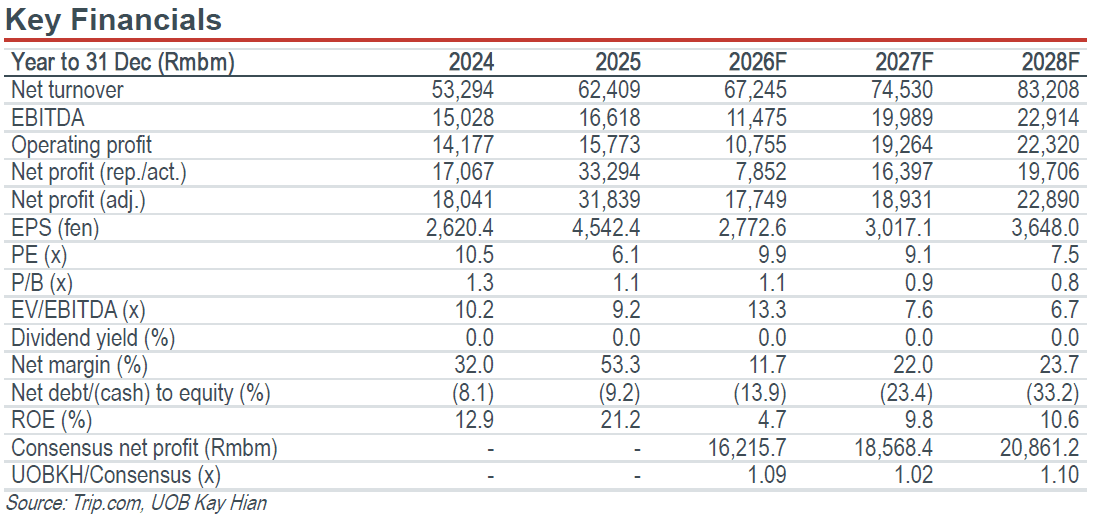
- Maintain BUY with an unchanged target price of HK$508.00 (US$65.00).
Analysis
- Resilient core travel demand, with international business sustaining strong growth. Trip.com’s 2Q26 revenue grew 6% yoy to Rmb15.7b (2Q25: +16%,1Q26: +17%), broadly in line with our estimate. Accommodation reservation revenue rose 6% yoy to Rmb6.6b (2Q25: +21%,1Q26: +17%) driven by higher accommodation reservations, partly offset by Rmb122m of contra-revenue related to the State Administration for Market Regulation penalty. Transportation ticketing revenue declined 1% yoy to Rmb5.4b (2Q25: +11%,1Q26: +12%), mainly due to elevated energy prices and geopolitical volatility. Packaged-tour and corporate travel revenue increased 8% (2Q25: +5%, 1Q26: +19%) and 11% (2Q25: +9%, 1Q26: +20%) yoy to Rmb1.2b and Rmb771m, respectively. The international business remained the key growth driver, with revenue expanding over 50% yoy and inbound travel revenue growing at a high double-digit rate.
- Margins moderated amid higher marketing investment. Gross margin dropped 1.2ppt yoy to 79.8% in 2Q26, due to slowing top-line growth. Non-GAAP operating margin declined 3.6ppt yoy to 27.9%, while sales and marketing expense ratio rose 2.0ppt yoy to 24.1%, reflecting continued investment in Trip.com. Non-GAAP net profit fell 4.3% yoy to Rmb4.8b, but improved 23% qoq, implying a non-GAAP net margin of 27%.
Highlights
- Trip.com reported in-line 2Q26 results. Total net revenue rose 6% yoy to Rmb15.6b, in line with our expectation. Non-GAAP operating profit declined 6.5% but was above estimates. Non-GAAP net income fell 4.3% yoy to Rmb4.8b, but beat our and consensus estimates by 16-19%. Trip.com guided 3Q26 revenue growth of 1-6% yoy, reflecting weaker domestic travel demand and ongoing regulatory adjustments, with further pressure expected in 4Q26 from a full-quarter regulatory impact.
- Maintain BUY with an unchanged target price of HK$508.00 (US$65.00).
Analysis
- Resilient core travel demand, with international business sustaining strong growth. Trip.com’s 2Q26 revenue grew 6% yoy to Rmb15.7b (2Q25: +16%,1Q26: +17%), broadly in line with our estimate. Accommodation reservation revenue rose 6% yoy to Rmb6.6b (2Q25: +21%,1Q26: +17%) driven by higher accommodation reservations, partly offset by Rmb122m of contra-revenue related to the State Administration for Market Regulation penalty. Transportation ticketing revenue declined 1% yoy to Rmb5.4b (2Q25: +11%,1Q26: +12%), mainly due to elevated energy prices and geopolitical volatility. Packaged-tour and corporate travel revenue increased 8% (2Q25: +5%, 1Q26: +19%) and 11% (2Q25: +9%, 1Q26: +20%) yoy to Rmb1.2b and Rmb771m, respectively. The international business remained the key growth driver, with revenue expanding over 50% yoy and inbound travel revenue growing at a high double-digit rate.
- Margins moderated amid higher marketing investment. Gross margin dropped 1.2ppt yoy to 79.8% in 2Q26, due to slowing top-line growth. Non-GAAP operating margin declined 3.6ppt yoy to 27.9%, while sales and marketing expense ratio rose 2.0ppt yoy to 24.1%, reflecting continued investment in Trip.com. Non-GAAP net profit fell 4.3% yoy to Rmb4.8b, but improved 23% qoq, implying a non-GAAP net margin of 27%.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$322.00
HK$508.00
+57.8%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales

12 Oct 2026
Xiaomi Corp (1810 HK): SKYNOAD’s Locked Orders Surpass 70,000 Units

29 Sept 2026