

Company Coverage
Contemporary Amperex Technology Co (300750 CH): Fears Overdone; Bottom Fishing Opportunity Emerges
BUY (Maintained)
Current price:
Target price:
Upside:
Rmb316.36
Rmb585.00
+84.9%
Analyst
Highlights
- CATL’s installations continue to outgrow the market. Order flows remain strong, and capacity utilisation remains tight through year-end.
- The Hungary plant launch is delayed to at least 1Q27, but other plants can cover the shortfall. The Chongqing plant acquisition adds 18GWh in capacity, saves build time, and extends CATL’s coverage to southwest China.
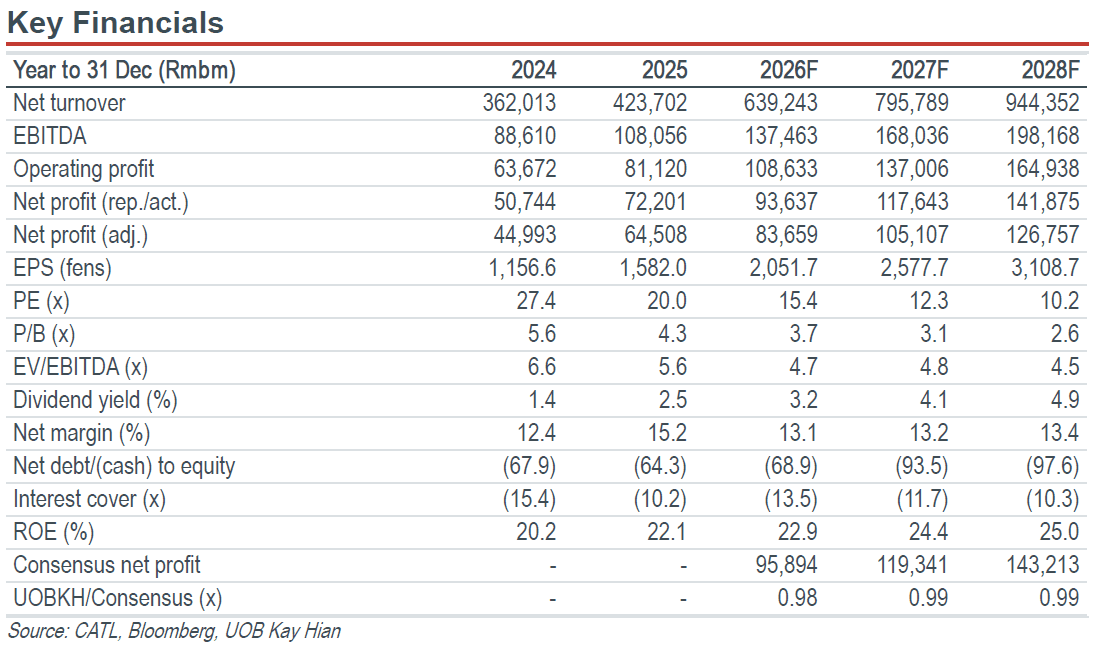
- Fears that OEMs will switch away from CATL are groundless, due to its moats in technology, reliability and brand equity. Maintain BUY and keep the target prices for A-share/H-share at Rmb585.00/HK$675.00. Valuation is attractive at 12.3x 2027F PE.
Analysis
- Installations continue to outgrow the market. According to SNE Research data, Contemporary Amperex Technology Co (CATL) supplied 289.6GWh of global installations in 7M26, up 26.6% yoy against a market that grew 20.4% yoy, lifting its market share by 1.9ppt yoy to 39.9%. Order flows remain strong, and capacity utilisation remains tight through year-end, driven by strong demand for energy storage battery.
- Capacity is running flat out. CATL’s battery capacity reached 525GWh in 1H26, annualised capacity of 1,050GWh already met the 2026 target, and utilisation was 94.9%. A further 764GWh was under construction as of 30 June, and most of it is due to come on stream within two years. At that level of utilisation, there is almost no headroom until the new lines arrive.
- The launch of the Hungary plant delayed to 1Q27. Hungarian regulators stopped work in the laser-cutting, winding and cell-drying workshops on 25 August after nine employees showed elevated nickel readings, and confirmed the suspension on 31 August; commissioning may continue, but no cells may be produced. The launch of Phase 1 (40GWh out of the 100GWh total designed capacity) will probably be delayed to at least 1Q27, which removes 8-12GWh, or 0.8-1.2%, from our 2026 volume, and Mercedes-Benz VLE supply has moved to China. The 5GWh module plant opened in May and the Arnstadt plant in Germany both keep running; CATL has 15 production bases worldwide that can make up the shortfall.
Highlights
- CATL’s installations continue to outgrow the market. Order flows remain strong, and capacity utilisation remains tight through year-end.
- The Hungary plant launch is delayed to at least 1Q27, but other plants can cover the shortfall. The Chongqing plant acquisition adds 18GWh in capacity, saves build time, and extends CATL’s coverage to southwest China.
- Fears that OEMs will switch away from CATL are groundless, due to its moats in technology, reliability and brand equity. Maintain BUY and keep the target prices for A-share/H-share at Rmb585.00/HK$675.00. Valuation is attractive at 12.3x 2027F PE.
Analysis
- Installations continue to outgrow the market. According to SNE Research data, Contemporary Amperex Technology Co (CATL) supplied 289.6GWh of global installations in 7M26, up 26.6% yoy against a market that grew 20.4% yoy, lifting its market share by 1.9ppt yoy to 39.9%. Order flows remain strong, and capacity utilisation remains tight through year-end, driven by strong demand for energy storage battery.
- Capacity is running flat out. CATL’s battery capacity reached 525GWh in 1H26, annualised capacity of 1,050GWh already met the 2026 target, and utilisation was 94.9%. A further 764GWh was under construction as of 30 June, and most of it is due to come on stream within two years. At that level of utilisation, there is almost no headroom until the new lines arrive.
- The launch of the Hungary plant delayed to 1Q27. Hungarian regulators stopped work in the laser-cutting, winding and cell-drying workshops on 25 August after nine employees showed elevated nickel readings, and confirmed the suspension on 31 August; commissioning may continue, but no cells may be produced. The launch of Phase 1 (40GWh out of the 100GWh total designed capacity) will probably be delayed to at least 1Q27, which removes 8-12GWh, or 0.8-1.2%, from our 2026 volume, and Mercedes-Benz VLE supply has moved to China. The 5GWh module plant opened in May and the Arnstadt plant in Germany both keep running; CATL has 15 production bases worldwide that can make up the shortfall.
BUY (Maintained)
Current price:
Target price:
Upside:
Rmb316.36
Rmb585.00
+84.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Sept 2026
Pateo Connect Technology (2889 HK): 1H26: Core Results In Line, But GAAP Bottom-line Pressured By Share-based Compensation

1 Sept 2026
Z.AI Co (2513 HK): 1H26: Revenue Miss And Mix-Driven Margin Pressure, But ARR Momentum Remains Robust

28 Aug 2026
