

Company Coverage
Mobvista Inc (1860 HK): A Fast-growing Global AI-driven Adtech Platform
NOT RATED
Current price:
Target price:
Upside:
HK$10.70
n.a.
n.a.
Analyst
Analyst
Highlights
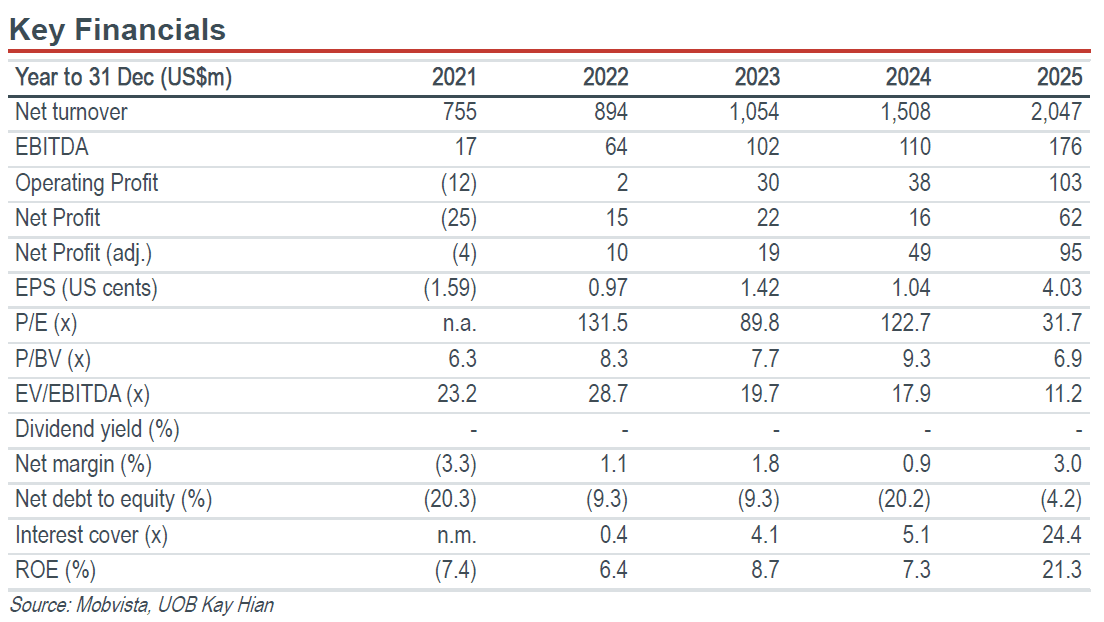
- Mobvista is a fast-growing AI-driven ad-tech platform connecting advertisers with publishers. It registered a 28% revenue four-year CAGR in 2021-25 as third-party platforms gained shares from top-tier media and advertising platforms.
- The launch of its new AI infrastructure in Oct 26 should significantly improve its model capabilities, with initial tests suggesting close to 100-fold overall efficiency improvement.
- The board approved a new share repurchase plan of up to HK$300m open-market repurchases (up to 10% of its outstanding shares), backed by its strong net cash position of US$178m as of end-Jun 26. Mobvista is trading at 22.7x 2026F PE and 13.4x 2027F PE, based on Bloomberg consensus.
Analysis
- Mintegral: A fast-growing AI-driven ad-tech platform. Mintegral connects advertisers with publishers, both primarily gaming app developers in the mid-to-long-tail market. Since 2023, it has expanded smart bidding from shallow events (such as installs) to deep events based on post-install user behaviour). In 1H26, smart-bidding solutions accounted for over 90% of Mintegral’s revenue.
- Third-party platforms gaining market share from Google and Meta. Over the past five years, gaming advertisers have shifted budgets away from major media and advertising platforms because: a) Apple’s privacy policy (IDFA) changes restricted user-level cross-app tracking in 2021; b) advertisers began sharing first-party data and evaluating campaigns by return on ad spend, rather than installs; and c) ad auctions shifted from historical effective cost per mille rankings towards dynamic, value-based bidding. As such, competition became more performance-driven, enabling gaming-focused third-party platforms such as AppLovin, Unity and Mintegral to gain market shares on model capabilities.
Highlights
- Mobvista is a fast-growing AI-driven ad-tech platform connecting advertisers with publishers. It registered a 28% revenue four-year CAGR in 2021-25 as third-party platforms gained shares from top-tier media and advertising platforms.
- The launch of its new AI infrastructure in Oct 26 should significantly improve its model capabilities, with initial tests suggesting close to 100-fold overall efficiency improvement.
- The board approved a new share repurchase plan of up to HK$300m open-market repurchases (up to 10% of its outstanding shares), backed by its strong net cash position of US$178m as of end-Jun 26. Mobvista is trading at 22.7x 2026F PE and 13.4x 2027F PE, based on Bloomberg consensus.
Analysis
- Mintegral: A fast-growing AI-driven ad-tech platform. Mintegral connects advertisers with publishers, both primarily gaming app developers in the mid-to-long-tail market. Since 2023, it has expanded smart bidding from shallow events (such as installs) to deep events based on post-install user behaviour). In 1H26, smart-bidding solutions accounted for over 90% of Mintegral’s revenue.
- Third-party platforms gaining market share from Google and Meta. Over the past five years, gaming advertisers have shifted budgets away from major media and advertising platforms because: a) Apple’s privacy policy (IDFA) changes restricted user-level cross-app tracking in 2021; b) advertisers began sharing first-party data and evaluating campaigns by return on ad spend, rather than installs; and c) ad auctions shifted from historical effective cost per mille rankings towards dynamic, value-based bidding. As such, competition became more performance-driven, enabling gaming-focused third-party platforms such as AppLovin, Unity and Mintegral to gain market shares on model capabilities.
NOT RATED
Current price:
Target price:
Upside:
HK$10.70
n.a.
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

16 Sept 2026
Contemporary Amperex Technology Co (300750 CH): Fears Overdone; Bottom Fishing Opportunity Emerges

1 Sept 2026
Z.AI Co (2513 HK): 1H26: Revenue Miss And Mix-Driven Margin Pressure, But ARR Momentum Remains Robust

2 Sept 2026
Pateo Connect Technology (2889 HK): 1H26: Core Results In Line, But GAAP Bottom-line Pressured By Share-based Compensation
Our latest research
16 Sept 2026
Contemporary Amperex Technology Co (300750 CH): Fears Overdone; Bottom Fishing Opportunity Emerges
16 Sept 2026
TA: Cathay Pacific Airways (0293 HK) / Sino Land (0083 HK)
15 Sept 2026