

Company Coverage
BYD Electronics (285 HK): 3Q26: Consumer Electronics Continues To Drag Profitability
SELL (Maintained)
Current price:
Target price:
Upside:
HK$22.24
HK$14.50
-34.8%
Analyst
Analyst
Highlights
- BYDE reported weak results again. Revenue of Rmb45b was in line, but margins missed consensus as consumer devices continued to drag profitability. Bottom line registered a 35% sequential recovery at Rmb537m but still missed consensus expectation by 18%.
- Management sees strong opportunities in its AI-infrastructure related business and expects robust growth through 2027, but the consumer electronic business seems to have more downside going forward.
- Maintain SELL and keep target price unchanged at HK$14.50.
Analysis
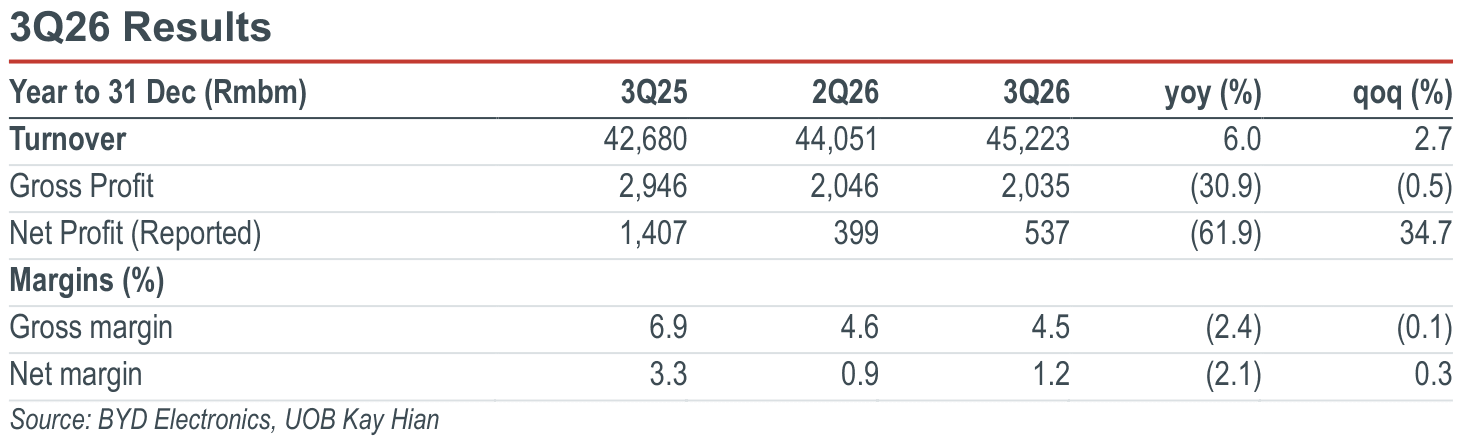
- Weak sets of results yet again as the smart terminal segment saw no signs of recovery. BYD Electronics’ (BYDE) 3Q26 revenue grew 6.0% yoy and 2.7% qoq to Rmb45,223m, which is largely in line with growth driven by the auto segment and the emerging AI server ODM business. This is however more than offset by a sustained weakness in the smart terminal segment – the lower capacity utilisation and pricing pressure had led to a 2.4ppt yoy and 0.1ppt qoq compression in gross margins to 4.5%, which is a 0.4ppt miss vs consensus estimates but largely in line with our expectations. On the brighter side, BYDE stated that forex impacts had improved sequentially, and as a result, net profit declined 61.9% yoy but recovered 34.7% qoq to Rmb537m, which is still 17.7% below consensus estimate and largely in line with ours.
Highlights
- BYDE reported weak results again. Revenue of Rmb45b was in line, but margins missed consensus as consumer devices continued to drag profitability. Bottom line registered a 35% sequential recovery at Rmb537m but still missed consensus expectation by 18%.
- Management sees strong opportunities in its AI-infrastructure related business and expects robust growth through 2027, but the consumer electronic business seems to have more downside going forward.
- Maintain SELL and keep target price unchanged at HK$14.50.
Analysis
- Weak sets of results yet again as the smart terminal segment saw no signs of recovery. BYD Electronics’ (BYDE) 3Q26 revenue grew 6.0% yoy and 2.7% qoq to Rmb45,223m, which is largely in line with growth driven by the auto segment and the emerging AI server ODM business. This is however more than offset by a sustained weakness in the smart terminal segment – the lower capacity utilisation and pricing pressure had led to a 2.4ppt yoy and 0.1ppt qoq compression in gross margins to 4.5%, which is a 0.4ppt miss vs consensus estimates but largely in line with our expectations. On the brighter side, BYDE stated that forex impacts had improved sequentially, and as a result, net profit declined 61.9% yoy but recovered 34.7% qoq to Rmb537m, which is still 17.7% below consensus estimate and largely in line with ours.
SELL (Maintained)
Current price:
Target price:
Upside:
HK$22.24
HK$14.50
-34.8%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
NAURA Technology Group (002371 CH): 3Q26: Temporary Weakness Due To Component Shortage; Demand Pushed Back To 4Q26

26 Oct 2026
Lens Technology (6613 HK): 3Q26: Core Business Weakness And Emerging-Business Investment Pressure Earnings

14 Oct 2026
Lenovo Group (992 HK): PC Shipments Miss Expectations In 3Q26
Our latest research
30 Oct 2026
TA: CITIC (0267 HK) / Geely Automobile (0175 HK)

30 Oct 2026
Budweiser APAC (1876 HK): 3Q26: Revenue In Line But EBITDA Misses

30 Oct 2026