

Company Coverage
NAURA Technology Group (002371 CH): 3Q26: Temporary Weakness Due To Component Shortage; Demand Pushed Back To 4Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb497.30
Rmb783.20
+57.5%
Rmb930.00
Analyst
Analyst
Highlights
- NAURA was impacted by component shortages in 3Q26, with revenue/net profit missing consensus estimates by 16%/9% respectively.
- This is however temporary as the company kept its full-year revenue target of Rmb49b unchanged, indicating confidence in a meaningful improvement in the supply shortage situation.
- Maintain BUY and cut target price to Rmb783.20. Our positive view on NAURA’s exposure to China’s WFE opportunities remains unchanged.
Analysis
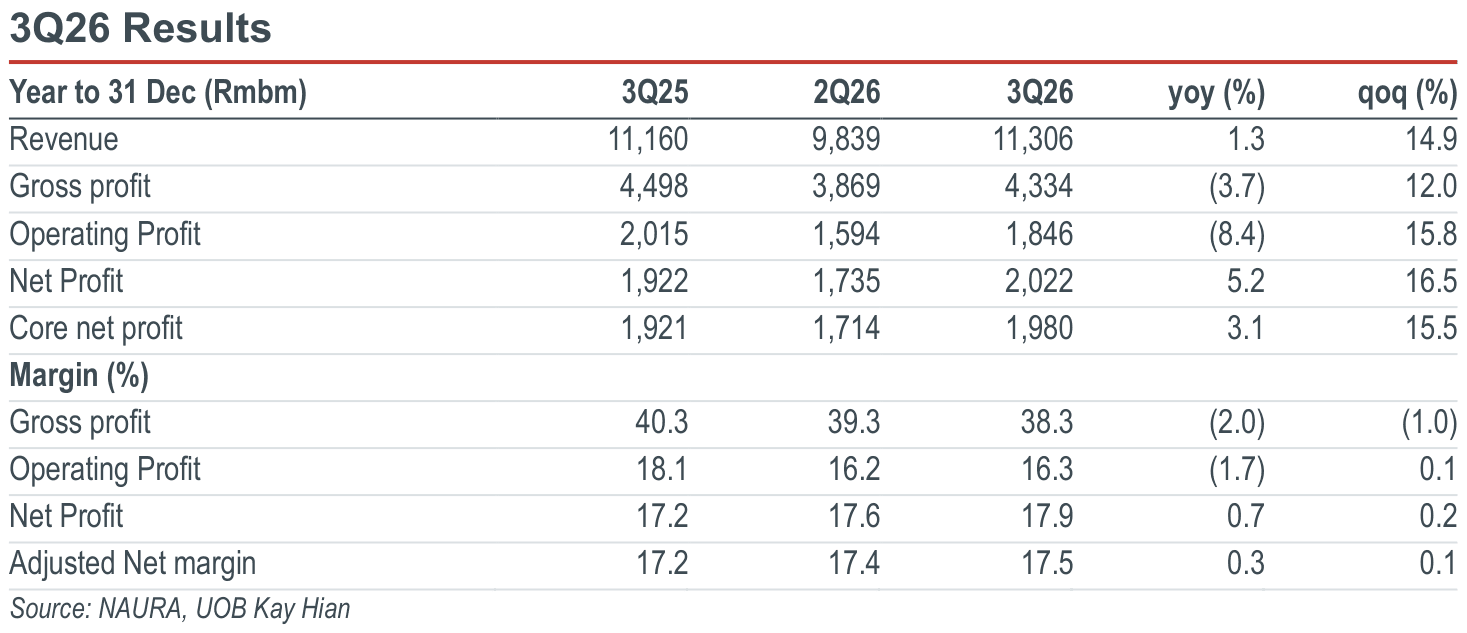
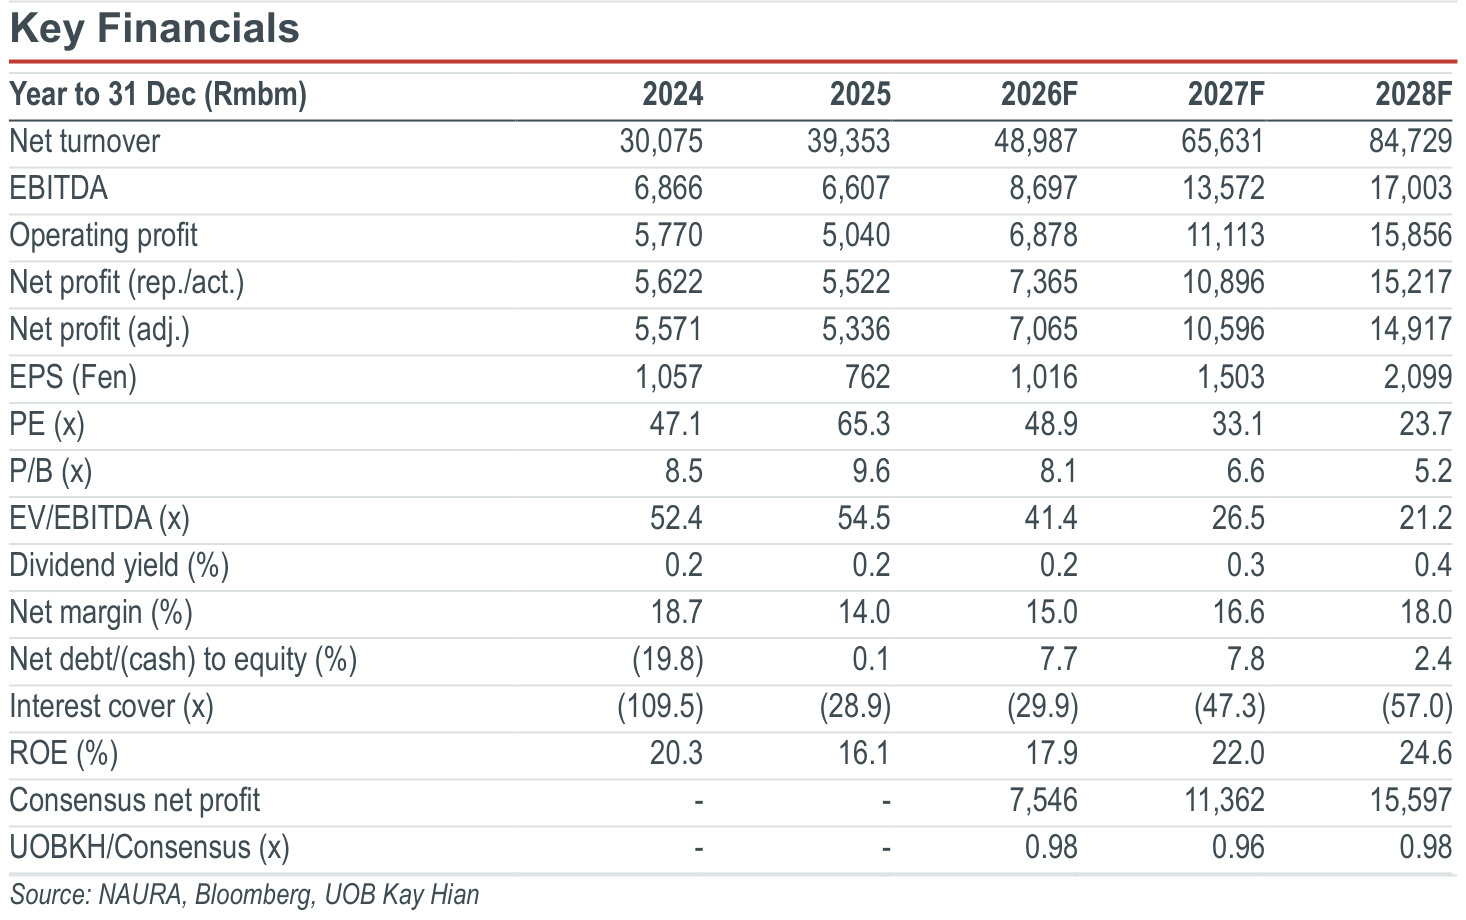
- Component shortages led to a weaker quarter. In 3Q26, NAURA Technology Group’s (NAURA) revenue grew 1.3% yoy and 14.9% qoq to Rmb11,306m, which is 16.2% below consensus, as component shortages constrained near-term shipments. Gross margin continued to trend down, declining 2.0ppt yoy and 1.0ppt qoq to 38.3%, which is 1.6ppt below consensus, caused by higher component costs for new products still in the early volume ramp-up phrase with a worse operating scale. As a result, operating profit fell 8.4% yoy to Rmb1,846m, while net profit rose 5.2% yoy and 16.5% qoq to Rmb2,022m, missing consensus by 9.2%.
Highlights
- NAURA was impacted by component shortages in 3Q26, with revenue/net profit missing consensus estimates by 16%/9% respectively.
- This is however temporary as the company kept its full-year revenue target of Rmb49b unchanged, indicating confidence in a meaningful improvement in the supply shortage situation.
- Maintain BUY and cut target price to Rmb783.20. Our positive view on NAURA’s exposure to China’s WFE opportunities remains unchanged.
Analysis
- Component shortages led to a weaker quarter. In 3Q26, NAURA Technology Group’s (NAURA) revenue grew 1.3% yoy and 14.9% qoq to Rmb11,306m, which is 16.2% below consensus, as component shortages constrained near-term shipments. Gross margin continued to trend down, declining 2.0ppt yoy and 1.0ppt qoq to 38.3%, which is 1.6ppt below consensus, caused by higher component costs for new products still in the early volume ramp-up phrase with a worse operating scale. As a result, operating profit fell 8.4% yoy to Rmb1,846m, while net profit rose 5.2% yoy and 16.5% qoq to Rmb2,022m, missing consensus by 9.2%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb497.30
Rmb783.20
+57.5%
Rmb930.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Oct 2026
Lens Technology (6613 HK): 3Q26: Core Business Weakness And Emerging-Business Investment Pressure Earnings

14 Oct 2026
Lenovo Group (992 HK): PC Shipments Miss Expectations In 3Q26

30 Oct 2026
BYD Electronics (285 HK): 3Q26: Consumer Electronics Continues To Drag Profitability
Our latest research
30 Oct 2026
TA: CITIC (0267 HK) / Geely Automobile (0175 HK)

30 Oct 2026
Budweiser APAC (1876 HK): 3Q26: Revenue In Line But EBITDA Misses
30 Oct 2026