

Company Coverage
Sunny Optical (2382 HK): NDR Takeaways: 2026 Guidance Reiterated With Pan-IoT And AR Glasses Driving Growth
BUY (Maintained)
Current price:
Target price:
Upside:
HK$62.70
HK$106.00
+69.1%
Analyst
Analyst
Highlights
- At the non-deal roadshow for Sunny held in Taipei last week, investors’ key focuses were primarily related to Sunny’s progress in optical interconnect components, share gains and design wins from the US smartphone client, concerns about Android businesses, as well as opportunities from the fast-growing pan-IoT business.
- Sunny is upbeat on the edge-AI driven Pan-IoT business, expects the XR business to recover in 2027 and targets stable growth in the automotive business. The smartphone business will continue to face headwinds but targets flattish yoy growth in 2026-27 on share gains and specs upgrades.
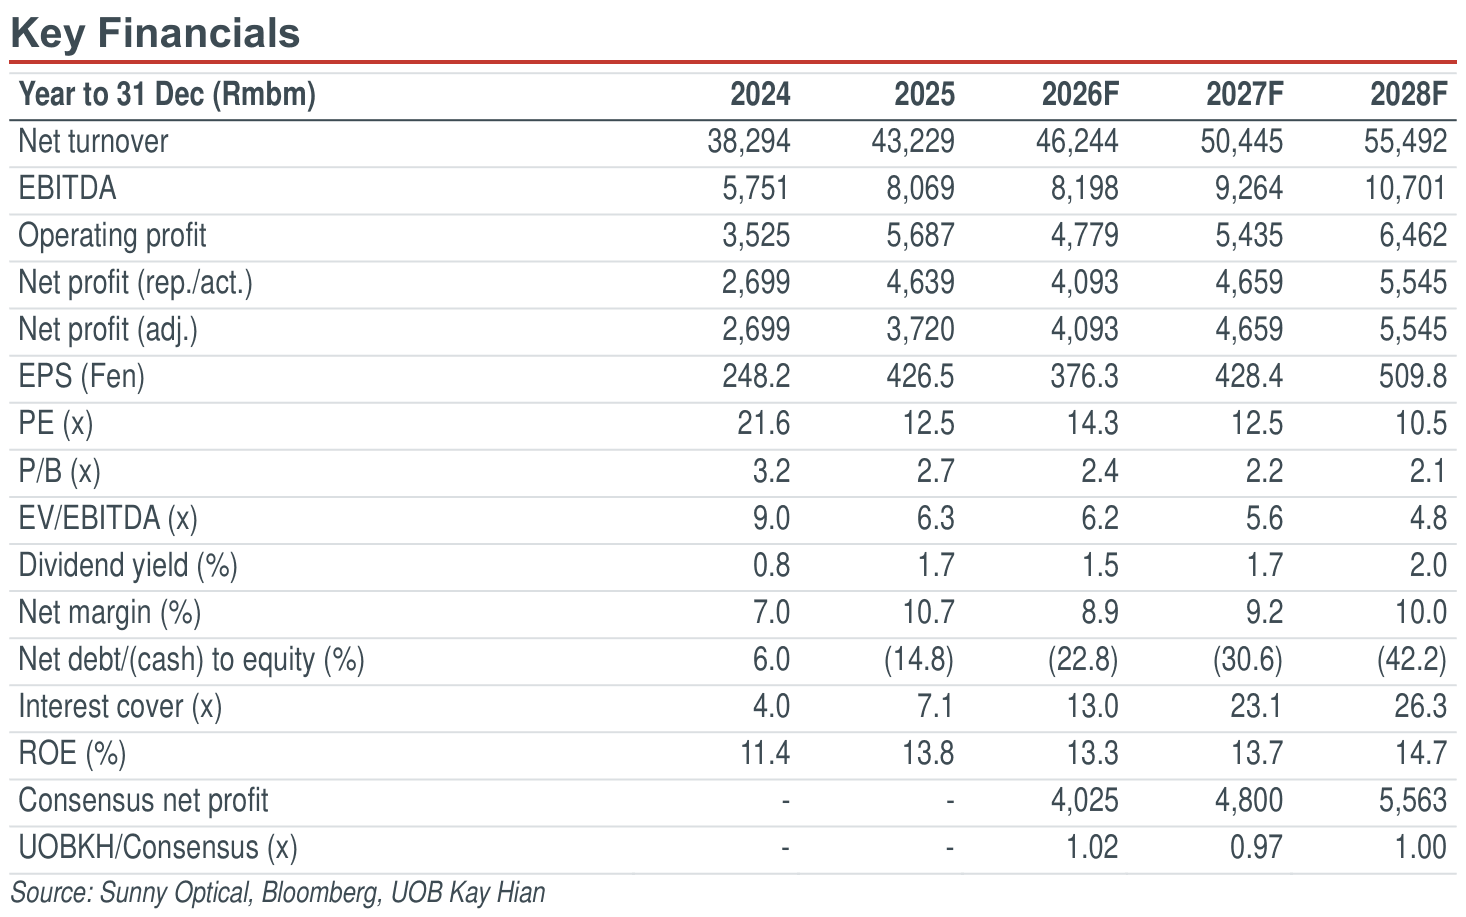
- Maintain BUY and target price of HK$106.00, pegged to 21.1x 2027F PE.
Analysis
- Management targets flattish revenue growth for handset business in 2026-27. Management highlighted industry expectations of a 10-20% yoy decline in smartphone shipment volume in 2026, with 2H26 seeing an accelerated decline given a higher impact from cost hikes during the period. The trend will continue into 2027 and shipment volume may decline by another double-digit % yoy. The silver lining is that Sunny Optical (Sunny) sees sustained demand for high-end/flagship products with stronger-than-expected demand from the Chinese Android brand’s recent launches. Sunny is also targeting to expand its share in the premium brands, including Huawei, Samsung and Apple which should perform significantly better than the mass-market focused Chinese Android brands. Notably, Sunny had managed to become one of the two major suppliers of the key US client’s main camera lens + variable aperture supplier alongside Largan (3008 TT/Not) which implies share gain vs the previous generation. That said, additional new design wins for the flagship smartphone products in the US client are likely pushed back to 2028/29, and instead the growth from this client will come from the expanded adoption of variable aperture specs to more SKUs.
- As such, the company is still targeting a flattish smartphone revenue growth, with share gains and specs upgrades offsetting sharp volume declines. Margins will remain range bound between 25-30% for lens and 6-8% for modules, although the overall tone seems to lean towards the lower bound of the range in the near future.
Highlights
- At the non-deal roadshow for Sunny held in Taipei last week, investors’ key focuses were primarily related to Sunny’s progress in optical interconnect components, share gains and design wins from the US smartphone client, concerns about Android businesses, as well as opportunities from the fast-growing pan-IoT business.
- Sunny is upbeat on the edge-AI driven Pan-IoT business, expects the XR business to recover in 2027 and targets stable growth in the automotive business. The smartphone business will continue to face headwinds but targets flattish yoy growth in 2026-27 on share gains and specs upgrades.
- Maintain BUY and target price of HK$106.00, pegged to 21.1x 2027F PE.
Analysis
- Management targets flattish revenue growth for handset business in 2026-27. Management highlighted industry expectations of a 10-20% yoy decline in smartphone shipment volume in 2026, with 2H26 seeing an accelerated decline given a higher impact from cost hikes during the period. The trend will continue into 2027 and shipment volume may decline by another double-digit % yoy. The silver lining is that Sunny Optical (Sunny) sees sustained demand for high-end/flagship products with stronger-than-expected demand from the Chinese Android brand’s recent launches. Sunny is also targeting to expand its share in the premium brands, including Huawei, Samsung and Apple which should perform significantly better than the mass-market focused Chinese Android brands. Notably, Sunny had managed to become one of the two major suppliers of the key US client’s main camera lens + variable aperture supplier alongside Largan (3008 TT/Not) which implies share gain vs the previous generation. That said, additional new design wins for the flagship smartphone products in the US client are likely pushed back to 2028/29, and instead the growth from this client will come from the expanded adoption of variable aperture specs to more SKUs.
- As such, the company is still targeting a flattish smartphone revenue growth, with share gains and specs upgrades offsetting sharp volume declines. Margins will remain range bound between 25-30% for lens and 6-8% for modules, although the overall tone seems to lean towards the lower bound of the range in the near future.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$62.70
HK$106.00
+69.1%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

16 Sept 2026
Contemporary Amperex Technology Co (300750 CH): Fears Overdone; Bottom Fishing Opportunity Emerges

2 Sept 2026
Pateo Connect Technology (2889 HK): 1H26: Core Results In Line, But GAAP Bottom-line Pressured By Share-based Compensation
16 Sept 2026
Mobvista Inc (1860 HK): A Fast-growing Global AI-driven Adtech Platform
Our latest research

29 Sept 2026
Alibaba Group (9988 HK): APSARA Conference 2026 Key Takeaways
29 Sept 2026
TA: Henderson Land Development (0012 HK) / China Longyuan Power Group (0916 HK)

28 Sept 2026