

Company Coverage
Li Ning (2331 HK): Full-Year Guidance Maintained; Considering Proposing Special Dividend
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$12.84
HK$19.50
+51.9%
HK$21.80
Analyst
Analyst
Highlights
- Li Ning’ low single-digit yoy decline in retail sell-through in 3Q26 was below management’s expectation, with offline discounts deepening by a low single digit yoy. For 4Q26, management highlights weather conditions and 11.11 as the key swing factors. However, with the full-year targets already incorporating a cautious view, management maintained its guidance of low single-digit revenue growth and a mid- to high single-digit net margin.
- The launch timeline for Curry’s signature shoes has yet to be determined. Management expects the full Curry product portfolio to be rolled out after 4Q27, at which point it anticipates a more meaningful contribution to sales.
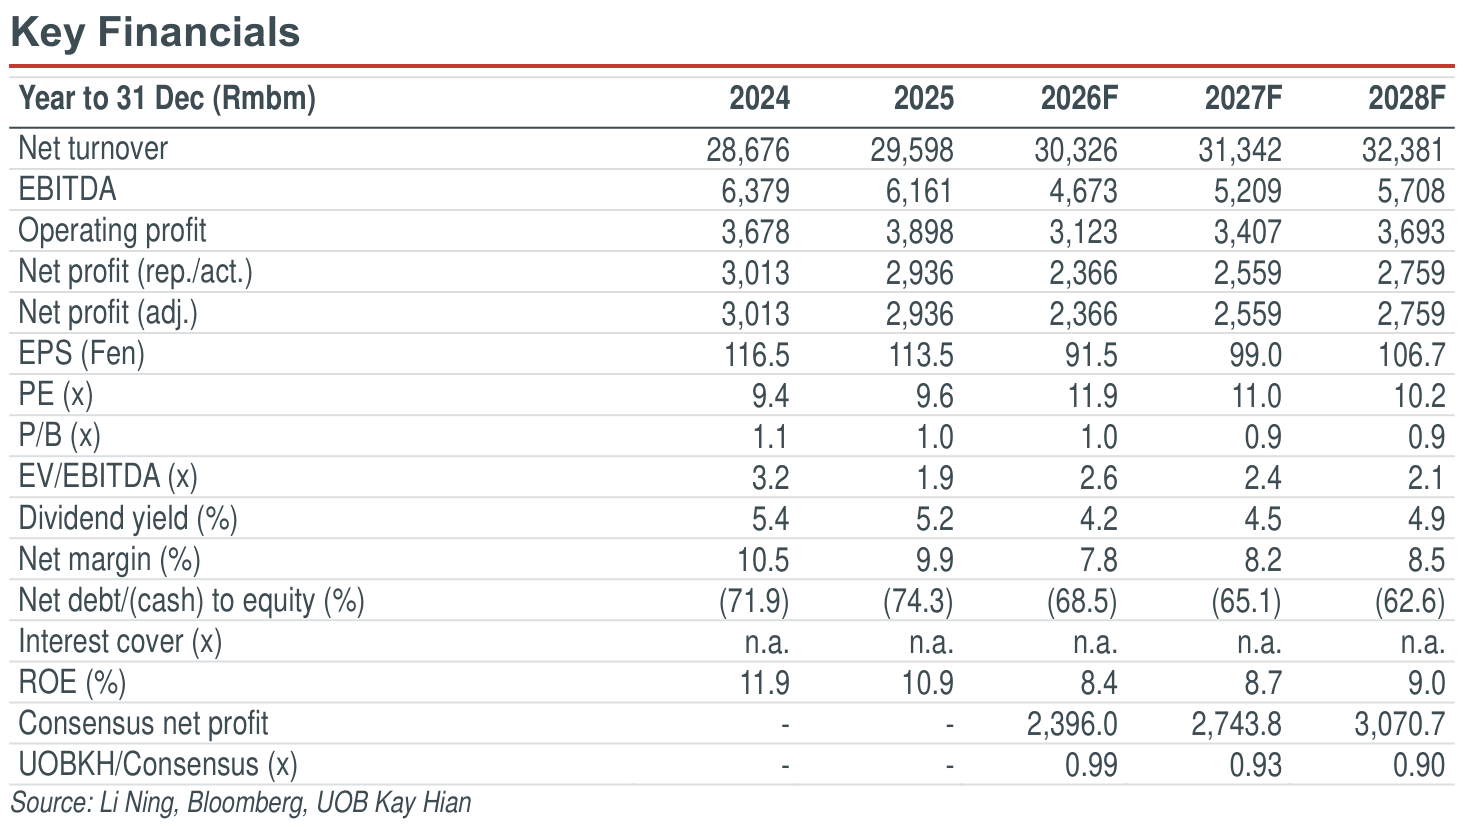
- The company will hold a board meeting on 5 November to consider and approve a special dividend. Meanwhile, management believes that the regular payout ratio of 50% remains appropriate in the near term. Maintain BUY but cut target price by 11% to HK$19.50.
Analysis
- 3Q26 retail sell-through remained weak. In 3Q26, Li Ning recorded a low single-digit yoy decline in retail sell-through (excluding Li Ning Young) (vs a low single-digit decline in 2Q26), below management’s expectation, due to softer consumption and extreme weather. Including Li Ning Young, which recorded double-digit sell-through growth, total sell-through would be flat yoy (vs flat yoy in 2Q26). By channel, the offline channel registered a mid-single-digit decline, with retail remaining broadly flat and wholesale down by mid-single-digits. E-commerce grew by high single-digits, supported by short-term promotions such as influencer live-selling.
- Expect discounts to remain stable qoq in 4Q26, but yoy pressure to ease, helped by a low base; year-end inventory targeted at 4.0-4.5 months. In 3Q26, offline discounts deepened by a low single-digit yoy and slightly qoq to around 40% off, while online discounts deepened slightly yoy but remained stable qoq. As of end-3Q26, the inventory level edged up to 5-6 months (vs close to four months at end-2Q26), although it remained stable yoy due to seasonal restocking, with the running category facing the greatest inventory and discount pressure. Looking ahead, management expects discounts to remain largely stable qoq in 4Q26, although yoy pressure is expected to ease vs 3Q26, supported by an easier base, and targets an inventory level of 4.0-4.5 months by year-end.
Highlights
- Li Ning’ low single-digit yoy decline in retail sell-through in 3Q26 was below management’s expectation, with offline discounts deepening by a low single digit yoy. For 4Q26, management highlights weather conditions and 11.11 as the key swing factors. However, with the full-year targets already incorporating a cautious view, management maintained its guidance of low single-digit revenue growth and a mid- to high single-digit net margin.
- The launch timeline for Curry’s signature shoes has yet to be determined. Management expects the full Curry product portfolio to be rolled out after 4Q27, at which point it anticipates a more meaningful contribution to sales.
- The company will hold a board meeting on 5 November to consider and approve a special dividend. Meanwhile, management believes that the regular payout ratio of 50% remains appropriate in the near term. Maintain BUY but cut target price by 11% to HK$19.50.
Analysis
- 3Q26 retail sell-through remained weak. In 3Q26, Li Ning recorded a low single-digit yoy decline in retail sell-through (excluding Li Ning Young) (vs a low single-digit decline in 2Q26), below management’s expectation, due to softer consumption and extreme weather. Including Li Ning Young, which recorded double-digit sell-through growth, total sell-through would be flat yoy (vs flat yoy in 2Q26). By channel, the offline channel registered a mid-single-digit decline, with retail remaining broadly flat and wholesale down by mid-single-digits. E-commerce grew by high single-digits, supported by short-term promotions such as influencer live-selling.
- Expect discounts to remain stable qoq in 4Q26, but yoy pressure to ease, helped by a low base; year-end inventory targeted at 4.0-4.5 months. In 3Q26, offline discounts deepened by a low single-digit yoy and slightly qoq to around 40% off, while online discounts deepened slightly yoy but remained stable qoq. As of end-3Q26, the inventory level edged up to 5-6 months (vs close to four months at end-2Q26), although it remained stable yoy due to seasonal restocking, with the running category facing the greatest inventory and discount pressure. Looking ahead, management expects discounts to remain largely stable qoq in 4Q26, although yoy pressure is expected to ease vs 3Q26, supported by an easier base, and targets an inventory level of 4.0-4.5 months by year-end.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$12.84
HK$19.50
+51.9%
HK$21.80
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Oct 2026
Xtep International Holdings(1368 HK): Core Xtep Brand’s Offline Sell-Through Remains Under Pressure; Reiterates Full-year Targets

22 Oct 2026
Anta Sports (2020 HK): 3Q26 Will Be A Softer Quarter But Solid Start To 4Q26; Confident In Achieving Full-Year Targets

21 Oct 2026
CR Mixc Lifestyle (1209 HK): 3Q26 Operational Update: Double-digit Earnings Growth In Line With Expectations; New Mall Openings On Track
Our latest research

27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00
27 Oct 2026
TA: MTR Corp (0066 HK) / Sun Hung Kai Properties (0016 HK)

27 Oct 2026