

Company Coverage
ZTE Corporation (763 HK): 3Q26: Operating Profit Dragged Down By Weak Margins And High Operating Expenses
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$19.10
HK$19.20
0.5%
HK$22.30
Analyst
Analyst
Highlights
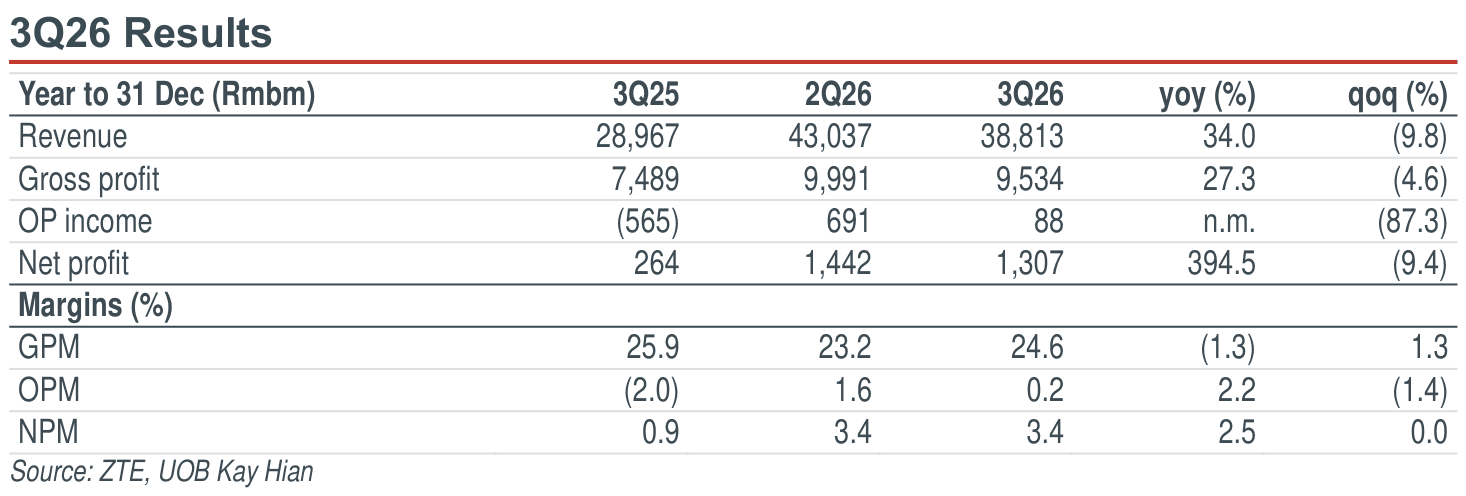
- 3Q26 revenue rose 34% yoy to Rmb38.8b and reported net profit surged 395% yoy to Rmb1.3b, 6%/30% above consensus, but operating profit missed by 79% on higher operating expenses.
- 4Q26 should remain flattish qoq as weak domestic telco offsets renewed sequential growth in compute; 2027 looks like another year of moderate growth, led by overseas telco and compute businesses.
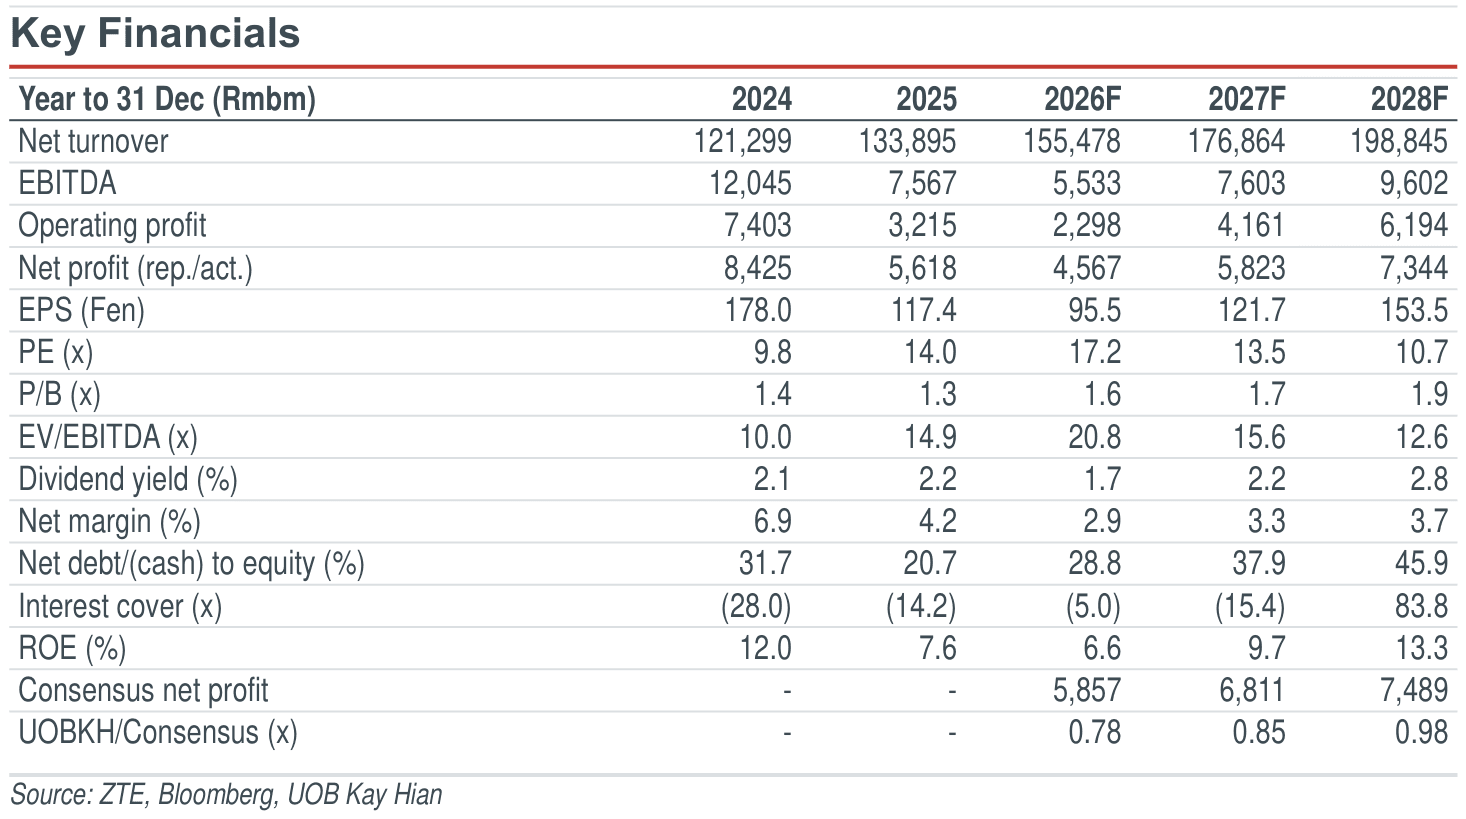
- Maintain HOLD and cut target price to HK$19.20 as we lower our 2026-28 net profit estimates by 6.3%/13.8%/4.8% respectively.
Analysis
- Revenue beat but operating profit missed. Revenue grew 34.0% yoy but fell 9.8% qoq to Rmb38,813m, beating consensus by 5.8%. Gross margin remained low at 24.6% (-1.3ppt yoy, +1.3ppt qoq), in line with consensus. Operating profit dropped 87.3% qoq to Rmb88m, missing consensus by 79.3% due to higher-than-expected operating expenses. Reported net profit rose 394.5% yoy but fell 9.4% qoq to Rmb1,307m, beating consensus by 30.2%, supported by Rmb501m in fair-value gains on trading financial assets. This translates to a core net profit of RMB593m, down 53.8% qoq, although it turned positive versus the same period last year.
- Compute-related revenue moderated sequentially by around 5.2% qoq to Rmb17b in 3Q26, due to a high-base effect, as 2Q26’s delivery also included orders from 1Q26 that were pushed back into the quarter amid memory supply shortages. Note that ZTE Corporation (ZTE) has stocked up on ample memory supplies as seen in the Rmb18b sequential increase in inventory in 3Q26, as the company expects further price hikes going forward. This also means that order deliveries should be much smoother going forward.
Highlights
- 3Q26 revenue rose 34% yoy to Rmb38.8b and reported net profit surged 395% yoy to Rmb1.3b, 6%/30% above consensus, but operating profit missed by 79% on higher operating expenses.
- 4Q26 should remain flattish qoq as weak domestic telco offsets renewed sequential growth in compute; 2027 looks like another year of moderate growth, led by overseas telco and compute businesses.
- Maintain HOLD and cut target price to HK$19.20 as we lower our 2026-28 net profit estimates by 6.3%/13.8%/4.8% respectively.
Analysis
- Revenue beat but operating profit missed. Revenue grew 34.0% yoy but fell 9.8% qoq to Rmb38,813m, beating consensus by 5.8%. Gross margin remained low at 24.6% (-1.3ppt yoy, +1.3ppt qoq), in line with consensus. Operating profit dropped 87.3% qoq to Rmb88m, missing consensus by 79.3% due to higher-than-expected operating expenses. Reported net profit rose 394.5% yoy but fell 9.4% qoq to Rmb1,307m, beating consensus by 30.2%, supported by Rmb501m in fair-value gains on trading financial assets. This translates to a core net profit of RMB593m, down 53.8% qoq, although it turned positive versus the same period last year.
- Compute-related revenue moderated sequentially by around 5.2% qoq to Rmb17b in 3Q26, due to a high-base effect, as 2Q26’s delivery also included orders from 1Q26 that were pushed back into the quarter amid memory supply shortages. Note that ZTE Corporation (ZTE) has stocked up on ample memory supplies as seen in the Rmb18b sequential increase in inventory in 3Q26, as the company expects further price hikes going forward. This also means that order deliveries should be much smoother going forward.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$19.10
HK$19.20
0.5%
HK$22.30
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

22 Oct 2026
Fuyao Glass (3606 HK): 3Q26: Earnings Dragged By Higher Sea Freight Costs And One-off Expenses; Cut Target Price To HK$77.00

27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00

22 Oct 2026
Contemporary Amperex Technology Co (300750 CH): 3Q26: Earnings Miss Due To Delayed Pass-through Of Tax Hikes
Our latest research
27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00
27 Oct 2026
TA: MTR Corp (0066 HK) / Sun Hung Kai Properties (0016 HK)

27 Oct 2026