Company Coverage
Fuyao Glass (3606 HK): 3Q26: Earnings Dragged By Higher Sea Freight Costs And One-off Expenses; Cut Target Price To HK$77.00
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$51.75
HK$77.00
48.8%
HK$84.00
Analyst
Highlights
- 3Q26 core net profit dropped 4.1% yoy and 13.1% qoq to Rmb2.22b, missing estimates, due to higher sea freight costs, and one-off expenses.
- We expect margins to recover modestly in 4Q26, based on easing sea freight costs, flat soda ash prices, and the absence of one-off expenses.
- Sales volume and ASP will be driven by the accelerating industry consolidation, and vehicle intelligentisation overseas.
- We trim our 2026-28 net profit forecasts by 11%/8%/8% to Rmb8.58b/Rmb10.73b/Rmb12.12b respectively on lower margins.
- Maintain BUY and cut target price from HK$84.00 to HK$77.00.
Analysis
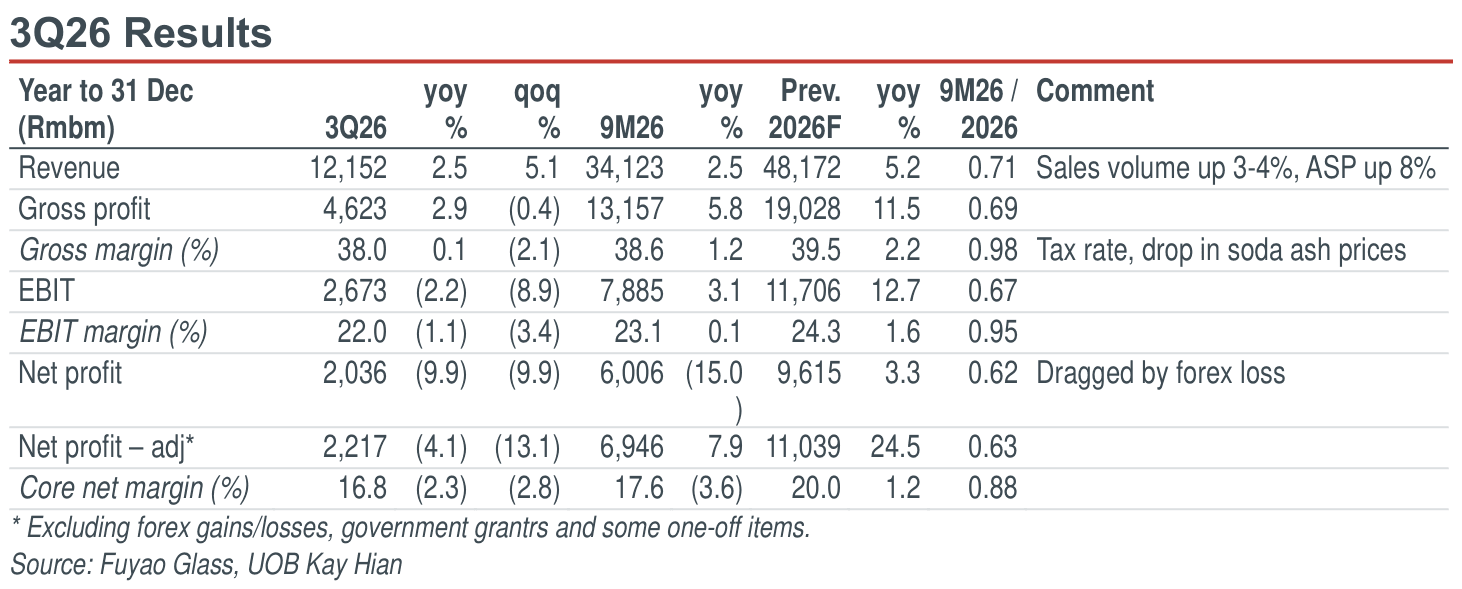
- 3Q26 results missed estimates with GAAP net profit of Rmb2,036m (-9.9% yoy/-9.9% qoq) and adjusted net profit of Rmb2,217m (-4.1% yoy/-13.1% qoq), vs consensus estimate of Rmb2.65b. Fuyao Glass’ (FYG) 3Q26 earnings miss stemmed from: a) spikes in sea freight costs, b) Rmb78m in product quality defect compensation, and c) US$14.34b (~Rmb100m) in expenses related to the fire at Phase 2 of the US plant.
- Revenue grew 2.5% yoy and 5.1% qoq to Rmb14.05b, missing estimates on ASP. 3Q26 ASP per sqm only soared about 4.5% yoy, vs a 7.4% yoy hike in 1H26, due to the appreciation of the renminbi. Stripping out forex impact, 3Q26 ASP per sqm rose 6.5% yoy. 9M26 ASP per sqm rose 6.4% yoy, boosting revenue by 2.5% yoy to Rmb34.12b (71% of our full-year 2026 estimate), despite sales volume decline.
- Revenue grew 2.5% yoy and 5.1% qoq to Rmb14.05b, missing estimates on ASP. 3Q26 ASP per sqm only soared about 4.5% yoy, vs a 7.4% yoy hike in 1H26, due to the appreciation of the renminbi. Stripping out forex impact, 3Q26 ASP per sqm rose 6.5% yoy. 9M26 ASP per sqm rose 6.4% yoy, boosting revenue by 2.5% yoy to Rmb34.12b (71% of our full-year 2026 estimate), despite sales volume decline.
Highlights
- 3Q26 core net profit dropped 4.1% yoy and 13.1% qoq to Rmb2.22b, missing estimates, due to higher sea freight costs, and one-off expenses.
- We expect margins to recover modestly in 4Q26, based on easing sea freight costs, flat soda ash prices, and the absence of one-off expenses.
- Sales volume and ASP will be driven by the accelerating industry consolidation, and vehicle intelligentisation overseas.
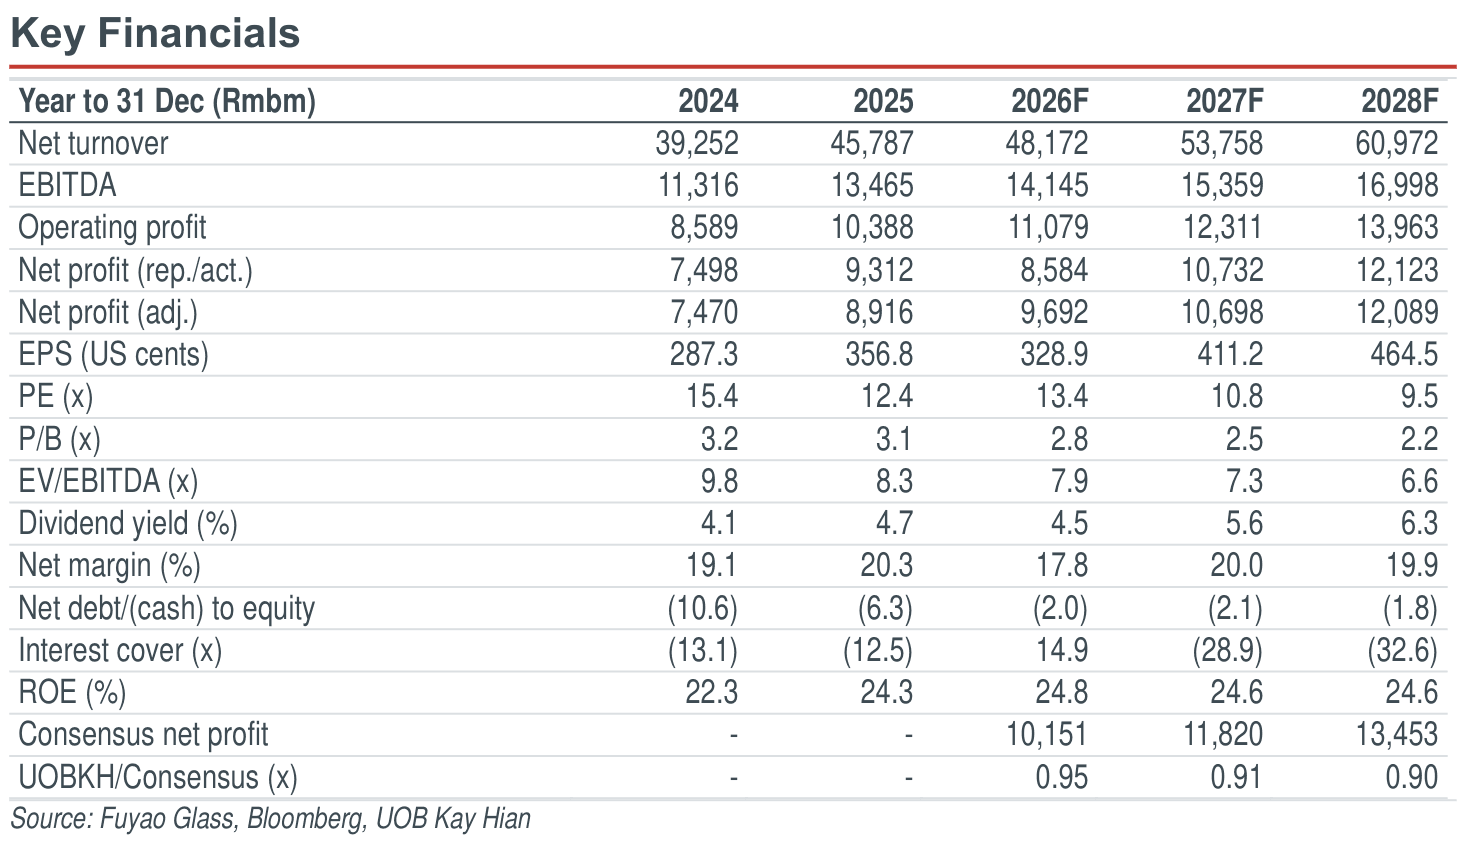
- We trim our 2026-28 net profit forecasts by 11%/8%/8% to Rmb8.58b/Rmb10.73b/Rmb12.12b respectively on lower margins.
- Maintain BUY and cut target price from HK$84.00 to HK$77.00.
Analysis
- 3Q26 results missed estimates with GAAP net profit of Rmb2,036m (-9.9% yoy/-9.9% qoq) and adjusted net profit of Rmb2,217m (-4.1% yoy/-13.1% qoq), vs consensus estimate of Rmb2.65b. Fuyao Glass’ (FYG) 3Q26 earnings miss stemmed from: a) spikes in sea freight costs, b) Rmb78m in product quality defect compensation, and c) US$14.34b (~Rmb100m) in expenses related to the fire at Phase 2 of the US plant.
- Revenue grew 2.5% yoy and 5.1% qoq to Rmb14.05b, missing estimates on ASP. 3Q26 ASP per sqm only soared about 4.5% yoy, vs a 7.4% yoy hike in 1H26, due to the appreciation of the renminbi. Stripping out forex impact, 3Q26 ASP per sqm rose 6.5% yoy. 9M26 ASP per sqm rose 6.4% yoy, boosting revenue by 2.5% yoy to Rmb34.12b (71% of our full-year 2026 estimate), despite sales volume decline.
- Revenue grew 2.5% yoy and 5.1% qoq to Rmb14.05b, missing estimates on ASP. 3Q26 ASP per sqm only soared about 4.5% yoy, vs a 7.4% yoy hike in 1H26, due to the appreciation of the renminbi. Stripping out forex impact, 3Q26 ASP per sqm rose 6.5% yoy. 9M26 ASP per sqm rose 6.4% yoy, boosting revenue by 2.5% yoy to Rmb34.12b (71% of our full-year 2026 estimate), despite sales volume decline.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$51.75
HK$77.00
48.8%
HK$84.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

22 Oct 2026
Contemporary Amperex Technology Co (300750 CH): 3Q26: Earnings Miss Due To Delayed Pass-through Of Tax Hikes

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales

21 Oct 2026
CR Mixc Lifestyle (1209 HK): 3Q26 Operational Update: Double-digit Earnings Growth In Line With Expectations; New Mall Openings On Track
Our latest research
22 Oct 2026
Contemporary Amperex Technology Co (300750 CH): 3Q26: Earnings Miss Due To Delayed Pass-through Of Tax Hikes

22 Oct 2026
Anta Sports (2020 HK): 3Q26 Will Be A Softer Quarter But Solid Start To 4Q26; Confident In Achieving Full-Year Targets
22 Oct 2026