

Company Coverage
PDD Holdings (PDD US): 3Q26: Better-than-expected Marketing Revenue Growth; Earnings Beat On Lower Marketing Spend On Temu
BUY (Maintained)
Current price:
Target price:
Upside:
US$77.45
US$115.00
48.5%
Analyst
Analyst
Highlights
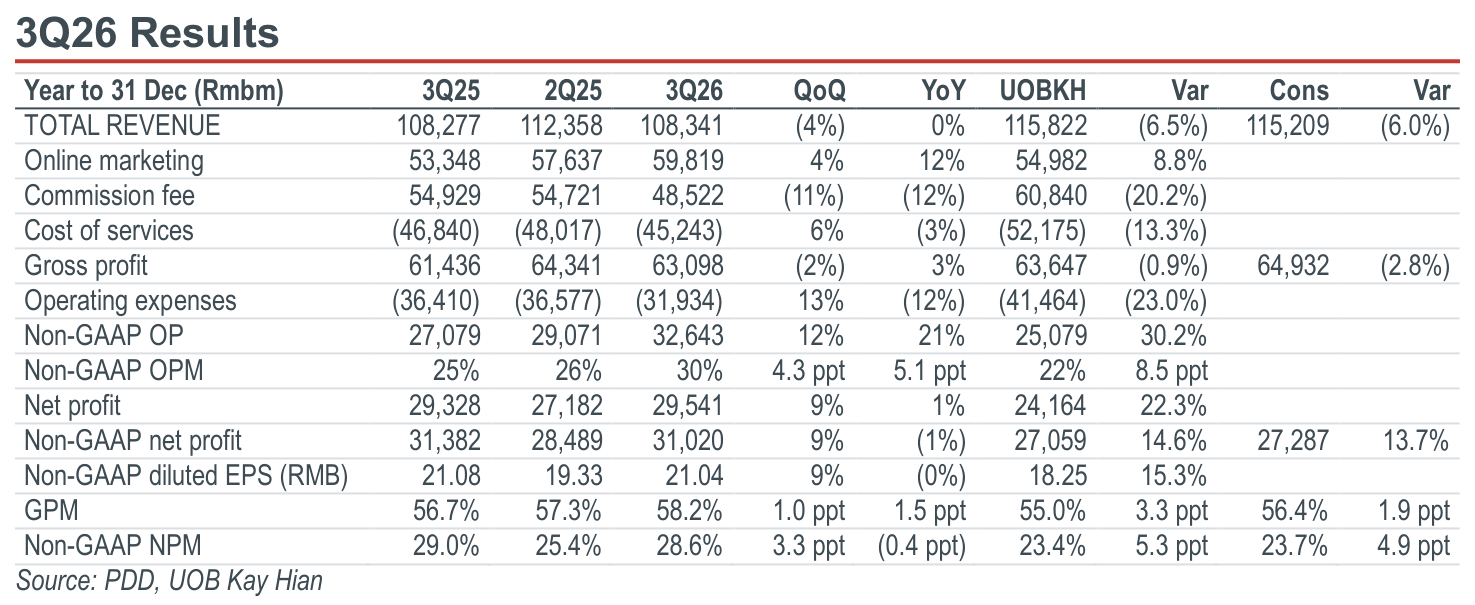
- PDD delivered a solid 3Q26 profit beat. Revenue was flat yoy at Rmb108.3b, around 6% below our and consensus estimates, as resilient domestic e-commerce monetisation offset Temu’s slowing growth. Lower sales and marketing expenses lifted non-GAAP operating profit by 20.5% yoy to Rmb32.6b, while non-GAAP net profit dropped 1.2% yoy to Rmb31.0b, 14-15% above our and consensus estimates.
- Maintain BUY with an unchanged target price of US$115.00.
Analysis
- Online marketing revenue beat our estimate, while transaction services revenue fell short. Online marketing services and other revenue grew 12.1% yoy to Rmb59.8b in 3Q26, accelerating from 3.5% yoy in 2Q26 and coming in 8.8% above our estimate, suggesting stronger-than-expected domestic monetisation. Transaction services revenue fell 11.7% yoy to Rmb48.5b, reversing from the 13.3% yoy growth in 2Q26 and coming in 20.2% below our estimate. The shortfall more than offset the online marketing beat, leaving group revenue broadly flat yoy and 6.5% below our estimate. Management said its global business continues to adapt to evolving trade and regulatory conditions while deepening supply chain investment.
- Strong profit beat on cost discipline. Gross margin expanded 1.5ppt yoy to 58.2% as cost of revenue fell 3.4% yoy while revenue was broadly flat. Non-GAAP operating profit rose 20.5% yoy to Rmb32.6b (vs 5% growth in 2Q26), 30.2% above our estimate, while non-GAAP operating margin expanded 5.1ppt yoy to 30.1%. The margin improvement was supported by a 16.6% yoy decline in sales and marketing expenses to Rmb25.3b. Non-GAAP net profit fell 1.2% yoy to Rmb31.0b as lower interest and investment income (Rmb5.4b vs Rmb8.6b in 3Q25) and higher income tax expenses (Rmb6.6b vs Rmb4.0b in 3Q25) offset the operating profit gains.
Highlights
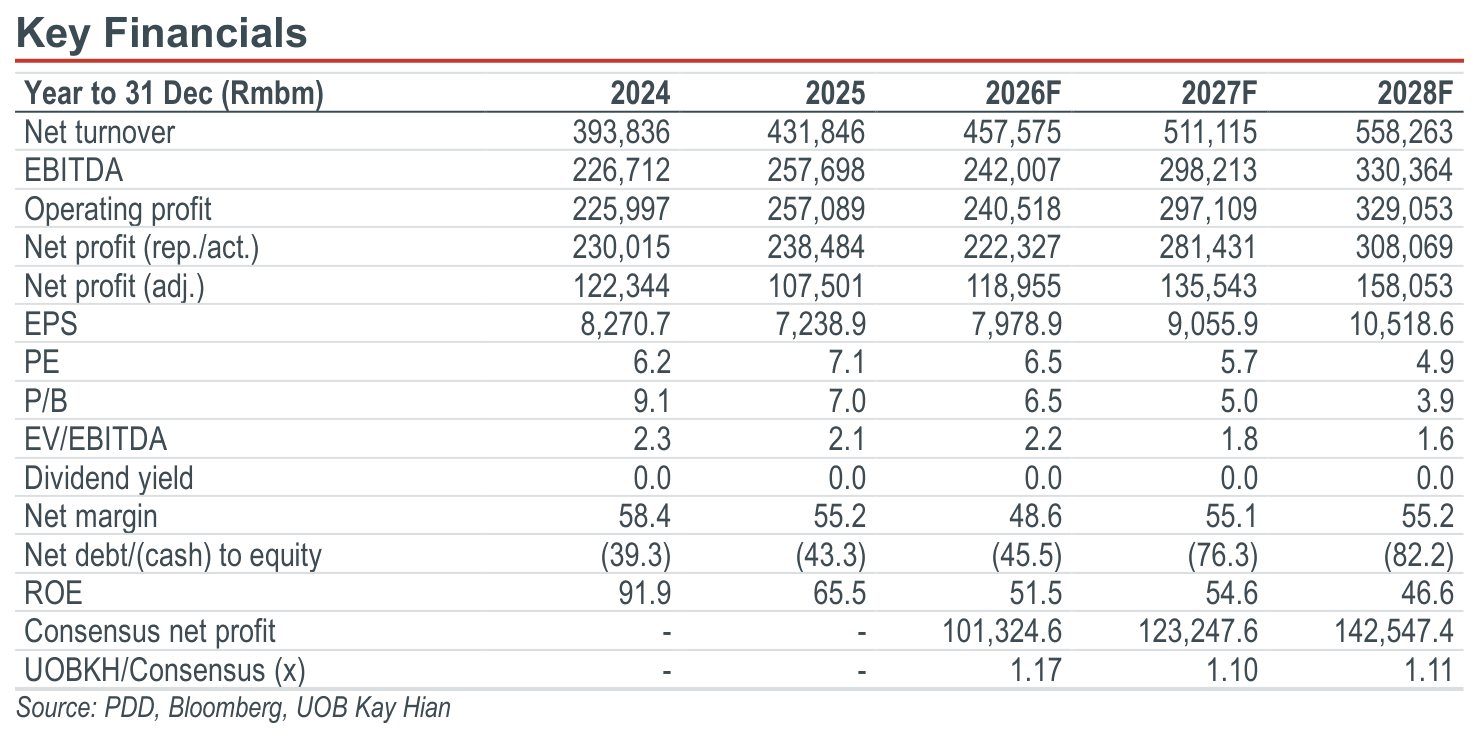
- PDD delivered a solid 3Q26 profit beat. Revenue was flat yoy at Rmb108.3b, around 6% below our and consensus estimates, as resilient domestic e-commerce monetisation offset Temu’s slowing growth. Lower sales and marketing expenses lifted non-GAAP operating profit by 20.5% yoy to Rmb32.6b, while non-GAAP net profit dropped 1.2% yoy to Rmb31.0b, 14-15% above our and consensus estimates.
- Maintain BUY with an unchanged target price of US$115.00.
Analysis
- Online marketing revenue beat our estimate, while transaction services revenue fell short. Online marketing services and other revenue grew 12.1% yoy to Rmb59.8b in 3Q26, accelerating from 3.5% yoy in 2Q26 and coming in 8.8% above our estimate, suggesting stronger-than-expected domestic monetisation. Transaction services revenue fell 11.7% yoy to Rmb48.5b, reversing from the 13.3% yoy growth in 2Q26 and coming in 20.2% below our estimate. The shortfall more than offset the online marketing beat, leaving group revenue broadly flat yoy and 6.5% below our estimate. Management said its global business continues to adapt to evolving trade and regulatory conditions while deepening supply chain investment.
- Strong profit beat on cost discipline. Gross margin expanded 1.5ppt yoy to 58.2% as cost of revenue fell 3.4% yoy while revenue was broadly flat. Non-GAAP operating profit rose 20.5% yoy to Rmb32.6b (vs 5% growth in 2Q26), 30.2% above our estimate, while non-GAAP operating margin expanded 5.1ppt yoy to 30.1%. The margin improvement was supported by a 16.6% yoy decline in sales and marketing expenses to Rmb25.3b. Non-GAAP net profit fell 1.2% yoy to Rmb31.0b as lower interest and investment income (Rmb5.4b vs Rmb8.6b in 3Q25) and higher income tax expenses (Rmb6.6b vs Rmb4.0b in 3Q25) offset the operating profit gains.
BUY (Maintained)
Current price:
Target price:
Upside:
US$77.45
US$115.00
48.5%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


