

Company Coverage
Alibaba Group (9988 HK): 2Q27: Cloud Revenue Beat; Margin Expansion; FCF Outflow Narrows
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$80.55
HK$134.00
66.4%
HK$189.00
Analyst
Analyst
Highlights
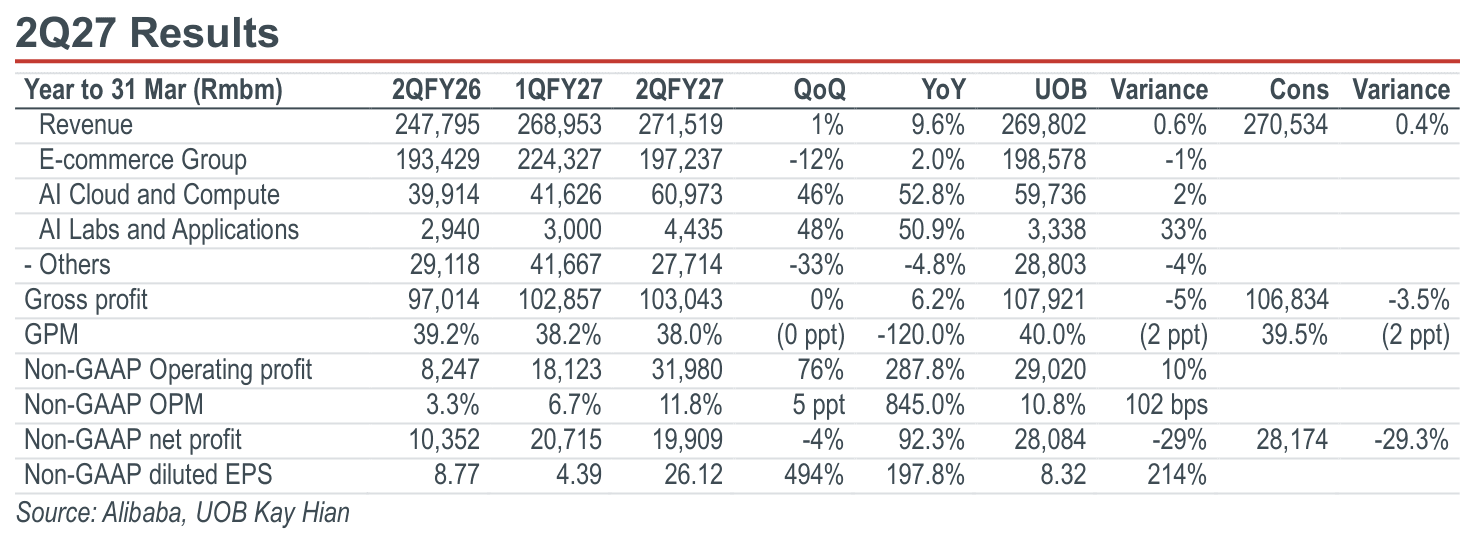
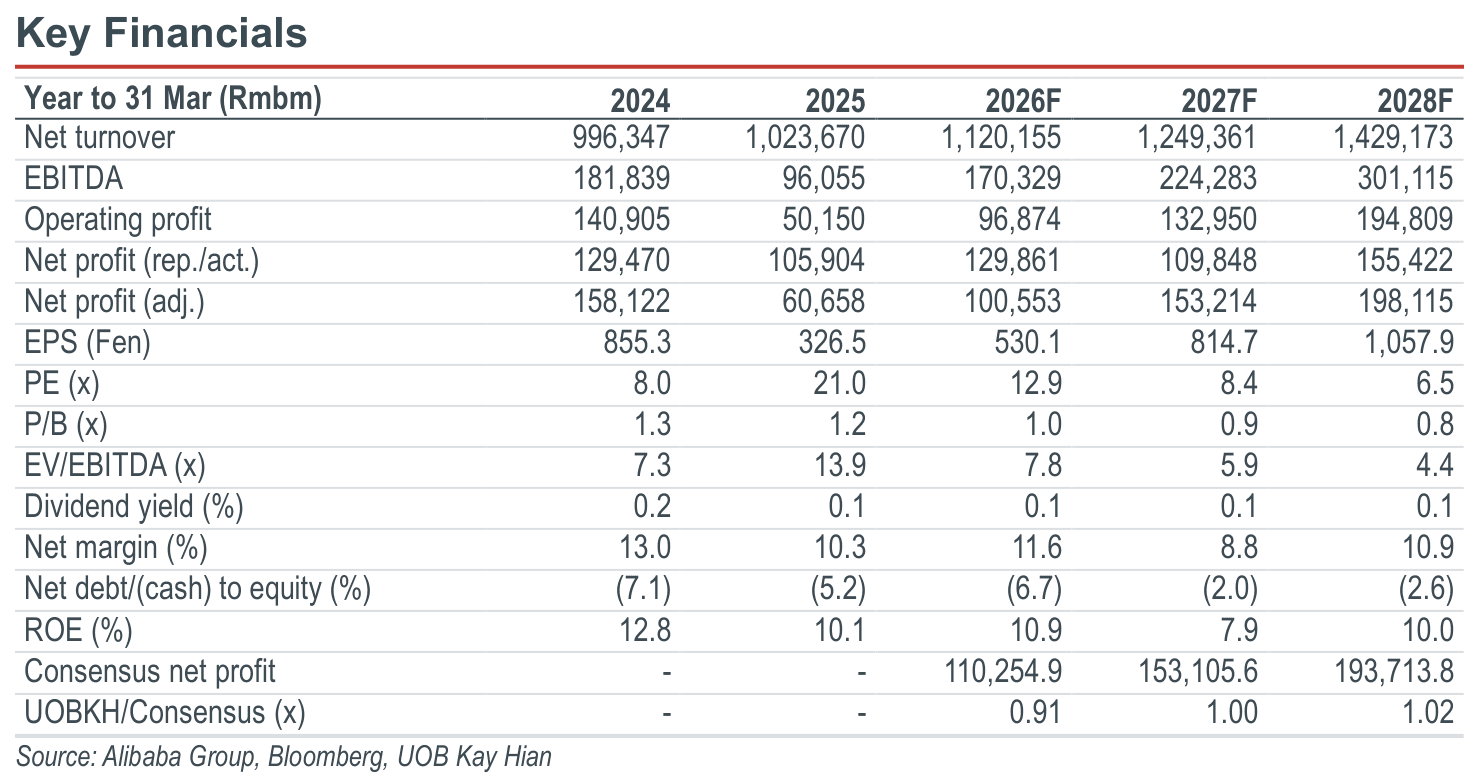
- Alibaba’s 2QFY27 results were mixed. Revenue rose 9.6% yoy to Rmb271.5b, broadly in line with our and consensus estimates. Adjusted EBITA more than doubled yoy to Rmb32.6b, beating our estimate by 6.1%, supported by a higher cloud EBITA margin and narrower quick commerce losses. Non-GAAP net profit rose 92.3% yoy to Rmb19.9b but missed our and consensus by 29%. Capex reached Rmb50.5b (+60% yoy), down from Rmb67.7b last quarter. Maintain BUY with a lower target price of HK$134.00 (US$137.00).
Analysis
- E-commerce revenue broadly in line, with narrower quick commerce losses. In 2QFY27, Alibaba e-commerce group revenue rose 2% yoy to Rmb197.2b. Customer management revenue (CMR) declined 5% yoy or grew 1% on a like-for-like basis excluding the contra-revenue impact of the new business development programme. China quick commerce revenue rose 22% yoy to Rmb58.8b, led by Freshippo. E-commerce group adjusted EBITA rose 243% yoy to Rmb38.9b, mainly on narrower China quick commerce losses as Taobao Instant Commerce continued to improve its unit economics.
- Cloud growth accelerated with stronger profitability. AI cloud & compute revenue rose 53% yoy (vs. 45% in 1QFY27), driven by 67% growth (vs 45% in 1QFY27) in recurring external revenue, and ahead of management’s prior guidance of over 50%. Adjusted EBITA increased 121% yoy to Rmb8.8b, with margin expanding to 14.5% from 11.6% in 1QFY27. AI-related product revenue reached Rmb17.9b in 2QFY27, equivalent to a US$10.7b annualised run rate and approximately 38% of external cloud revenue. Management expects cloud revenue growth of 30-45% yoy in FY28 and over 50% yoy in CY28.
Highlights
- Alibaba’s 2QFY27 results were mixed. Revenue rose 9.6% yoy to Rmb271.5b, broadly in line with our and consensus estimates. Adjusted EBITA more than doubled yoy to Rmb32.6b, beating our estimate by 6.1%, supported by a higher cloud EBITA margin and narrower quick commerce losses. Non-GAAP net profit rose 92.3% yoy to Rmb19.9b but missed our and consensus by 29%. Capex reached Rmb50.5b (+60% yoy), down from Rmb67.7b last quarter. Maintain BUY with a lower target price of HK$134.00 (US$137.00).
Analysis
- E-commerce revenue broadly in line, with narrower quick commerce losses. In 2QFY27, Alibaba e-commerce group revenue rose 2% yoy to Rmb197.2b. Customer management revenue (CMR) declined 5% yoy or grew 1% on a like-for-like basis excluding the contra-revenue impact of the new business development programme. China quick commerce revenue rose 22% yoy to Rmb58.8b, led by Freshippo. E-commerce group adjusted EBITA rose 243% yoy to Rmb38.9b, mainly on narrower China quick commerce losses as Taobao Instant Commerce continued to improve its unit economics.
- Cloud growth accelerated with stronger profitability. AI cloud & compute revenue rose 53% yoy (vs. 45% in 1QFY27), driven by 67% growth (vs 45% in 1QFY27) in recurring external revenue, and ahead of management’s prior guidance of over 50%. Adjusted EBITA increased 121% yoy to Rmb8.8b, with margin expanding to 14.5% from 11.6% in 1QFY27. AI-related product revenue reached Rmb17.9b in 2QFY27, equivalent to a US$10.7b annualised run rate and approximately 38% of external cloud revenue. Management expects cloud revenue growth of 30-45% yoy in FY28 and over 50% yoy in CY28.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$80.55
HK$134.00
66.4%
HK$189.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

18 Nov 2026
JD.com (9618 HK): 3Q26: Operating Beat On Margin Expansion And FD Loss Reduction; Retail Returns To Growth

19 Nov 2026
Tencent Holdings (700 HK): 3Q26: Higher AI Costs Result In Operating Profit Miss and Weigh on FCF

17 Nov 2026
Baidu Inc (9888 HK) - 3Q26: Earnings Beat; AI Cloud Growth Cushions Ad Weakness
Our latest research

20 Nov 2026
NetEase (9999 HK): 3Q26: Revenue And Earnings Miss On Softer Games; Gross Margin Expands
20 Nov 2026
TA: Semiconductor Manufacturing International (0981 HK) / Meituan (3690 HK)

20 Nov 2026