

Company Coverage
JD.com (9618 HK): 3Q26: Operating Beat On Margin Expansion And FD Loss Reduction; Retail Returns To Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$105.20
HK$138.00
31.2%
HK$148.00
Analyst
Analyst
Highlights
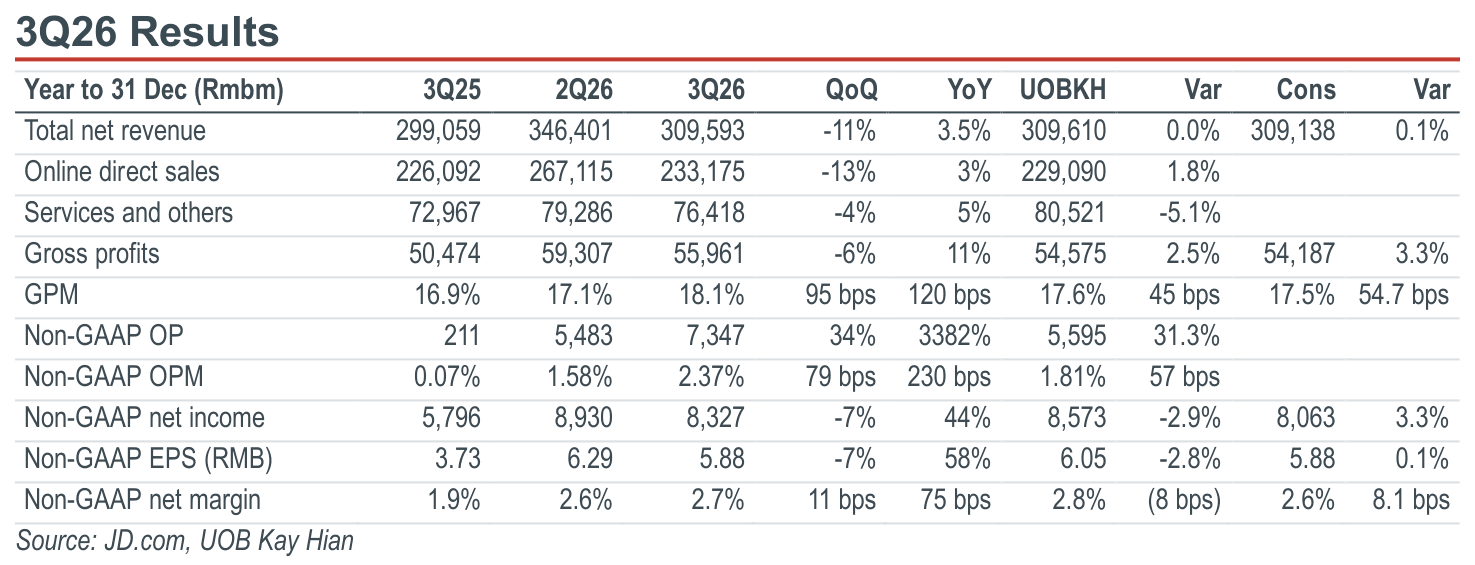
- JD’s 3Q26 results were mixed. Revenue grew 3.5% yoy to Rmb309.6b, in line with our and consensus estimates. Non-GAAP operating profit rose to Rmb7.3b, above our estimate, supported by higher gross margin and lower losses from new initiatives. Non-GAAP net profit rose 43.7% yoy to Rmb8.3b, 2.9% below our estimate but ahead of consensus. Management guides for flat retail revenue yoy and double-digit group growth in 4Q26, aided by CECONOMY consolidation.
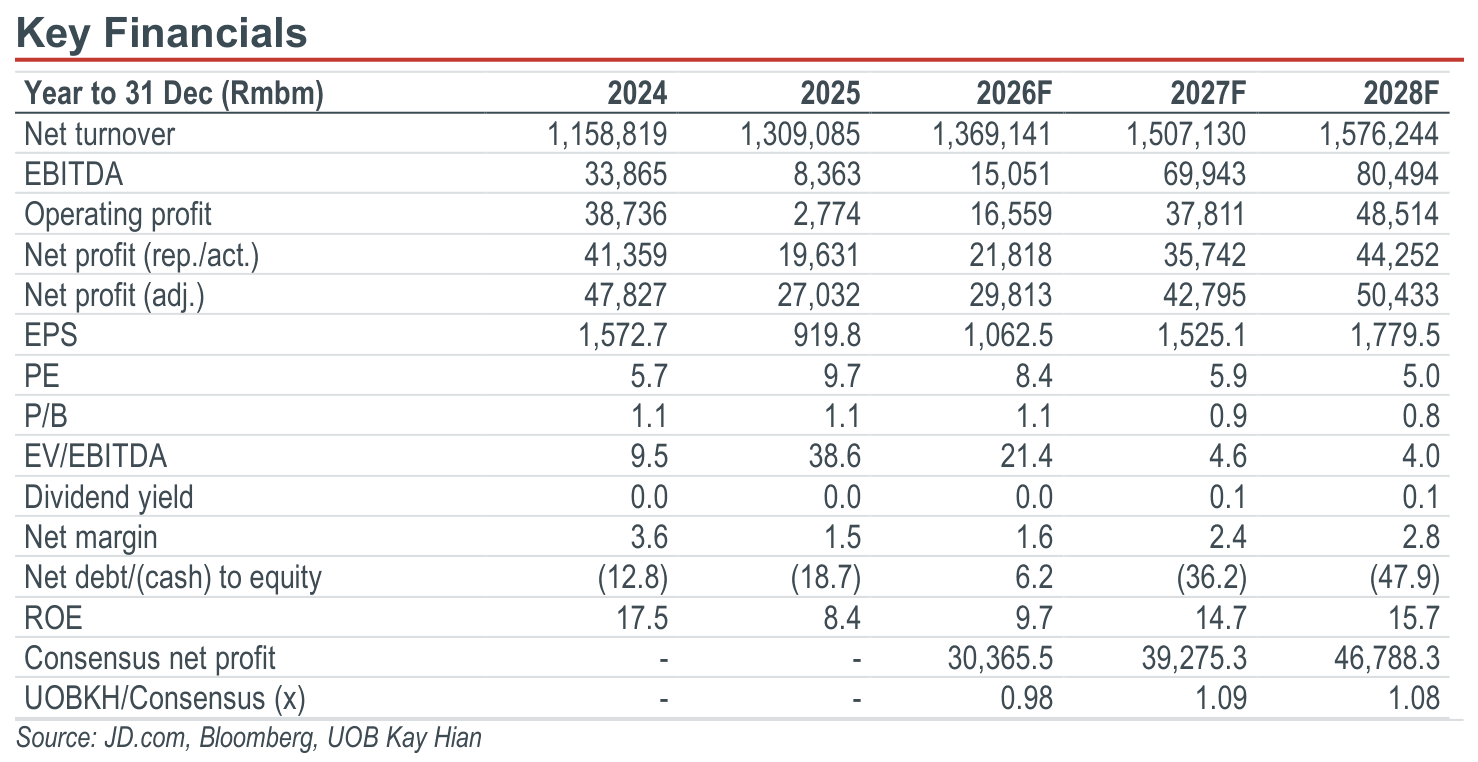
- Maintain BUY with a lower target price of HK$138.00 (US$35.00).
Analysis
- Revenue returned to growth, in line with our estimate. JD.com’s 3Q26 revenue grew 3.5% yoy to Rmb309.6b (2Q26: -2.9%), in line with our estimate. Electronics and home appliances revenue declined 0.7% yoy (2Q26: -12%) to Rmb127.7b as the high trade-in base eased, while general merchandise revenue grew 8.1% yoy (2Q26: +6%) to Rmb105.5b, led by supermarkets, healthcare and industrial products. Marketplace and marketing revenue rose 9.6% yoy (2Q26: +8%) to Rmb28.1b led by double-digit advertising growth, while logistics and other service revenue growth slowed to 2.1% yoy (2Q26: +6%). JD Retail revenue grew 2.9% yoy (2Q26: -5%) to Rmb258.0b, with operating margin edging down 0.1ppt yoy to 5.8%.
- Gross margin expanded, with marketing spending cut sharply. Gross margin expanded 1.2ppt yoy to 18.1% in 3Q26. Marketing expenses fell 26.2% yoy to Rmb15.5b due to more efficient promotional spending on new initiatives, while fulfilment expenses rose 7.4% yoy to Rmb23.6b and R&D rose 36.9% yoy to Rmb7.7b. Non-GAAP operating margin rose 2.3ppt yoy to 2.4%. JD Retail/JD Logistics/New Businesses operating margins came in at 5.8%/3.0%/-123.1%, vs 4.6%/3.5%/-135.7% in 2Q26. Non-GAAP net profit rose 43.7% yoy to Rmb8.3b, 2.9% below our estimate.
Highlights
- JD’s 3Q26 results were mixed. Revenue grew 3.5% yoy to Rmb309.6b, in line with our and consensus estimates. Non-GAAP operating profit rose to Rmb7.3b, above our estimate, supported by higher gross margin and lower losses from new initiatives. Non-GAAP net profit rose 43.7% yoy to Rmb8.3b, 2.9% below our estimate but ahead of consensus. Management guides for flat retail revenue yoy and double-digit group growth in 4Q26, aided by CECONOMY consolidation.
- Maintain BUY with a lower target price of HK$138.00 (US$35.00).
Analysis
- Revenue returned to growth, in line with our estimate. JD.com’s 3Q26 revenue grew 3.5% yoy to Rmb309.6b (2Q26: -2.9%), in line with our estimate. Electronics and home appliances revenue declined 0.7% yoy (2Q26: -12%) to Rmb127.7b as the high trade-in base eased, while general merchandise revenue grew 8.1% yoy (2Q26: +6%) to Rmb105.5b, led by supermarkets, healthcare and industrial products. Marketplace and marketing revenue rose 9.6% yoy (2Q26: +8%) to Rmb28.1b led by double-digit advertising growth, while logistics and other service revenue growth slowed to 2.1% yoy (2Q26: +6%). JD Retail revenue grew 2.9% yoy (2Q26: -5%) to Rmb258.0b, with operating margin edging down 0.1ppt yoy to 5.8%.
- Gross margin expanded, with marketing spending cut sharply. Gross margin expanded 1.2ppt yoy to 18.1% in 3Q26. Marketing expenses fell 26.2% yoy to Rmb15.5b due to more efficient promotional spending on new initiatives, while fulfilment expenses rose 7.4% yoy to Rmb23.6b and R&D rose 36.9% yoy to Rmb7.7b. Non-GAAP operating margin rose 2.3ppt yoy to 2.4%. JD Retail/JD Logistics/New Businesses operating margins came in at 5.8%/3.0%/-123.1%, vs 4.6%/3.5%/-135.7% in 2Q26. Non-GAAP net profit rose 43.7% yoy to Rmb8.3b, 2.9% below our estimate.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$105.20
HK$138.00
31.2%
HK$148.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

18 Nov 2026
Tencent Music Entertainment Group (1698 HK): 3Q26: Revenue Misses But Earnings Hold Up

17 Nov 2026
KE Holdings Inc (2423 HK): 3Q26: Strong Earnings Beat On Margin Expansion And Lower Opex

2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026
Our latest research

18 Nov 2026
Miniso (MNSO US/9896 HK): 3Q26: Results Better Than Expected; Reiterates 2026 Guidance; Optimistic About Domestic Market In 2027

18 Nov 2026
Sino Land (83 HK): Takeaways From Visit To One Marina Project
18 Nov 2026