

Company Coverage
Miniso (MNSO US/9896 HK): 3Q26: Results Better Than Expected; Reiterates 2026 Guidance; Optimistic About Domestic Market In 2027
BUY (Maintained)
Current price:
Target price:
Upside:
US$12.18
US$17.50
+43.7%
Analyst
Analyst
Highlights
- Miniso’s 3Q26 results were better than expected. Domestic revenue exceeded expectations, while overseas revenue was broadly in line, with performance continuing to be dragged by the distributor business. Operating margin contraction was also narrower than management’s previous expectation.
- Looking into 4Q26, management expects domestic SSSG to remain at least in the mid-single digits and is confident of exceeding the full-year low-single digit SSSG target. In its preliminary outlook for 2027, management remains optimistic about the domestic market and expects revenue growth of at least high single digits.
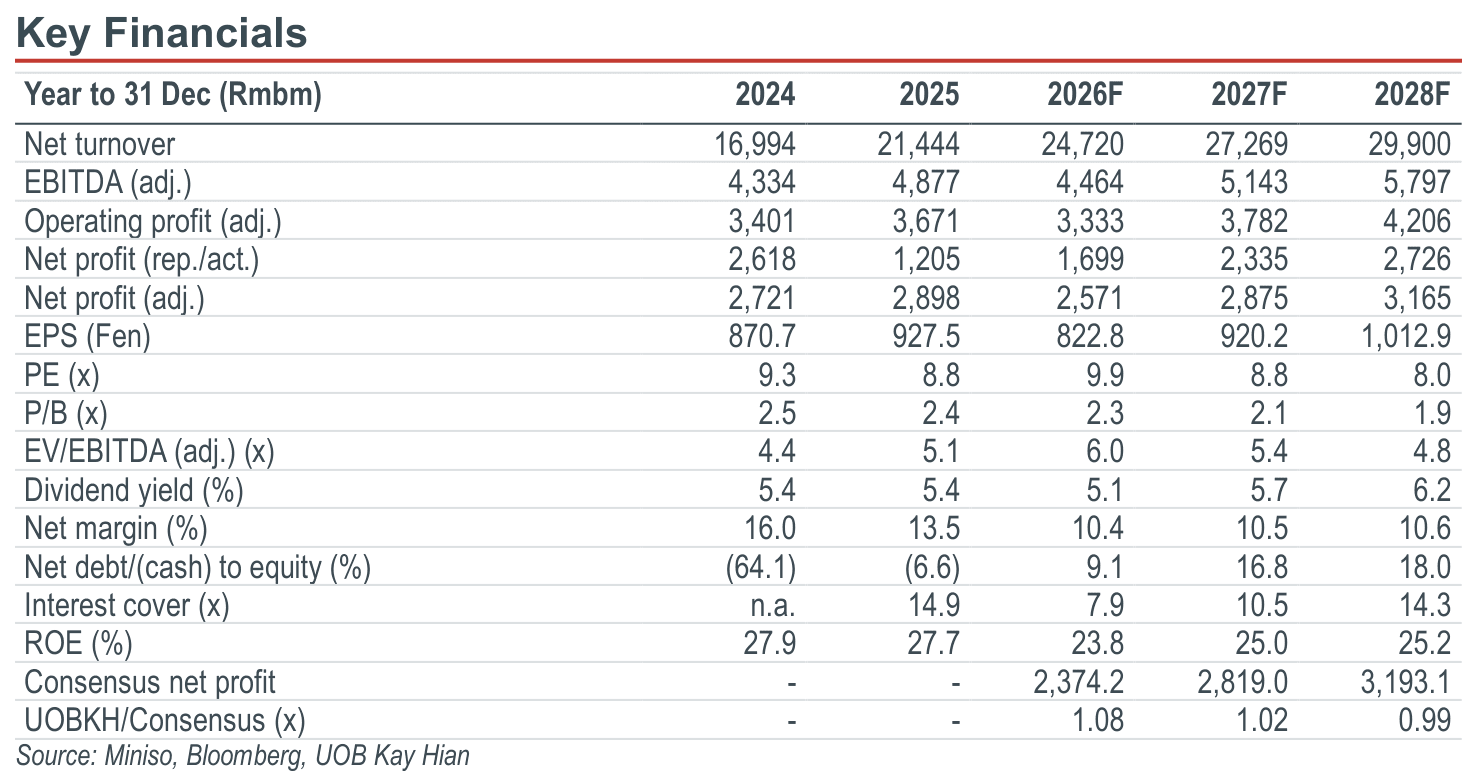
- For the overseas markets, the company will continue to streamline its network. Management believes the distributor business has the possibility to gradually stabilise as early as 1Q27. Management also reiterated its 2H26 and full-year guidance. While management has yet to provide specific guidance for 2027, it indicated that margins could improve from 2026 levels. Maintain BUY, with target price unchanged at US$17.50.
Analysis
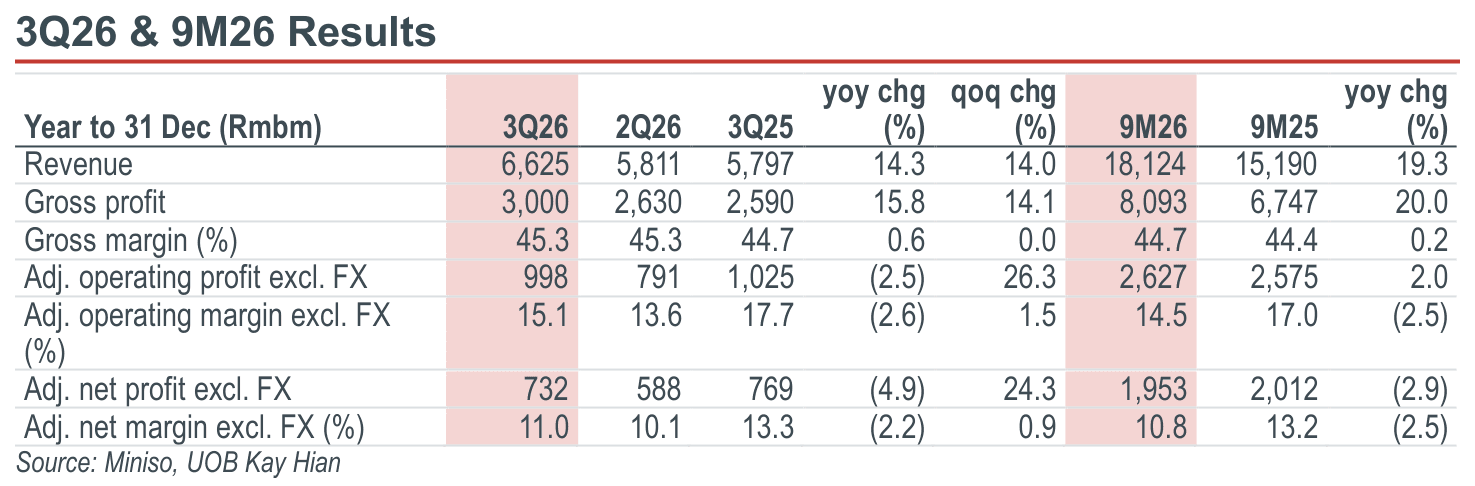
- 3Q26 results better than expected. Miniso reported 3Q26 revenue of Rmb6,625m (+14% yoy, +14% qoq), largely in line with management’s guidance for low-teens growth and 3% above VA consensus, primarily driven by the strong performance of the domestic market. Gross margin was 45.3% (+0.6ppt yoy, flat qoq), due to optimisation of its product mix as the company benefitted from optimised pricing strategies and higher sales contribution of proprietary and designer IPs. Adjusted operating profit excluding forex was Rmb998m (-3% yoy, +26% qoq), with an adjusted operating margin of 15.1% (-2.6ppt yoy, +1.5ppt qoq), better than management’s previous expectation of a 4-5ppt yoy decline. Adjusted net profit excluding forex was Rmb732m (-5% yoy, +24% qoq), with an adjusted net margin of 11.0% (-2.2ppt yoy, +0.9ppt qoq).
Highlights
- Miniso’s 3Q26 results were better than expected. Domestic revenue exceeded expectations, while overseas revenue was broadly in line, with performance continuing to be dragged by the distributor business. Operating margin contraction was also narrower than management’s previous expectation.
- Looking into 4Q26, management expects domestic SSSG to remain at least in the mid-single digits and is confident of exceeding the full-year low-single digit SSSG target. In its preliminary outlook for 2027, management remains optimistic about the domestic market and expects revenue growth of at least high single digits.
- For the overseas markets, the company will continue to streamline its network. Management believes the distributor business has the possibility to gradually stabilise as early as 1Q27. Management also reiterated its 2H26 and full-year guidance. While management has yet to provide specific guidance for 2027, it indicated that margins could improve from 2026 levels. Maintain BUY, with target price unchanged at US$17.50.
Analysis
- 3Q26 results better than expected. Miniso reported 3Q26 revenue of Rmb6,625m (+14% yoy, +14% qoq), largely in line with management’s guidance for low-teens growth and 3% above VA consensus, primarily driven by the strong performance of the domestic market. Gross margin was 45.3% (+0.6ppt yoy, flat qoq), due to optimisation of its product mix as the company benefitted from optimised pricing strategies and higher sales contribution of proprietary and designer IPs. Adjusted operating profit excluding forex was Rmb998m (-3% yoy, +26% qoq), with an adjusted operating margin of 15.1% (-2.6ppt yoy, +1.5ppt qoq), better than management’s previous expectation of a 4-5ppt yoy decline. Adjusted net profit excluding forex was Rmb732m (-5% yoy, +24% qoq), with an adjusted net margin of 11.0% (-2.2ppt yoy, +0.9ppt qoq).
BUY (Maintained)
Current price:
Target price:
Upside:
US$12.18
US$17.50
+43.7%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

27 Oct 2026
ZTE Corporation (763 HK): 3Q26: Operating Profit Dragged Down By Weak Margins And High Operating Expenses

30 Oct 2026
Midea Group (000333 CH): 3Q26: EBIT Declines 3%; Targets Positive Sales Growth For 4Q26

30 Oct 2026
Haier Smart Home (6690 HK): 3Q26: Net Profit Declines 12% yoy; Targets A Return To Domestic Revenue Growth For 4Q26
Our latest research

18 Nov 2026
JD.com (9618 HK): 3Q26: Operating Beat On Margin Expansion And FD Loss Reduction; Retail Returns To Growth

18 Nov 2026
Sino Land (83 HK): Takeaways From Visit To One Marina Project

18 Nov 2026