

Company Coverage
Tencent Holdings (700 HK): 3Q26: Higher AI Costs Result In Operating Profit Miss and Weigh on FCF
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$372.80
HK$500.00
34.1%
HK$537.00
Analyst
Analyst
Highlights
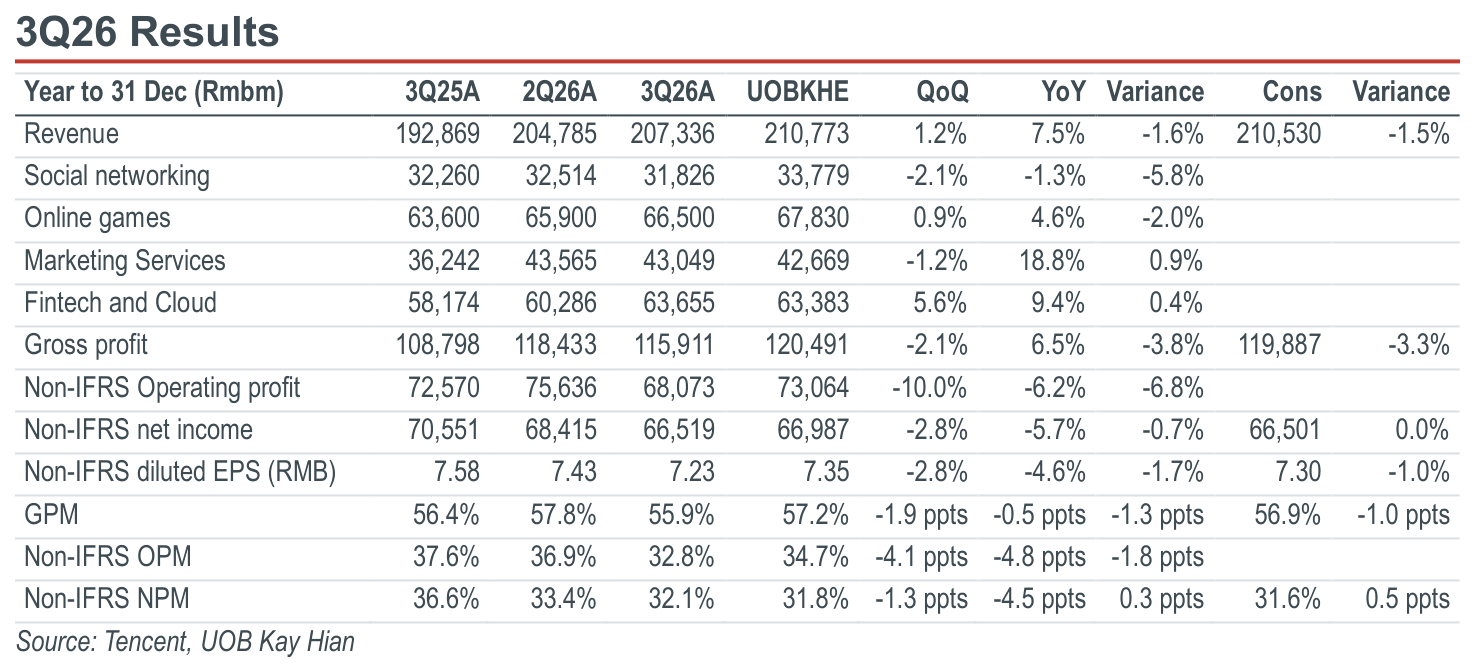
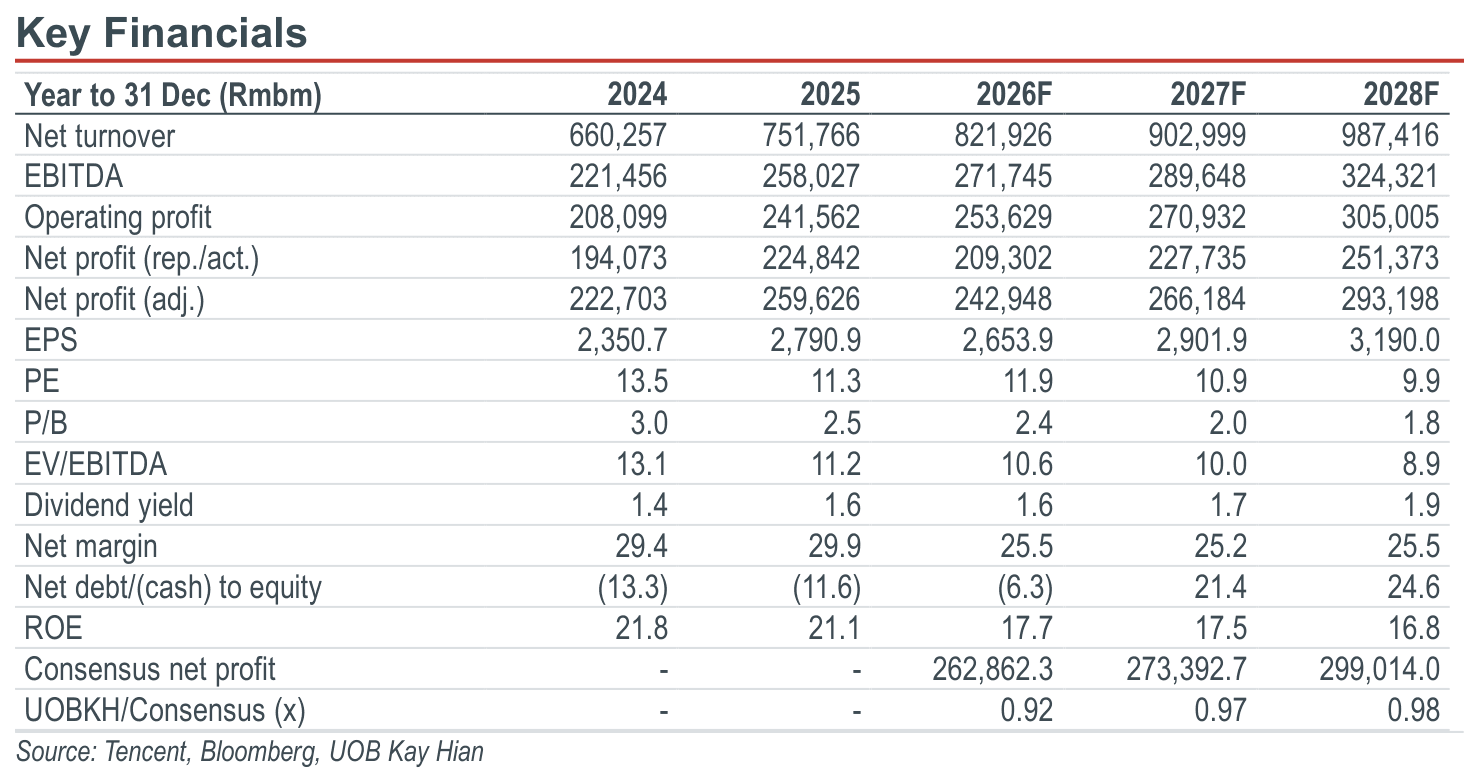
- Tencent’s 3Q26 results came in slightly below expectations. Revenue rose 7.5% yoy to Rmb207.3b, 1.6% below both our estimate and consensus. Higher AI-related costs weighed on profitability, with gross profit missing both estimates and non-IFRS operating profit coming in 6.8% below our estimate. Non-IFRS net profit fell 5.7% yoy to Rmb66.5b, broadly in line with expectations. Higher capex and compute prepayments widened the free cash outflow, with Tencent shifting to net debt.
- Maintain BUY with a lower target price of HK$500.00.
Analysis
- International weakness weighed on gaming growth. Online games revenue grew 4.6% yoy to Rmb66.5b, 2% below our estimate as international weakness partly offset solid domestic growth. Domestic games revenue rose 11% yoy to Rmb47.6b, led by evergreen titles including Honour of Kings, Delta Force and VALORANT MOBILE. International games revenue fell 9% yoy to Rmb18.9b, or 4% in constant currency, against a high base in 3Q25. Tencent expects a more normal cadence of premium game releases in 2027.
- Advertising growth remained strong as margins narrowed. Marketing services revenue rose 18.8% yoy to Rmb43.0b, broadly in line with our estimate. Growth was supported by improved AI-driven ad recommendations and wider use of Weixin’s closed-loop marketing tools. Segment gross margin fell to 52% from 57% in 3Q25, reflecting higher AI-related operating costs and Mini Dramas content costs.
Highlights
- Tencent’s 3Q26 results came in slightly below expectations. Revenue rose 7.5% yoy to Rmb207.3b, 1.6% below both our estimate and consensus. Higher AI-related costs weighed on profitability, with gross profit missing both estimates and non-IFRS operating profit coming in 6.8% below our estimate. Non-IFRS net profit fell 5.7% yoy to Rmb66.5b, broadly in line with expectations. Higher capex and compute prepayments widened the free cash outflow, with Tencent shifting to net debt.
- Maintain BUY with a lower target price of HK$500.00.
Analysis
- International weakness weighed on gaming growth. Online games revenue grew 4.6% yoy to Rmb66.5b, 2% below our estimate as international weakness partly offset solid domestic growth. Domestic games revenue rose 11% yoy to Rmb47.6b, led by evergreen titles including Honour of Kings, Delta Force and VALORANT MOBILE. International games revenue fell 9% yoy to Rmb18.9b, or 4% in constant currency, against a high base in 3Q25. Tencent expects a more normal cadence of premium game releases in 2027.
- Advertising growth remained strong as margins narrowed. Marketing services revenue rose 18.8% yoy to Rmb43.0b, broadly in line with our estimate. Growth was supported by improved AI-driven ad recommendations and wider use of Weixin’s closed-loop marketing tools. Segment gross margin fell to 52% from 57% in 3Q25, reflecting higher AI-related operating costs and Mini Dramas content costs.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$372.80
HK$500.00
34.1%
HK$537.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


