

Company Coverage
Baidu Inc (9888 HK): 3Q26: Earnings Beat; AI Cloud Growth Cushions Ad Weakness
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$75.25
HK$100.00
32.9%
HK$136.00
Analyst
Highlights
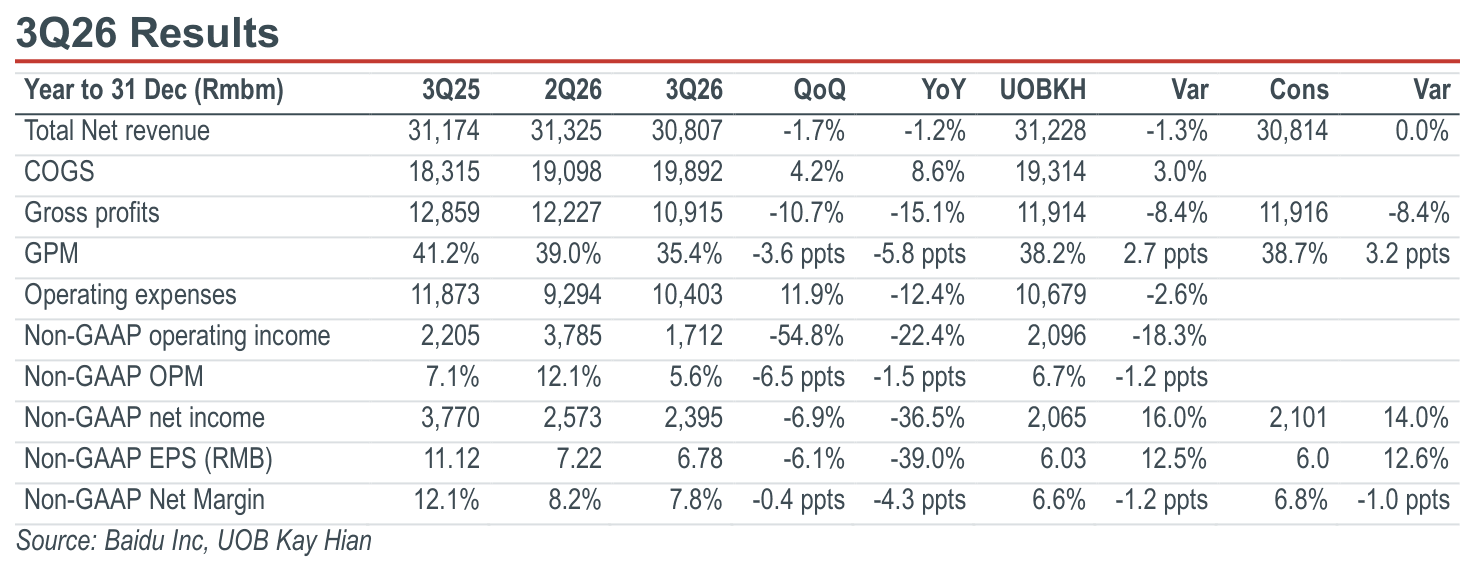
- 3Q26 earnings beat on below-the-line items. Revenue fell 1.2% yoy, broadly in line, as a 94% growth in AI cloud infra cushioned a 22% decline in online marketing. Non-GAAP operating margin missed by 1.2ppt, while net profit beat by 16.0% on other income and a lower minority-interest charge. Qianfan MaaS revenue from external token usage rose more than tenfold yoy, while higher capex widened the free cash outflow to Rmb4.6b.
- Maintain BUY with a slightly lower target price of HK$100.00 (US$103.00).
Analysis
- 3Q26 AI infra revenue beat. Baidu Inc’s (Baidu) revenue fell 1.2% yoy to Rmb30.8b in 3Q26, narrowing from a 4.2% yoy decline in 2Q26. Baidu Core AI-powered revenue grew 37% yoy to Rmb13.2b, accounting for 53% of Baidu General Business revenue, up from 50% in 2Q26. AI cloud infra revenue surged 94% yoy to Rmb8.2b, with GPU cloud revenue up 191% yoy, while AI applications revenue was flat yoy at Rmb2.6b. AI cloud infra profit and margin improved both yoy and qoq, while longer contracts and more prepayments shortened compute payback periods.
- Qianfan MaaS monetisation gained traction. Revenue from external customers’ token usage rose more than tenfold yoy in 3Q26, while AI applications revenue was broadly flat yoy. Yijing’s digital human production costs fell around 80% from 4Q25.
- Broad-based advertising remains weak Total online marketing revenue fell 22% yoy to Rmb11.9b. AI-native marketing revenue declined 15% yoy to Rmb2.4b after being flat yoy in 2Q26, reflecting a challenging macro environment, evolving competition and Baidu’s decision to prioritise user experience over near-term monetisation during its AI search transition.
- Apollo Go scaled up in key markets. Fully driverless rides in Shenzhen rose around 170% qoq in 3Q26, while its Dubai fleet doubled. Apollo Go continued to carry out tests in London and Hong Kong, with its global footprint reaching 30 cities as of Oct 26.
Highlights
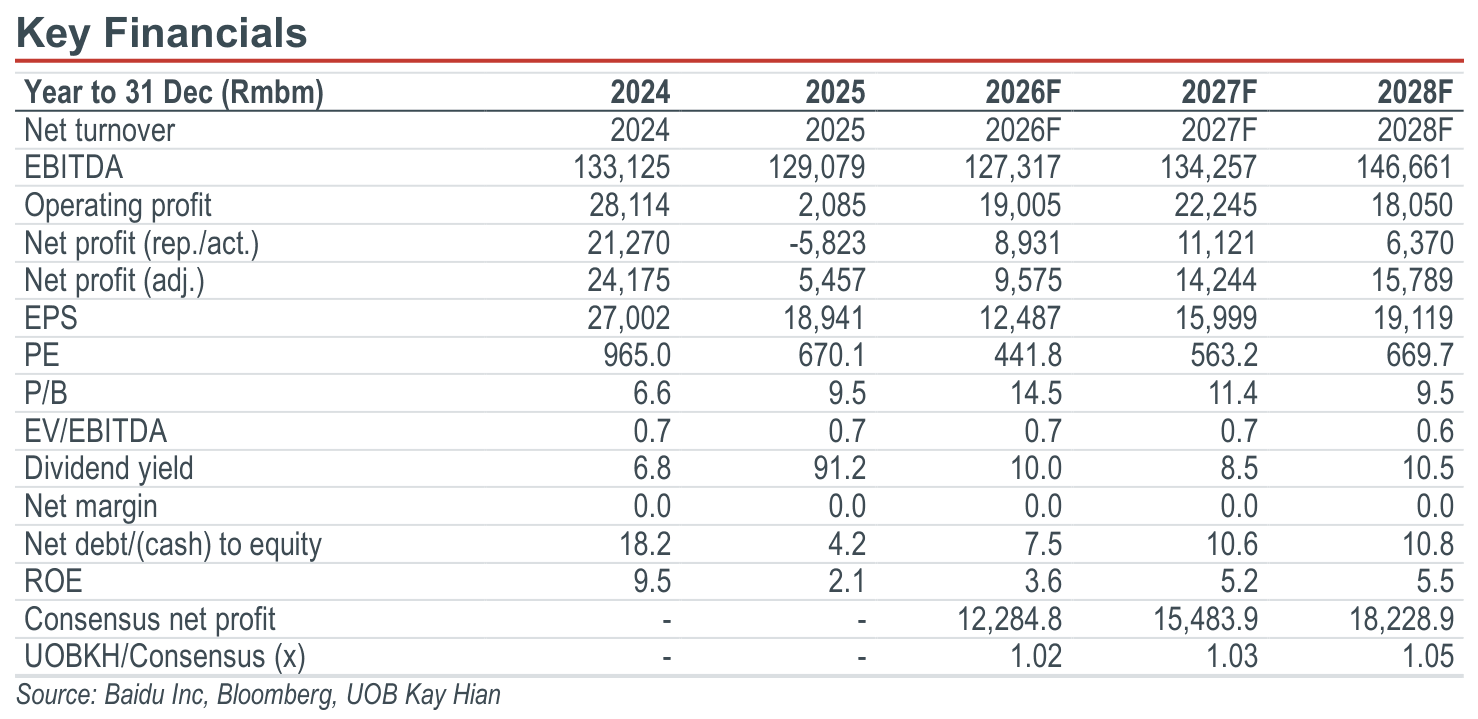
- 3Q26 earnings beat on below-the-line items. Revenue fell 1.2% yoy, broadly in line, as a 94% growth in AI cloud infra cushioned a 22% decline in online marketing. Non-GAAP operating margin missed by 1.2ppt, while net profit beat by 16.0% on other income and a lower minority-interest charge. Qianfan MaaS revenue from external token usage rose more than tenfold yoy, while higher capex widened the free cash outflow to Rmb4.6b.
- Maintain BUY with a slightly lower target price of HK$100.00 (US$103.00).
Analysis
- 3Q26 AI infra revenue beat. Baidu Inc’s (Baidu) revenue fell 1.2% yoy to Rmb30.8b in 3Q26, narrowing from a 4.2% yoy decline in 2Q26. Baidu Core AI-powered revenue grew 37% yoy to Rmb13.2b, accounting for 53% of Baidu General Business revenue, up from 50% in 2Q26. AI cloud infra revenue surged 94% yoy to Rmb8.2b, with GPU cloud revenue up 191% yoy, while AI applications revenue was flat yoy at Rmb2.6b. AI cloud infra profit and margin improved both yoy and qoq, while longer contracts and more prepayments shortened compute payback periods.
- Qianfan MaaS monetisation gained traction. Revenue from external customers’ token usage rose more than tenfold yoy in 3Q26, while AI applications revenue was broadly flat yoy. Yijing’s digital human production costs fell around 80% from 4Q25.
- Broad-based advertising remains weak Total online marketing revenue fell 22% yoy to Rmb11.9b. AI-native marketing revenue declined 15% yoy to Rmb2.4b after being flat yoy in 2Q26, reflecting a challenging macro environment, evolving competition and Baidu’s decision to prioritise user experience over near-term monetisation during its AI search transition.
- Apollo Go scaled up in key markets. Fully driverless rides in Shenzhen rose around 170% qoq in 3Q26, while its Dubai fleet doubled. Apollo Go continued to carry out tests in London and Hong Kong, with its global footprint reaching 30 cities as of Oct 26.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$75.25
HK$100.00
32.9%
HK$136.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

6 Nov 2026
ECARX Holdings Inc (ECX US) - 3Q26: Memory Costs Cut Gross Margin To 7.0%

29 Oct 2026
Tsingtao Brewery (168 HK): 3Q26: Net Profit Down 17%; Sales Volume Down 9%; ASP Up 4%

2 Nov 2026
Kweichow Moutai (600519 CH) - 3Q26: Results In Line; Direct Sales Up 40% On i-Moutai Growth
Our latest research

17 Nov 2026
New World Development (17 HK): Rights Issue Strenghtens Balance Sheet but Dilutes NAV per Share by 90%

16 Nov 2026
ChangXin Memory Technologies (688825 CH): China’s Rising DRAM Champion Amid The Memory Supercycle
13 Nov 2026