

Company Coverage
ChangXin Memory Technologies (688825 CH): China’s Rising DRAM Champion Amid The Memory Supercycle
BUY
Current price:
Target price:
Upside:
Previous TP :
Rmb39.98
Rmb59.40
48.5%
n.a.
Analyst
Analyst
Highlights
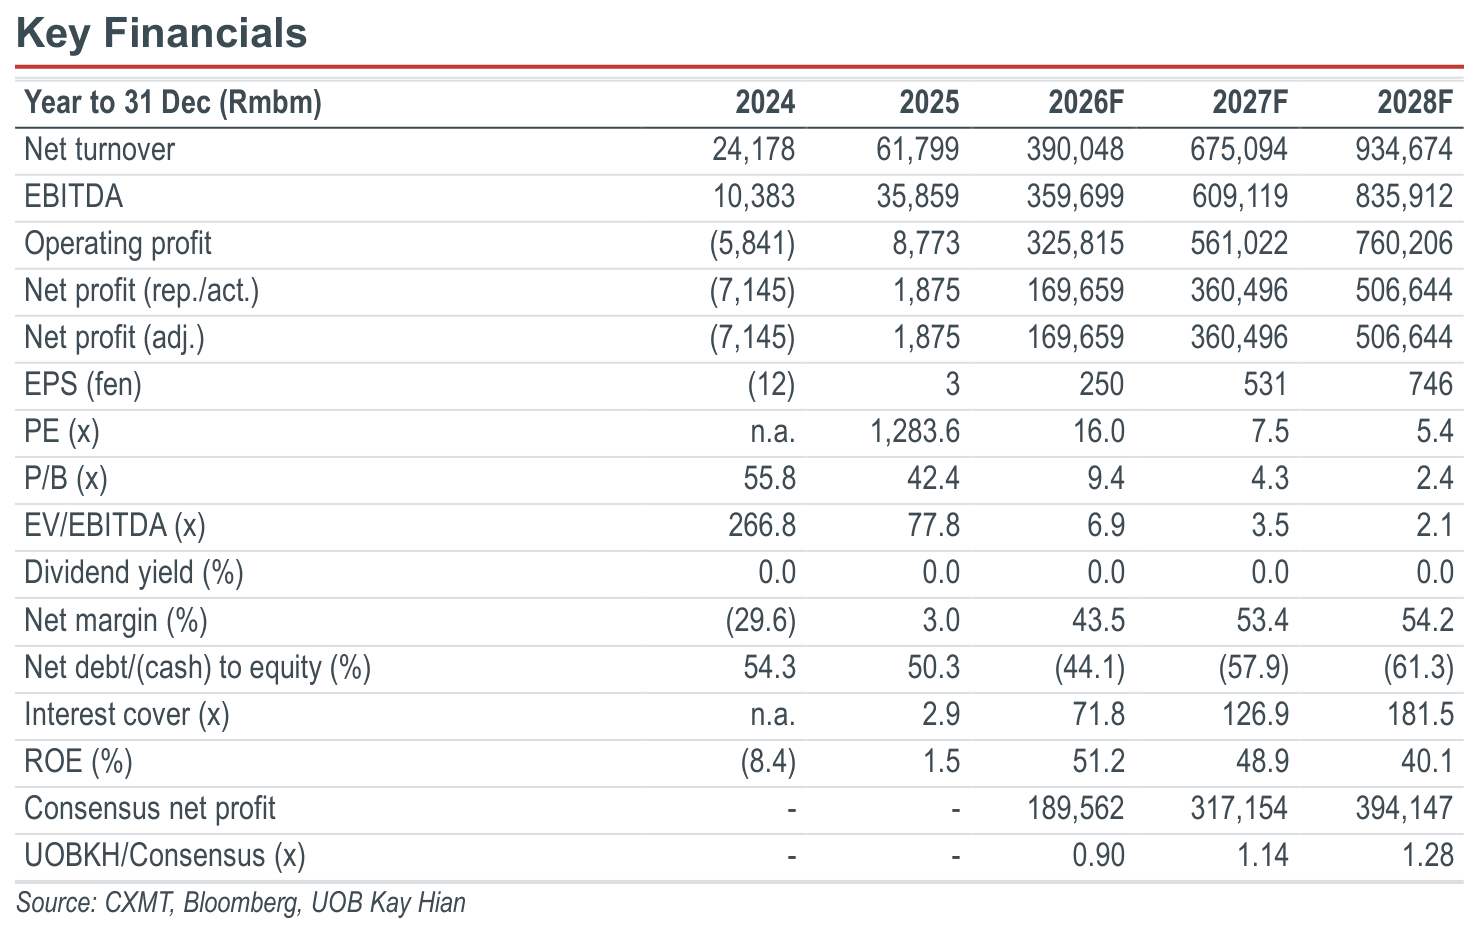
- As China’s largest DRAM maker, CXMT is well positioned to benefit from vast import substitution opportunities and a sustained peak DRAM cycle.
- We expect CXMT to achieve solid progress in HBM, with rapid capacity ramp-up and yield improvements boosting production in 2026-28. The extreme scarcity of HBM in China will help alleviate margin pressure from yield loss.
- Initiate coverage with BUY and a target price of Rmb59.40.
Analysis
- Largest DRAM maker in China riding on DRAM supercycle. CXMT is China’s leading DRAM IDM and ranks fourth in the world by bit volume. We estimate CXMT’s share of global DRAM bit shipments could grow from 8.5% in 2025 to 10.7% in 2028, driven by rapid capacity additions and improving yields. The strong underlying demand for DRAM is primarily underpinned by a broad surge in AI-related demand, as well as import substitution in the face of the US’ tightening export restrictions on HBM. Apart from its strong position among domestic consumer electronics players, the company has secured orders from Chinese cloud service providers (CSP) for server-grade DDR5, and has broken into the supply chains of overseas brands including Apple, HP and Asus, thanks to their supply-source diversification incentives.
- DRAM shortage likely to last through 2028… Our global DRAM supply-demand forecast shows a sustained shortage in 2026-28, with the shortfall widening from a low single-digit percentage of supply in 2026 to a low-teens percentage in 2027-28. AI infrastructure is the primary driver, as demand from servers and GPUs lifts AI infrastructure’s share of bit consumption to 60.0% in 2028, up 11.3ppt from that in 2025. On the other hand, while we expect AI adoption at the edge to lift DRAM consumption in PCs and smartphones, we remain cautious on their shipment numbers and are conservative on their content gains, as we expect most DRAM resources to go to higher-productivity products such as AI servers and GPUs. As a result, the share of DRAM bits consumed by PCs and smartphones could fall to 4.5%/30.3% in 2028 respectively, down 4.8ppt/5.7ppt from 2025.
- Click here for Full Report dated 13 Nov 26
Highlights
- As China’s largest DRAM maker, CXMT is well positioned to benefit from vast import substitution opportunities and a sustained peak DRAM cycle.
- We expect CXMT to achieve solid progress in HBM, with rapid capacity ramp-up and yield improvements boosting production in 2026-28. The extreme scarcity of HBM in China will help alleviate margin pressure from yield loss.
- Initiate coverage with BUY and a target price of Rmb59.40.
Analysis
- Largest DRAM maker in China riding on DRAM supercycle. CXMT is China’s leading DRAM IDM and ranks fourth in the world by bit volume. We estimate CXMT’s share of global DRAM bit shipments could grow from 8.5% in 2025 to 10.7% in 2028, driven by rapid capacity additions and improving yields. The strong underlying demand for DRAM is primarily underpinned by a broad surge in AI-related demand, as well as import substitution in the face of the US’ tightening export restrictions on HBM. Apart from its strong position among domestic consumer electronics players, the company has secured orders from Chinese cloud service providers (CSP) for server-grade DDR5, and has broken into the supply chains of overseas brands including Apple, HP and Asus, thanks to their supply-source diversification incentives.
- DRAM shortage likely to last through 2028… Our global DRAM supply-demand forecast shows a sustained shortage in 2026-28, with the shortfall widening from a low single-digit percentage of supply in 2026 to a low-teens percentage in 2027-28. AI infrastructure is the primary driver, as demand from servers and GPUs lifts AI infrastructure’s share of bit consumption to 60.0% in 2028, up 11.3ppt from that in 2025. On the other hand, while we expect AI adoption at the edge to lift DRAM consumption in PCs and smartphones, we remain cautious on their shipment numbers and are conservative on their content gains, as we expect most DRAM resources to go to higher-productivity products such as AI servers and GPUs. As a result, the share of DRAM bits consumed by PCs and smartphones could fall to 4.5%/30.3% in 2028 respectively, down 4.8ppt/5.7ppt from 2025.
- Click here for Full Report dated 13 Nov 26
BUY
Current price:
Target price:
Upside:
Previous TP :
Rmb39.98
Rmb59.40
48.5%
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
Shuanghuan Driveline (002472 CH): 3Q26: Earnings In Line, Emerging Segments To Grow

21 Oct 2026
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow

29 Oct 2026
Tencent Holdings (700 HK): 3Q26 Preview: Clear AI Strategy; Investment Pressure On Margins
Our latest research
13 Nov 2026
TA: Link Real Estate Investment Trust (0823 HK) / Sino Biopharmaceutical (1177 HK)

13 Nov 2026
LINK REIT (823 HK): 1HFY27: DPU Slightly Ahead; Solid Strategy Execution To Sharpen Focus On Retail In Asia Pacific

13 Nov 2026