

Company Coverage
Shuanghuan Driveline (002472 CH): 3Q26: Earnings In Line, Emerging Segments To Grow
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb41.41
Rmb52.00
+25.6%
Rmb50.00
Analyst
Analyst
Highlights
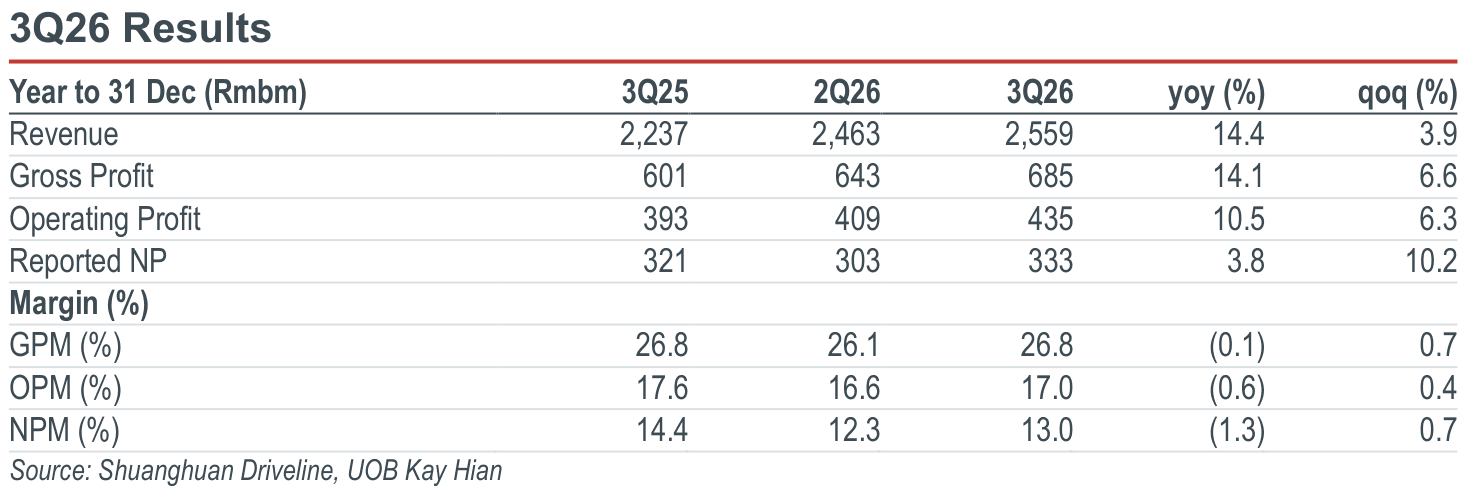
- Shuanghuan’s 3Q26 results were broadly in line. Revenue grew 14% yoy and gross margin recovered 0.7ppt qoq to 26.8%; net profit was slightly below expectations, growing 3.8% yoy to Rmb333m due to a higher opex.
- Overseas order growth is accelerating, with mounting orders momentum from leading global OEMS. The penetration of coaxial reducers is also expected to accelerate at over 1-2x yoy growth in 2027 from a low base.
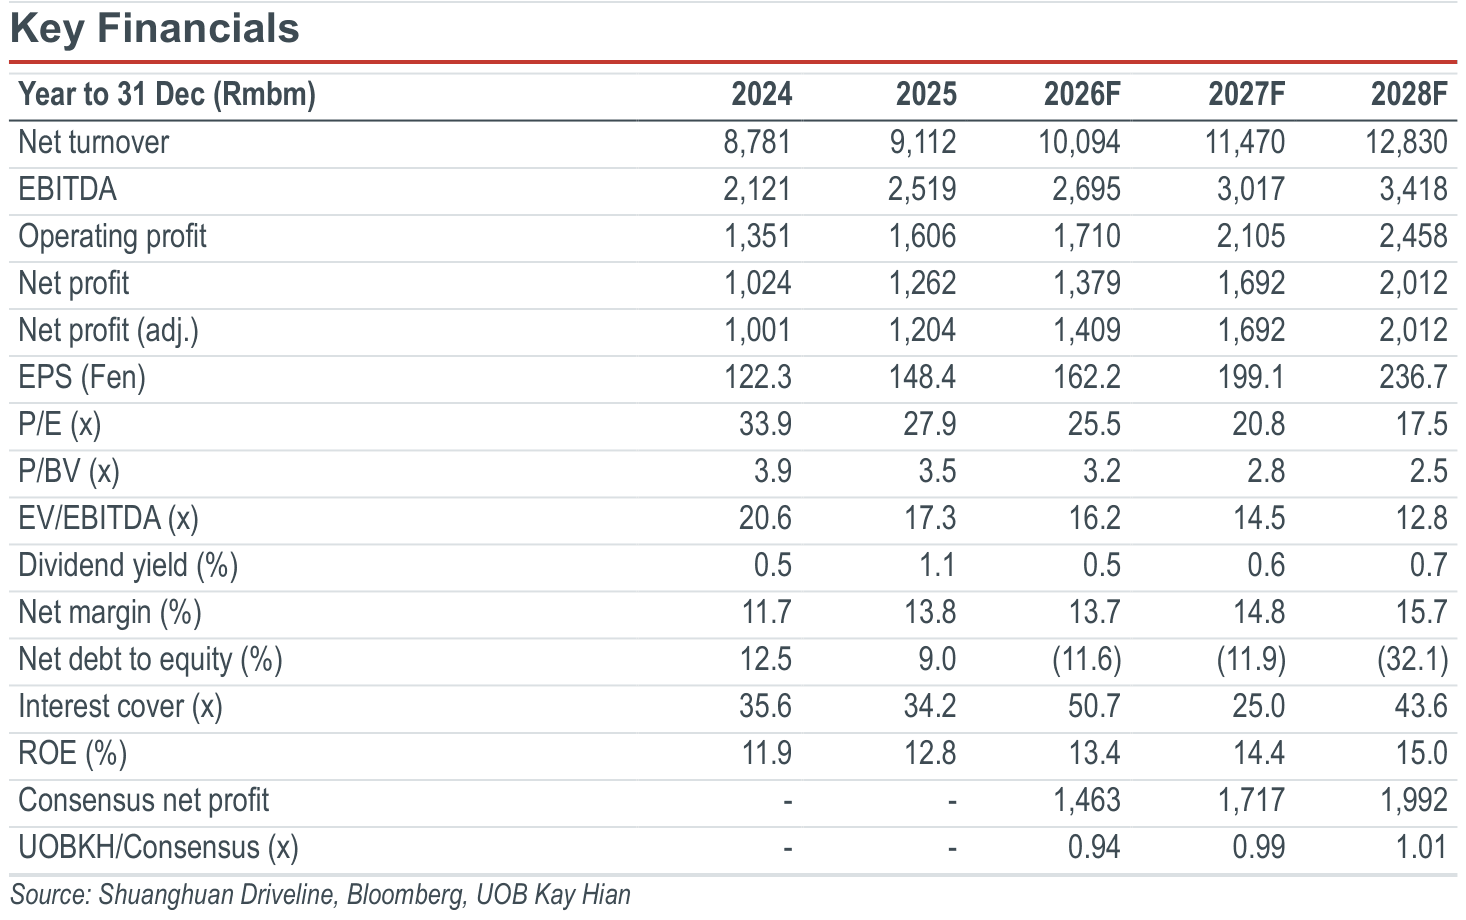
- Maintain BUY and raise target price slightly to Rmb52.00.
Analysis
- Revenue in line, higher operating expenses dragged earnings. Shuanghuan Driveline’s 3Q26 revenue was up 14.4% yoy and 3.9% qoq to Rmb2,559m, largely in line; gross margin was also in line, down 0.1ppt yoy and expanding 0.7ppt qoq to 26.8%. Operating profit was slightly below expectations, growing 10.5% yoy and 6.3% qoq to Rmb435m due to higher opex, and as a result reported net profit was a slight miss at Rmb333m, growing 3.8% yoy and 10.2% qoq.
- NEV gears, intelligent actuators and robotics continued to drive revenue growth. New energy vehicle (NEV) gears grew 26% yoy in 3Q26, intelligent actuators rose 31% yoy, robotics (industrial RV + harmonic) expanded around 20% yoy in 3Q26, and construction machinery gears grew 10% yoy in 3Q26. ICE-car gears continue to drag the overall growth, with revenue declining 14% yoy in 3Q26, and commercial vehicle gears also seeing a slowdown in momentum with revenue declining about 7% yoy during the quarter.
Highlights
- Shuanghuan’s 3Q26 results were broadly in line. Revenue grew 14% yoy and gross margin recovered 0.7ppt qoq to 26.8%; net profit was slightly below expectations, growing 3.8% yoy to Rmb333m due to a higher opex.
- Overseas order growth is accelerating, with mounting orders momentum from leading global OEMS. The penetration of coaxial reducers is also expected to accelerate at over 1-2x yoy growth in 2027 from a low base.
- Maintain BUY and raise target price slightly to Rmb52.00.
Analysis
- Revenue in line, higher operating expenses dragged earnings. Shuanghuan Driveline’s 3Q26 revenue was up 14.4% yoy and 3.9% qoq to Rmb2,559m, largely in line; gross margin was also in line, down 0.1ppt yoy and expanding 0.7ppt qoq to 26.8%. Operating profit was slightly below expectations, growing 10.5% yoy and 6.3% qoq to Rmb435m due to higher opex, and as a result reported net profit was a slight miss at Rmb333m, growing 3.8% yoy and 10.2% qoq.
- NEV gears, intelligent actuators and robotics continued to drive revenue growth. New energy vehicle (NEV) gears grew 26% yoy in 3Q26, intelligent actuators rose 31% yoy, robotics (industrial RV + harmonic) expanded around 20% yoy in 3Q26, and construction machinery gears grew 10% yoy in 3Q26. ICE-car gears continue to drag the overall growth, with revenue declining 14% yoy in 3Q26, and commercial vehicle gears also seeing a slowdown in momentum with revenue declining about 7% yoy during the quarter.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb41.41
Rmb52.00
+25.6%
Rmb50.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


