

Company Coverage
Inovance Technology (300124 CH): 3Q26: Earnings Miss On Margin Squeeze; Outlook Hinges On Cost Pass-through
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb53.31
Rmb75.00
40.7%
Rmb95.00
Analyst
Analyst
Highlights
- Inovance’s 3Q26 reported net profit grew 23.6% yoy to Rmb1.6b, above consensus estimate. This is mainly driven by non-op items. Core profit was weaker than expected due to a surprise margin squeeze from cost hikes.
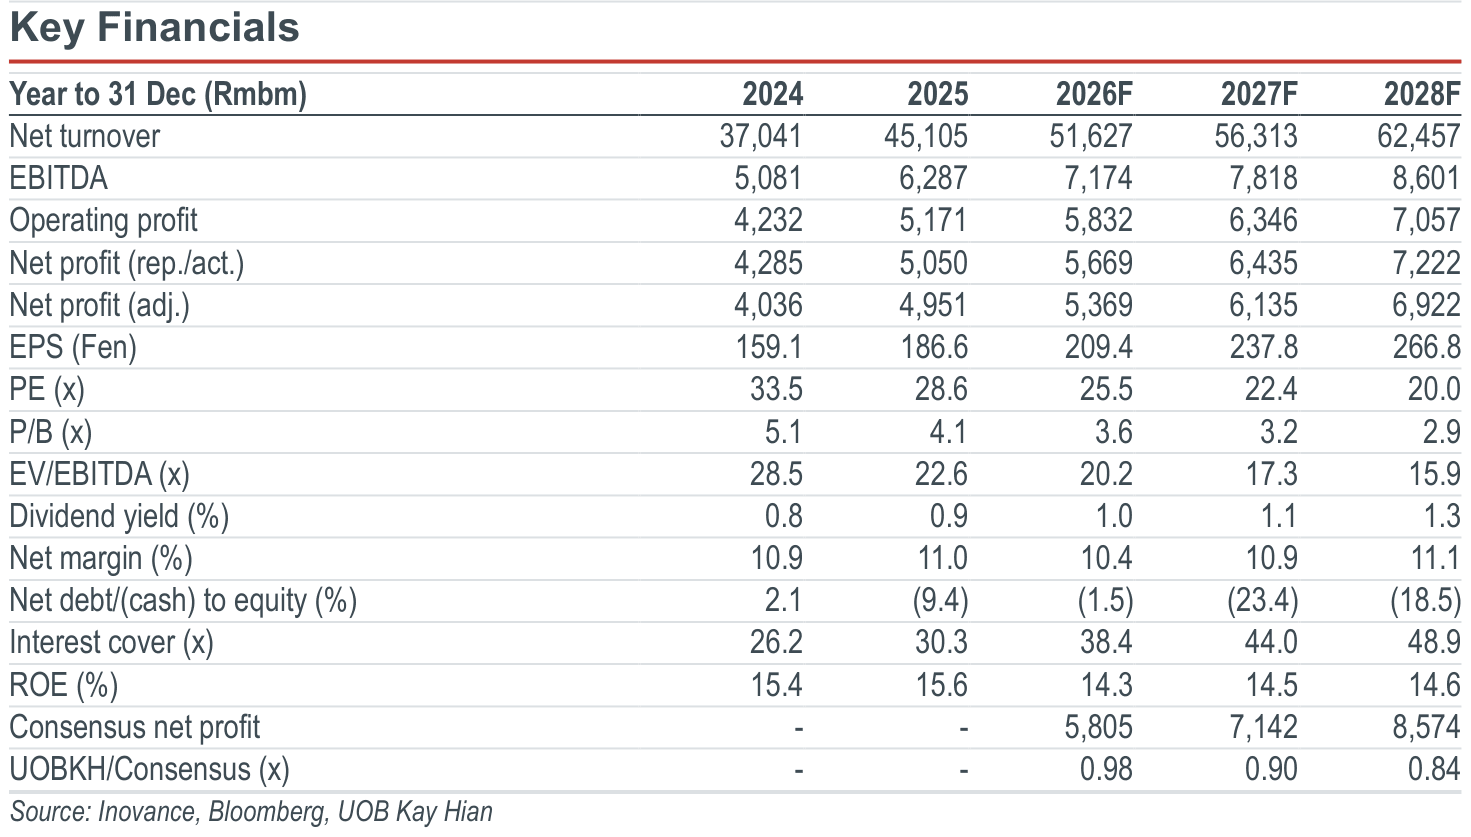
- Management expects sustained 20% yoy growth in the general automation business in 2027, while the NEV and elevator businesses should see relief in profitability thanks to cost pass-through. Physical AI will start to kick in as a primary growth driver going forward as well.
- Maintain BUY but cut target price to Rmb75.00.
Analysis
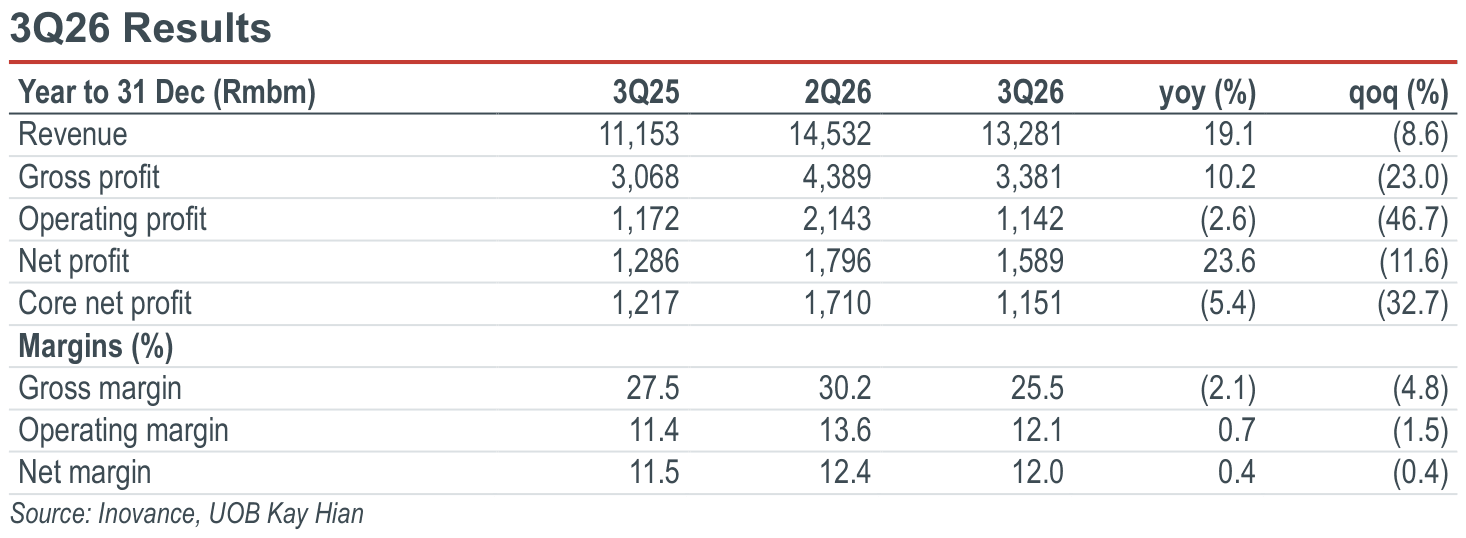
- Margin squeeze drove core profit miss. Revenue rose 19.1% yoy but fell 8.6% qoq to Rmb13,281m, in line with consensus. Gross margin contracted 2.1ppt yoy and 4.8ppt qoq to 25.5%, missing consensus by 3.6ppt. Reported net profit rose 23.6% yoy to Rmb1,589m, 4.0% above consensus, supported by Rmb419m in fair-value gains. Excluding these gains, core net profit dropped 5.4% yoy and 32.7% qoq to Rmb1,151m, 16.7% below consensus.
- Product mix and cost inflation weighed on margins. Industrial automation and digital contributed Rmb6.4b, or 48% of revenue, while new energy vehicles contributed Rmb6.1b, or 46%, and emerging businesses contributed Rmb630m, or 5%. Automotive gross margin fell materially due to a shift towards lower-margin products, while component-cost inflation and the lack of cost pass-through further pressured group margins.
Highlights
- Inovance’s 3Q26 reported net profit grew 23.6% yoy to Rmb1.6b, above consensus estimate. This is mainly driven by non-op items. Core profit was weaker than expected due to a surprise margin squeeze from cost hikes.
- Management expects sustained 20% yoy growth in the general automation business in 2027, while the NEV and elevator businesses should see relief in profitability thanks to cost pass-through. Physical AI will start to kick in as a primary growth driver going forward as well.
- Maintain BUY but cut target price to Rmb75.00.
Analysis
- Margin squeeze drove core profit miss. Revenue rose 19.1% yoy but fell 8.6% qoq to Rmb13,281m, in line with consensus. Gross margin contracted 2.1ppt yoy and 4.8ppt qoq to 25.5%, missing consensus by 3.6ppt. Reported net profit rose 23.6% yoy to Rmb1,589m, 4.0% above consensus, supported by Rmb419m in fair-value gains. Excluding these gains, core net profit dropped 5.4% yoy and 32.7% qoq to Rmb1,151m, 16.7% below consensus.
- Product mix and cost inflation weighed on margins. Industrial automation and digital contributed Rmb6.4b, or 48% of revenue, while new energy vehicles contributed Rmb6.1b, or 46%, and emerging businesses contributed Rmb630m, or 5%. Automotive gross margin fell materially due to a shift towards lower-margin products, while component-cost inflation and the lack of cost pass-through further pressured group margins.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb53.31
Rmb75.00
40.7%
Rmb95.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00

22 Oct 2026
Contemporary Amperex Technology Co (300750 CH): 3Q26: Earnings Miss Due To Delayed Pass-through Of Tax Hikes

28 Oct 2026
Shuanghuan Driveline (002472 CH): 3Q26: Earnings In Line, Emerging Segments To Grow
Our latest research
28 Oct 2026
TA: Swire Properties (1972 HK) / CK Hutchison (0001 HK)

28 Oct 2026
Huizhou Desay SV (002920 CH): 3Q26: Revenue Growth Accelerates To 24%, But Earnings Miss On Subsidy Cuts, Credit Provisions, Associates’ Losses, And Tax Hikes
28 Oct 2026