Company Coverage
Han’s Laser (002008 CH): 3Q26: Strong Beat In IT Business
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb60.54
Rmb106.90
+76.6%
Rmb153.20
Analyst
Analyst
Highlights
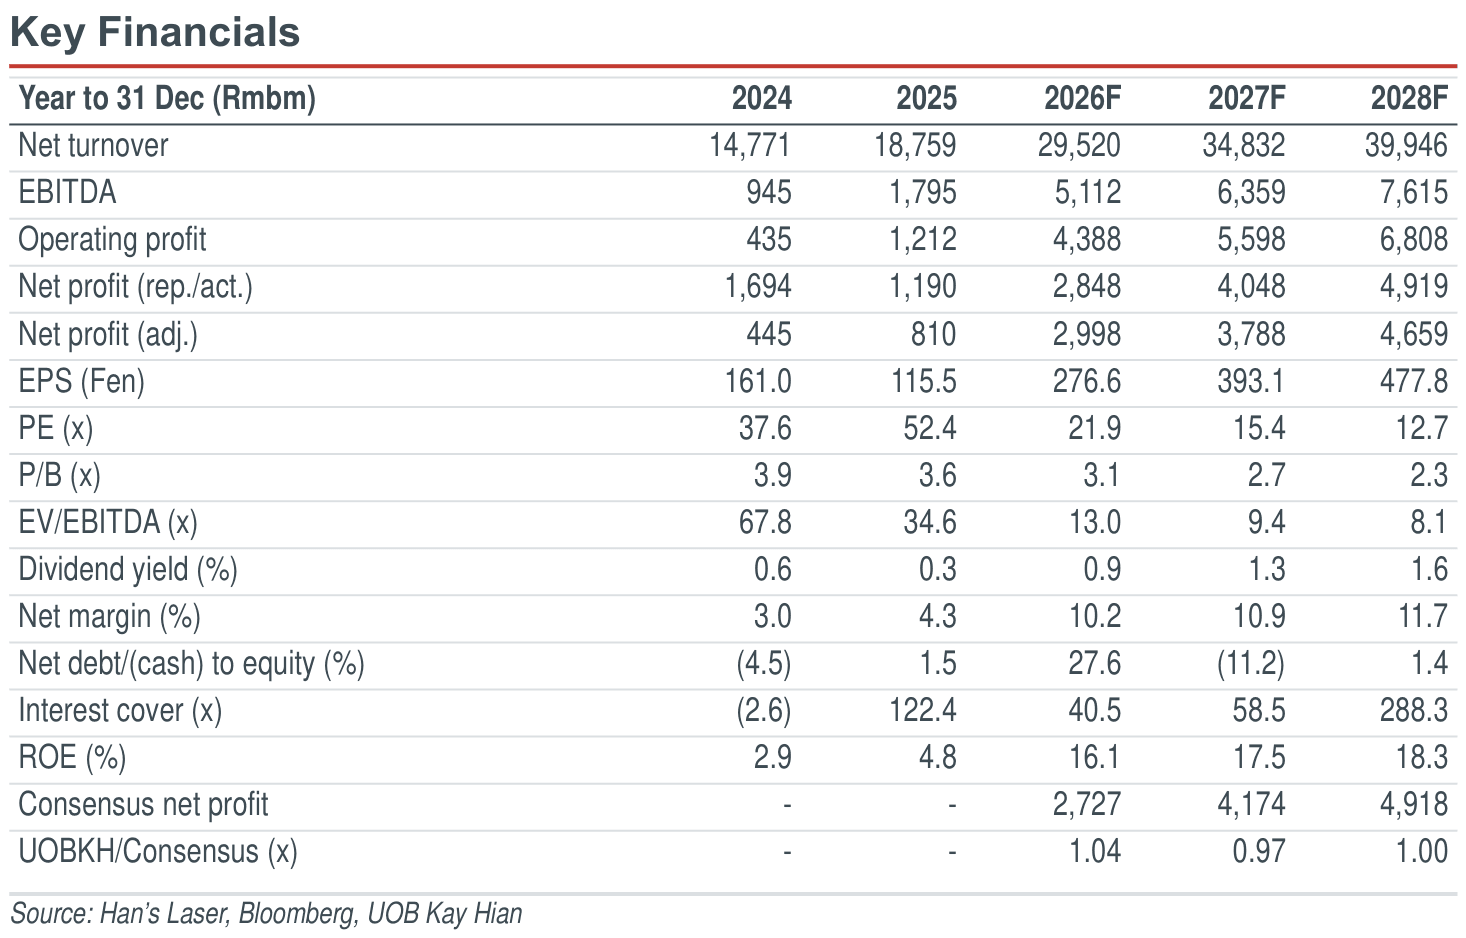
- Han’s Laser’s 3Q26 revenue grew 58% yoy to Rmb8b, and adjusted net profit surged 190% yoy to Rmb893m. These came in 5%/6% above consensus estimates respectively, driven by strong growth in the IT and PCB equipment businesses.
- AI-related orders remained strong, with the IT business expected to deliver a strong beat in 2026. Han’s had also achieved a major order win with 3DP from an IT client, which should start contribution from 4Q26 to 2027.
- Maintain BUY; trim target price to Rmb106.90 as we lower the target multiple.
Analysis
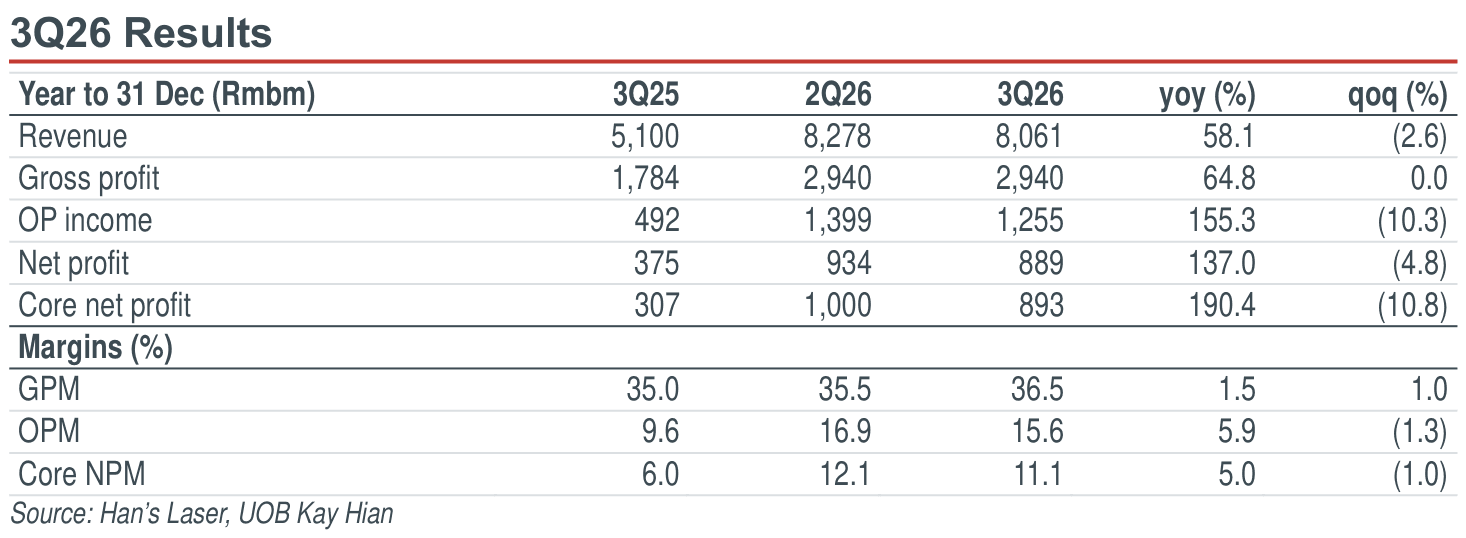
- Margin expansion drove earnings beat. Revenue rose 58.1% yoy but declined 2.6% qoq to Rmb8,061m, beating consensus by 4.5%. Gross margin expanded 1.5ppt yoy and 1.0ppt qoq to 36.5%, in line with consensus. Operating profit surged 155.3% yoy to Rmb1,255m, beating consensus by 16.5%. Adjusted net profit surged 190.4% yoy but moderated 10.8% qoq to Rmb893m following a strong 2Q26, beating consensus by 6.0%.
- Order intake nearly doubled. 9M26 new orders surged 90% yoy to Rmb24.3b, with Rmb5.3b added during August and September. The strong orders (and the strong growth) were primarily driven by the IT and PCB equipment businesses.
Highlights
- Han’s Laser’s 3Q26 revenue grew 58% yoy to Rmb8b, and adjusted net profit surged 190% yoy to Rmb893m. These came in 5%/6% above consensus estimates respectively, driven by strong growth in the IT and PCB equipment businesses.
- AI-related orders remained strong, with the IT business expected to deliver a strong beat in 2026. Han’s had also achieved a major order win with 3DP from an IT client, which should start contribution from 4Q26 to 2027.
- Maintain BUY; trim target price to Rmb106.90 as we lower the target multiple.
Analysis
- Margin expansion drove earnings beat. Revenue rose 58.1% yoy but declined 2.6% qoq to Rmb8,061m, beating consensus by 4.5%. Gross margin expanded 1.5ppt yoy and 1.0ppt qoq to 36.5%, in line with consensus. Operating profit surged 155.3% yoy to Rmb1,255m, beating consensus by 16.5%. Adjusted net profit surged 190.4% yoy but moderated 10.8% qoq to Rmb893m following a strong 2Q26, beating consensus by 6.0%.
- Order intake nearly doubled. 9M26 new orders surged 90% yoy to Rmb24.3b, with Rmb5.3b added during August and September. The strong orders (and the strong growth) were primarily driven by the IT and PCB equipment businesses.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rmb60.54
Rmb106.90
+76.6%
Rmb153.20
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Oct 2026
Lenovo Group (992 HK): 2QFY27 Results Preview: ISG To Register Another Quarter Of Strong Growth

23 Oct 2026

