
Company Coverage
LINK REIT (823 HK): 1HFY27: DPU Slightly Ahead; Solid Strategy Execution To Sharpen Focus On Retail In Asia Pacific
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$41.50
HK$45.70
+10.1%
HK$44.30
Analyst
Analyst
Highlights
- 1HFY27 DPU rose 0.3% yoy to 127.25 HK cents, accounting for 51% of our FY27 forecast and slightly ahead of our expectations.
- Hong Kong tenant sales was broadly stable (-0.2% yoy), while retail rental reversion was -7.5%. Management reiterated guidance for FY27 Hong Kong rental reversion and is planning HK$1b-2b of buybacks in 2HFY27.
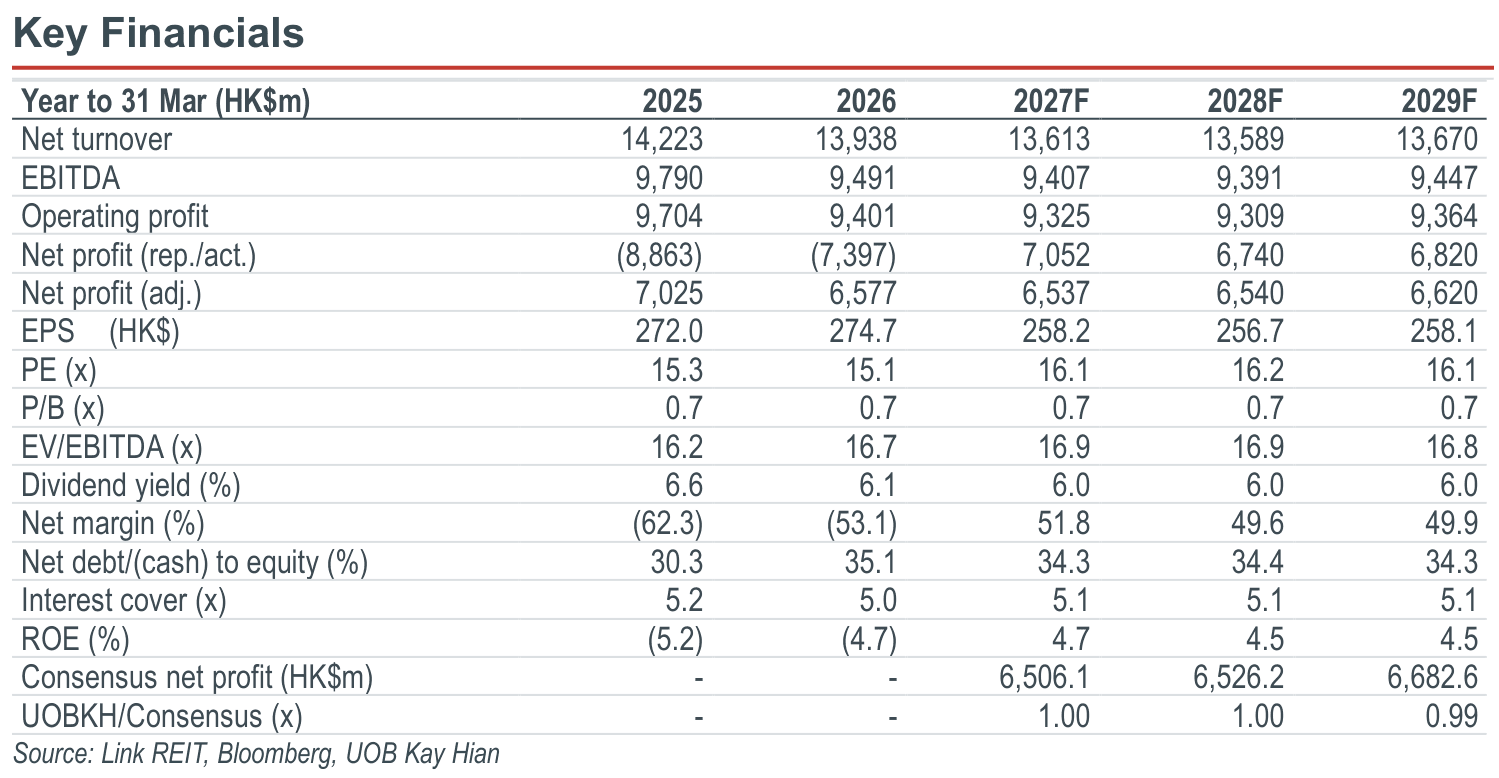
- We raise FY27-29 earnings by 0.5% on lower G&A. Maintain BUY with a higher target price of HK$45.70 (DDM, terminal growth 3.2%).
Analysis
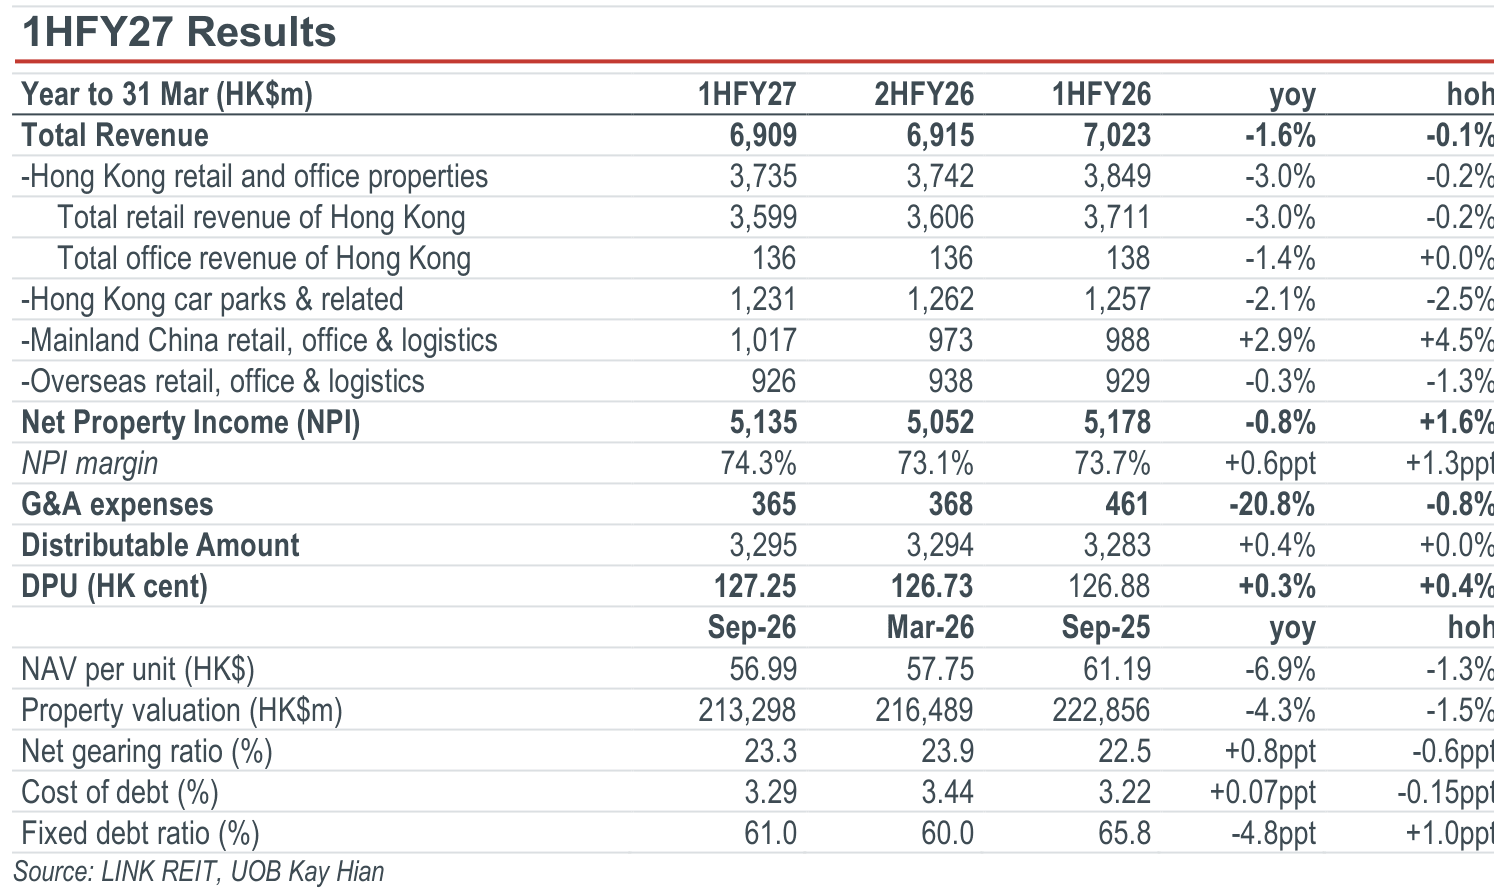
- 1HFY27 results slightly ahead of our expectations. DPU rose 0.3% yoy to HK$1.2725, 51% of our full-year estimate. Revenue fell 1.6% yoy and NPI fell 0.8% yoy due to negative Hong Kong retail rental reversion (-7.5% vs -8.2% in FY26). Cost control partly offset this - NPI margin rose 0.6ppt to 74.3% and G&A fell 21%. Valuation fell 1.5% hoh to HK$213.3b. This was mainly due to the disposals of Swing By @ Thomson Plaza and a 50% stake in 100 Market Street, in addition to lower Hong Kong market rents. Hong Kong cap rates were unchanged. Net gearing fell 0.6ppt hoh to 23.3% on lower net debt. Average all-in borrowing cost rose 7bps yoy to 3.29%.
Highlights
- 1HFY27 DPU rose 0.3% yoy to 127.25 HK cents, accounting for 51% of our FY27 forecast and slightly ahead of our expectations.
- Hong Kong tenant sales was broadly stable (-0.2% yoy), while retail rental reversion was -7.5%. Management reiterated guidance for FY27 Hong Kong rental reversion and is planning HK$1b-2b of buybacks in 2HFY27.
- We raise FY27-29 earnings by 0.5% on lower G&A. Maintain BUY with a higher target price of HK$45.70 (DDM, terminal growth 3.2%).
Analysis
- 1HFY27 results slightly ahead of our expectations. DPU rose 0.3% yoy to HK$1.2725, 51% of our full-year estimate. Revenue fell 1.6% yoy and NPI fell 0.8% yoy due to negative Hong Kong retail rental reversion (-7.5% vs -8.2% in FY26). Cost control partly offset this - NPI margin rose 0.6ppt to 74.3% and G&A fell 21%. Valuation fell 1.5% hoh to HK$213.3b. This was mainly due to the disposals of Swing By @ Thomson Plaza and a 50% stake in 100 Market Street, in addition to lower Hong Kong market rents. Hong Kong cap rates were unchanged. Net gearing fell 0.6ppt hoh to 23.3% on lower net debt. Average all-in borrowing cost rose 7bps yoy to 3.29%.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$41.50
HK$45.70
+10.1%
HK$44.30
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Nov 2026
Hong Kong Property: Larger Units Lead As Their Supply Shrinks

27 Oct 2026
China Property: Oct 26: Supply Keeps Contracting While Sales Diverge, With Tier 1 And Second-hand Homes Ahead

6 Nov 2026
ECARX Holdings Inc (ECX US) - 3Q26: Memory Costs Cut Gross Margin To 7.0%
Our latest research
13 Nov 2026
TA: Link Real Estate Investment Trust (0823 HK) / Sino Biopharmaceutical (1177 HK)

13 Nov 2026
Edge Medical (2675 HK): Price War Clouds 2026 Revenue; Seeking Strategic Shift Toward High-end Market Via New Product Launches
12 Nov 2026