
Company Coverage
ECARX Holdings Inc (ECX US) - 3Q26: Memory Costs Cut Gross Margin To 7.0%
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$0.703
US$2.20
+212.9%
US$2.70
Analyst
Highlights
- 3Q26 net loss widened to US$48.4m, missing our estimates, as gross margin fell 14.9ppt yoy to 7.0% on memory costs that outpaced price increases.
- Revenue rose 9.5% yoy and 6.9% qoq to US$240.8m, and management reaffirmed 2026 revenue guidance of US$1.0b-1.1b.
- We cut 2026-28 bottom line forecasts to a US$104m loss, US$22m and US$59m respectively.
- Maintain BUY, as Volkswagen programmes from 2027 reduce reliance on Geely, while Flyme, the cockpit software business acquired by ECARX, adds software revenue.
Analysis
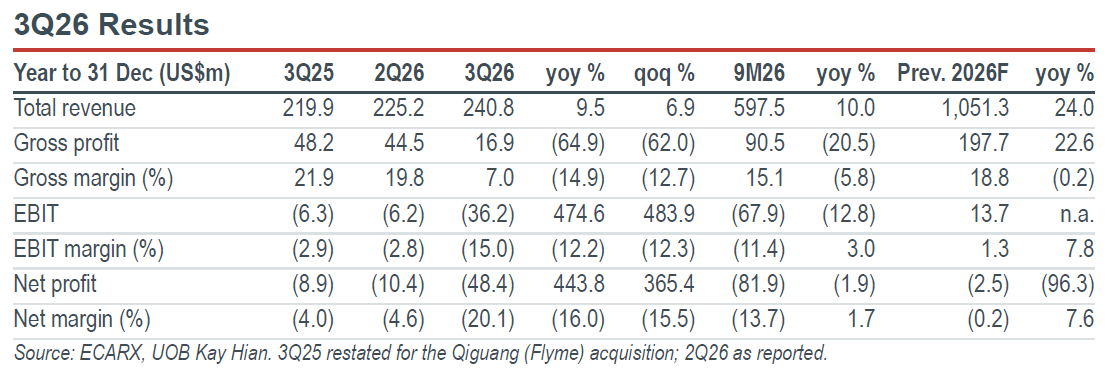
3Q26 results missed our estimates, as memory costs cut gross margin to 7.0%. ECARX Holdings Inc's (ECARX) gross profit fell 64.9% yoy/62.0% qoq to US$16.9m in 3Q26. Its net loss widened 443.8% yoy/365.4% qoq to US$48.4m, and its operating loss widened 474.6% yoy/483.9% qoq to US$36.2m. The 9M26 net loss of US$81.9m already exceeds our pre-revision 2026 forecast of a US$2.5m loss an consensus forecast of a US$9.2m loss. Adjusted EBITDA, which excludes share-based compensation of US$0.7m as well as interest, tax and depreciation and amortisation, swung to a loss of US$37.7m from a profit of US$0.5m in 2Q26.
Highlights
- 3Q26 net loss widened to US$48.4m, missing our estimates, as gross margin fell 14.9ppt yoy to 7.0% on memory costs that outpaced price increases.
- Revenue rose 9.5% yoy and 6.9% qoq to US$240.8m, and management reaffirmed 2026 revenue guidance of US$1.0b-1.1b.
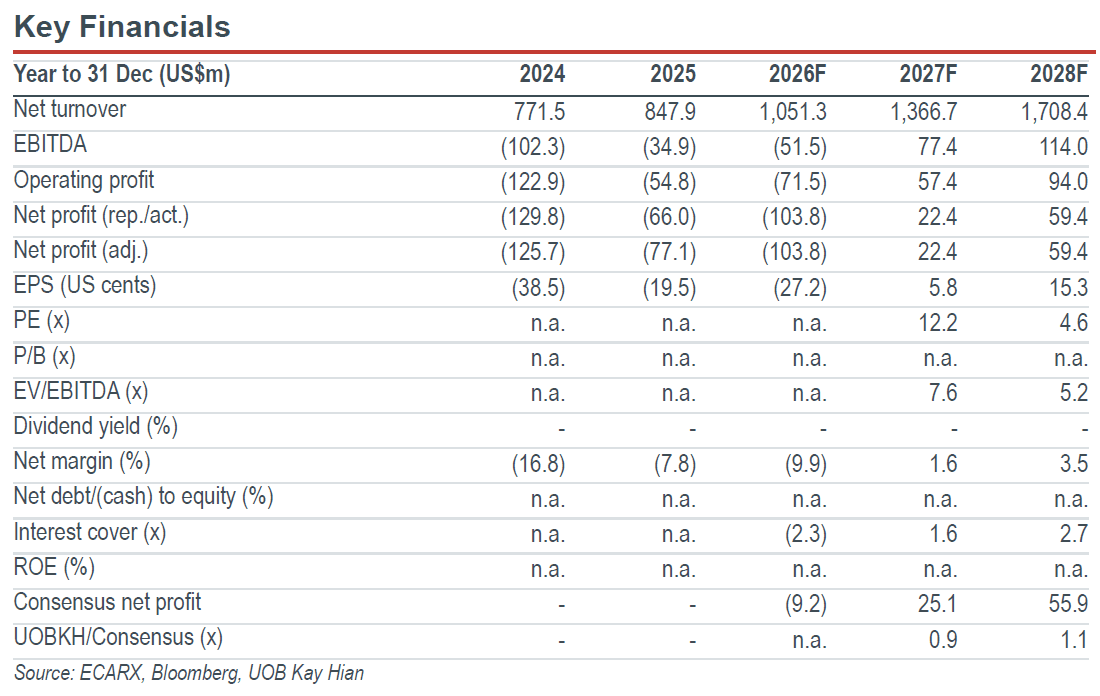
- We cut 2026-28 bottom line forecasts to a US$104m loss, US$22m and US$59m respectively.
- Maintain BUY, as Volkswagen programmes from 2027 reduce reliance on Geely, while Flyme, the cockpit software business acquired by ECARX, adds software revenue.
Analysis
3Q26 results missed our estimates, as memory costs cut gross margin to 7.0%. ECARX Holdings Inc's (ECARX) gross profit fell 64.9% yoy/62.0% qoq to US$16.9m in 3Q26. Its net loss widened 443.8% yoy/365.4% qoq to US$48.4m, and its operating loss widened 474.6% yoy/483.9% qoq to US$36.2m. The 9M26 net loss of US$81.9m already exceeds our pre-revision 2026 forecast of a US$2.5m loss an consensus forecast of a US$9.2m loss. Adjusted EBITDA, which excludes share-based compensation of US$0.7m as well as interest, tax and depreciation and amortisation, swung to a loss of US$37.7m from a profit of US$0.5m in 2Q26.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$0.703
US$2.20
+212.9%
US$2.70
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
NAURA Technology Group (002371 CH): 3Q26: Temporary Weakness Due To Component Shortage; Demand Pushed Back To 4Q26

14 Oct 2026
Lenovo Group (992 HK): PC Shipments Miss Expectations In 3Q26

30 Oct 2026
BYD Electronics (285 HK): 3Q26: Consumer Electronics Continues To Drag Profitability
Our latest research
6 Nov 2026
TA: Swire Pacific (0019 HK) / JD Health International (6618 HK)

6 Nov 2026
BeOne Medicines (6160 HK) - 3Q26: Results Outperform; Raising 2026 Guidance Again

6 Nov 2026