
Company Coverage
Sino Biopharmaceutical (1177 HK): US$7b Boehringer Ingelheim Deal To Boost Growth In 2027
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$5.63
HK$7.50
+33.3%
HK$7.20
Analyst
Analyst
Highlights
- Sino Biopharm and BI have entered into a US$7b strategic collaboration, with upfront and near-term milestone payment of US$358m, plus double-digit royalties.
- This marks the two parties' second oncology collaboration and Sino Biopharm's third MNC out-licensing deal in 2026, with total licensing value for the year exceeding US$10b.
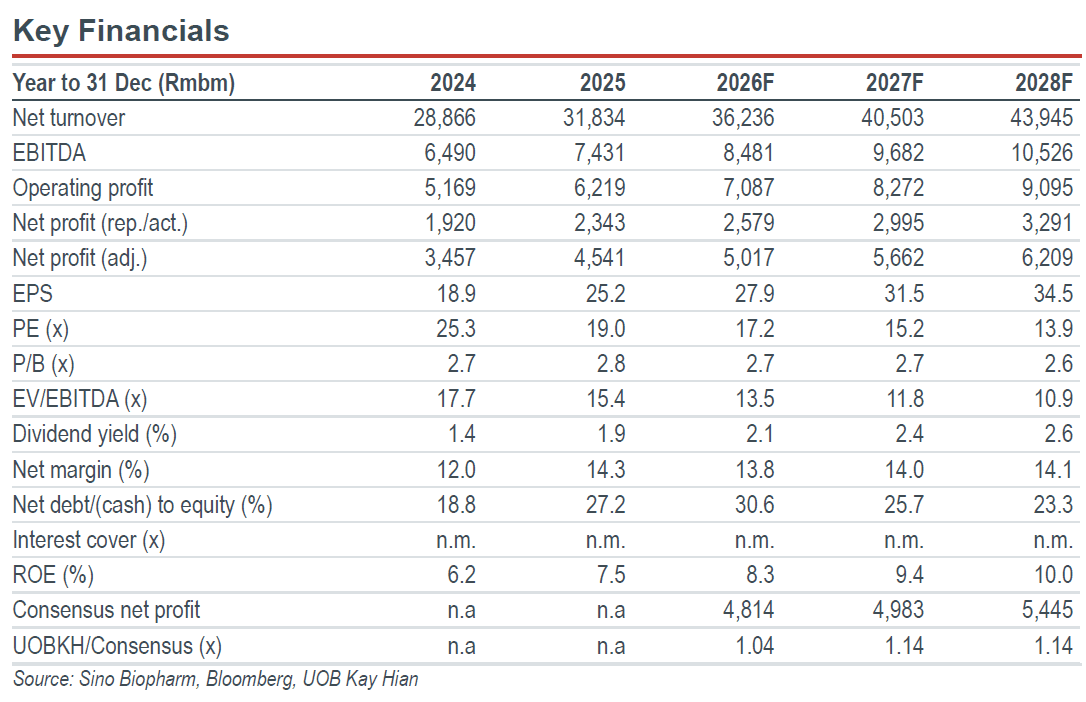
- Most of the upfront payment expected to be recognised next year, and this will significantly boost revenue and earnings growth in 2027.
- Maintain BUY and raise target price to HK$7.50.
Analysis
- Entered into US$7b collaboration with Boehringer Ingelheim. Sino Biopharmaceutical (Sino Biopharm) has entered into a strategic option and license agreement with Boehringer Ingelheim (BI) on six preclinical asset programmes. The total deal value amounts to US$7b, including US$358m in upfront and near-term milestone income. The six pre-clinical oncology assets span antibody-drug conjugates (ADCs) and T-cell engager (TCEs). Pursuant to the agreement, Sino Biopharmaceutical (Sino Biopharm) is responsible for early research through global phase 1 clinical trials; upon achieving the agreed clinical milestones, Boehringer Ingelheim has the right to exercise its options (subject to an additional option exercise fee) to obtain exclusive global rights (excluding Mainland China, Hong Kong, and Macau) for the development, manufacturing, and commercialisation of four projects, and exclusive global rights for two projects.
- Strong BD momentum supports global development of its innovative pipeline. This new out-licensing deal is the second collaboration between the two parties in oncology. Ytd, Sino Biopharmaceutical has completed three out-licensing deals with MNCs (Sanofi, AstraZeneca, and BI), with the total deal value exceeding US$10b. The robust business development (BD) momentum has not only brought in significant cash flow and lifted revenue, but also provided strong support for the global development of its innovative pipeline and created long-term value gains. The company is actively seeking BD opportunities for its innovative assets and is expecting more BD deals in the years ahead.
Highlights
- Sino Biopharm and BI have entered into a US$7b strategic collaboration, with upfront and near-term milestone payment of US$358m, plus double-digit royalties.
- This marks the two parties' second oncology collaboration and Sino Biopharm's third MNC out-licensing deal in 2026, with total licensing value for the year exceeding US$10b.
- Most of the upfront payment expected to be recognised next year, and this will significantly boost revenue and earnings growth in 2027.
- Maintain BUY and raise target price to HK$7.50.
Analysis
- Entered into US$7b collaboration with Boehringer Ingelheim. Sino Biopharmaceutical (Sino Biopharm) has entered into a strategic option and license agreement with Boehringer Ingelheim (BI) on six preclinical asset programmes. The total deal value amounts to US$7b, including US$358m in upfront and near-term milestone income. The six pre-clinical oncology assets span antibody-drug conjugates (ADCs) and T-cell engager (TCEs). Pursuant to the agreement, Sino Biopharmaceutical (Sino Biopharm) is responsible for early research through global phase 1 clinical trials; upon achieving the agreed clinical milestones, Boehringer Ingelheim has the right to exercise its options (subject to an additional option exercise fee) to obtain exclusive global rights (excluding Mainland China, Hong Kong, and Macau) for the development, manufacturing, and commercialisation of four projects, and exclusive global rights for two projects.
- Strong BD momentum supports global development of its innovative pipeline. This new out-licensing deal is the second collaboration between the two parties in oncology. Ytd, Sino Biopharmaceutical has completed three out-licensing deals with MNCs (Sanofi, AstraZeneca, and BI), with the total deal value exceeding US$10b. The robust business development (BD) momentum has not only brought in significant cash flow and lifted revenue, but also provided strong support for the global development of its innovative pipeline and created long-term value gains. The company is actively seeking BD opportunities for its innovative assets and is expecting more BD deals in the years ahead.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$5.63
HK$7.50
+33.3%
HK$7.20
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Shenzhen Mindray Bio-Medical Electronics (300760 CH) - 9M26: Results In Line; Overseas And Emerging Businesses To Continue Driving Growth In 2027

2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026

2 Nov 2026
Estun Automation (002747 CH) - 3Q26: Mixed Quarter But Profitability Improvements Ahead of Expectations
Our latest research
6 Nov 2026
TA: Swire Pacific (0019 HK) / JD Health International (6618 HK)

6 Nov 2026
BeOne Medicines (6160 HK) - 3Q26: Results Outperform; Raising 2026 Guidance Again

6 Nov 2026