
Periodic/Sector reports
Hong Kong Property: Larger Units Lead As Their Supply Shrinks
MARKET WEIGHT (Maintained)
Analyst
Analyst
Highlights
- Larger units led in 2026. Agreements above HK$10m rose 40.0-50.7% yoy in 10M26 while those below HK$4m fell 9.2%. In 9M26, Class D-E prices rose 7.6% and rents 8.8%, against 7.0% and 5.7% for Class A-C.
- Supply has shifted to small units. Class A made up 43.0% of completions in 2016-25, against 11.2% in 2006-15, and RVD forecasts 64.1% in 2027, with only 202 (3.0%) Class D-E units. We expect small-unit prices to face pressure in 2027 and large-unit prices to hold steady.
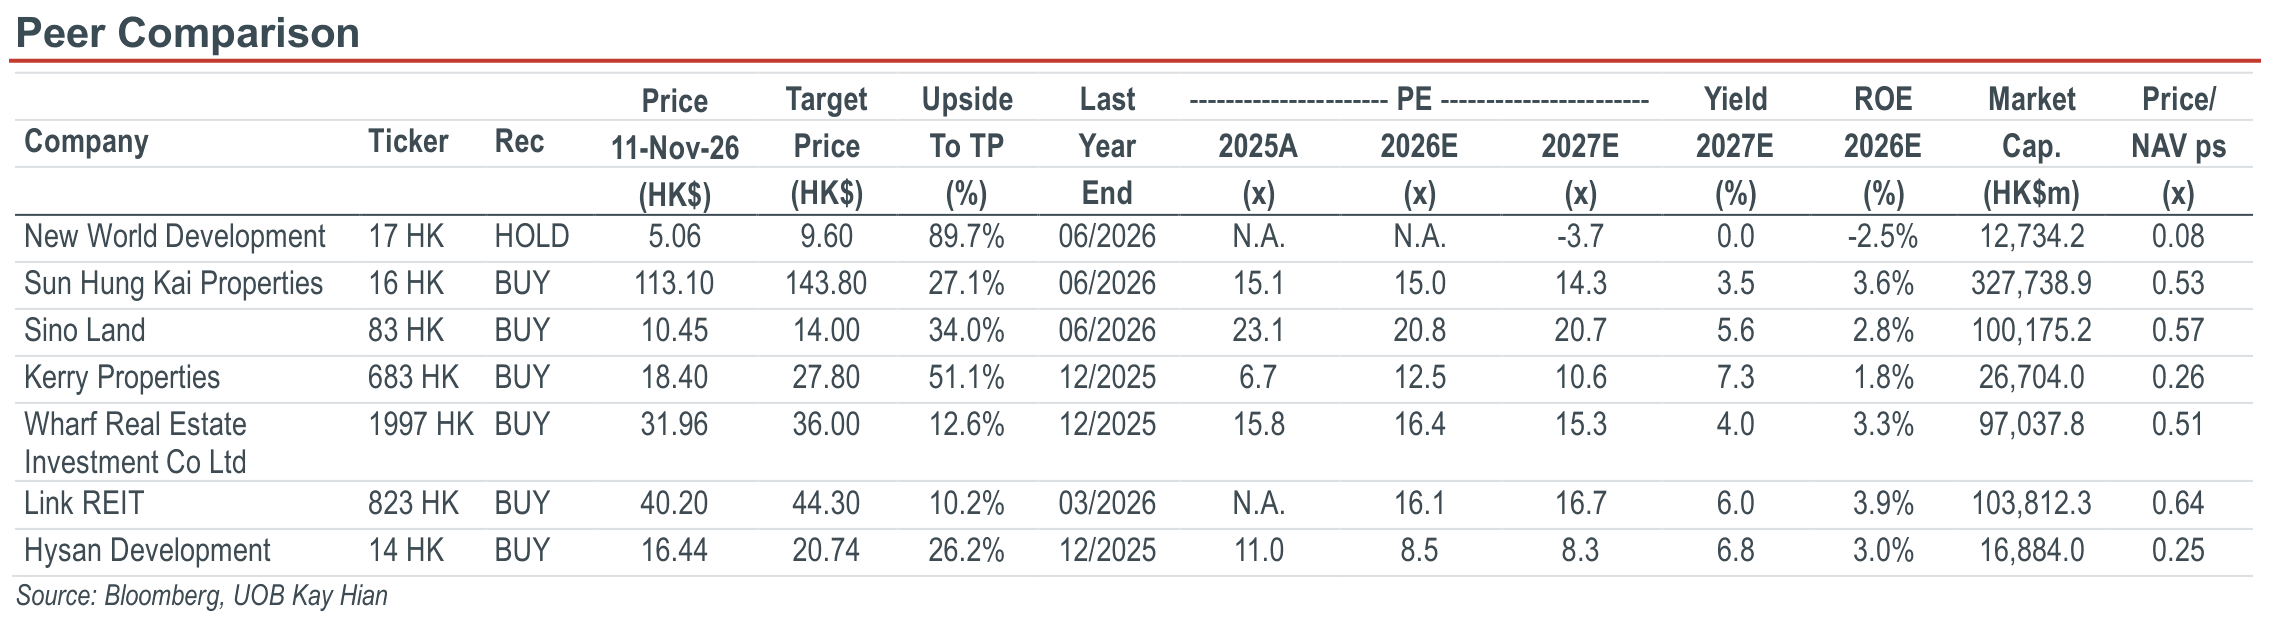
- Maintain MARKET WEIGHT. SHKP is our top pick; highlight Kerry Properties for strong high-end market exposure and attractive yield..
Analysis
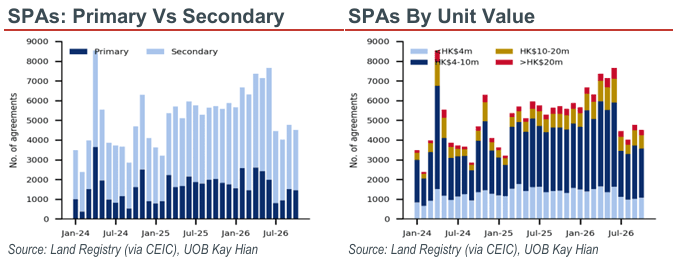
- Larger units led the 2026 transaction growth. In 10M26, residential sale and purchase agreements (SPA) number rose 14.0% yoy to 58,564 units, with primary and secondary transactions up 1.5% and 20.2% yoy respectively. Transaction value rose faster, by 20.7% in the primary market and 33.7% in the secondary market, pointing to a higher value per deal, particularly for new homes: The average primary agreement rose 18.9% yoy to HK$12.5m, against 11.2% to HK$7.7m in the secondary market. Stronger volume growth in larger units supports this: Agreements below HK$4m fell 9.2% yoy, while those at HK$4m-10m, HK$10m-20m and above HK$20m rose 16.3%, 50.7% and 40.0%. SPAs: Primary Vs Secondary SPAs By Unit Value Source: Land Registry (via CEIC), UOB Kay Hian Source: Land Registry (via CEIC), UOB Kay Hian
- Larger units also outperformed on rent increase in 2026, although price gains were broadly similar across unit sizes. The RVD residential price index rose 7.1% in 9M26, with prices of Class A-C and Class D-E units up 7.0% and 7.6% respectively. RVD residential rental index for Class D-E rents rose 8.8%, against 5.7% for Class A-C.
Highlights
- Larger units led in 2026. Agreements above HK$10m rose 40.0-50.7% yoy in 10M26 while those below HK$4m fell 9.2%. In 9M26, Class D-E prices rose 7.6% and rents 8.8%, against 7.0% and 5.7% for Class A-C.
- Supply has shifted to small units. Class A made up 43.0% of completions in 2016-25, against 11.2% in 2006-15, and RVD forecasts 64.1% in 2027, with only 202 (3.0%) Class D-E units. We expect small-unit prices to face pressure in 2027 and large-unit prices to hold steady.
- Maintain MARKET WEIGHT. SHKP is our top pick; highlight Kerry Properties for strong high-end market exposure and attractive yield..
Analysis
- Larger units led the 2026 transaction growth. In 10M26, residential sale and purchase agreements (SPA) number rose 14.0% yoy to 58,564 units, with primary and secondary transactions up 1.5% and 20.2% yoy respectively. Transaction value rose faster, by 20.7% in the primary market and 33.7% in the secondary market, pointing to a higher value per deal, particularly for new homes: The average primary agreement rose 18.9% yoy to HK$12.5m, against 11.2% to HK$7.7m in the secondary market. Stronger volume growth in larger units supports this: Agreements below HK$4m fell 9.2% yoy, while those at HK$4m-10m, HK$10m-20m and above HK$20m rose 16.3%, 50.7% and 40.0%. SPAs: Primary Vs Secondary SPAs By Unit Value Source: Land Registry (via CEIC), UOB Kay Hian Source: Land Registry (via CEIC), UOB Kay Hian
- Larger units also outperformed on rent increase in 2026, although price gains were broadly similar across unit sizes. The RVD residential price index rose 7.1% in 9M26, with prices of Class A-C and Class D-E units up 7.0% and 7.6% respectively. RVD residential rental index for Class D-E rents rose 8.8%, against 5.7% for Class A-C.
MARKET WEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

27 Oct 2026
China Property: Oct 26: Supply Keeps Contracting While Sales Diverge, With Tier 1 And Second-hand Homes Ahead

20 Oct 2026
China Property: NBS: New-home Sales Decline Deepens To 22.6% yoy In Sep 26; Second-Hand Market Continues To Outperform

5 Nov 2026
Automobile: China Auto Sector Weekly (5 Nov 26)
Our latest research
5 Nov 2026
Automobile: China Auto Sector Weekly (5 Nov 26)
27 Oct 2026
China Property: Oct 26: Supply Keeps Contracting While Sales Diverge, With Tier 1 And Second-hand Homes Ahead

23 Oct 2026