

Company Coverage
New World Development (17 HK): Rights Issue Strenghtens Balance Sheet but Dilutes NAV per Share by 90%
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$2.885
HK$2.700
-6.4%
HK$6.44
Analyst
Analyst
Highlights
- NWD has proposed an 11-for-1 rights issue at HK$0.90 per share to raise HK$24.9b, an 81.5% discount to the last close, fully underwritten by CTFE, HSBC and DBS. It is inter-conditional with a two-year extension of HK$82.0b of bank loans after a 10% prepayment.
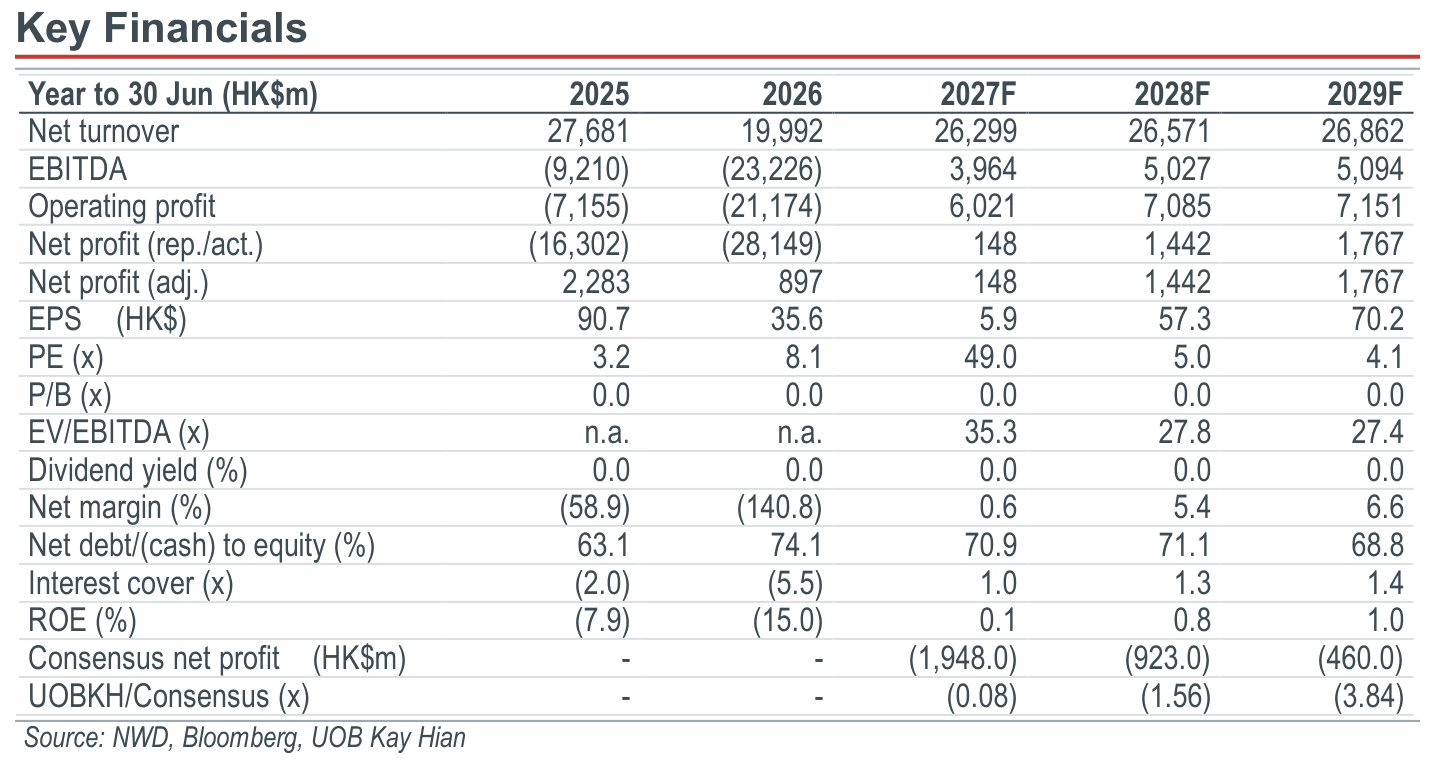
- The rights issue is expected to lower net gearing by 20.0ppt to 48.3% and lower adjusted net gearing to 71%. Cash to short-term debt ratio is expected to recover to 1x. However, financial risks remain with 70% gearing ratio. The share count rises 12-fold, lowering our NAV per share by 89.1%.
- Maintain HOLD with a lower target price of HK$2.70 (previously HK$6.44), including the value of the rights. Excluding the rights, our NAV-derived target price is HK$1.05, based on a narrower NAV discount of 70% (previously 80%) to our post-rights NAV, reflecting the improved debt metrics.
Analysis
- Issue price at fair discount to diluted NAV; completion is conditional. New World Development (NWD) has proposed a 11-for-1 rights issue, issuing 27.68b rights shares at HK$0.90, raising HK$24.1b net. The price is 26.9% below the theoretical ex-rights price (TERP) of HK$1.23. Considering the dilution effect, this issue price is at 75%/85% discount to our estimated and company’s reported NAV per share of HK$3.5/HK$5.8, respectively, so the issue price is not cheap in our view. The issue is inter-conditional with the prepayment of 10% of HK$82.0b of offshore bank loans due Mar 27-Dec 29 and a two-year extension of the remaining HK$73.8b, which needs all lenders to sign. The whitewash waiver needs at least 75% of independent shareholders’votes.
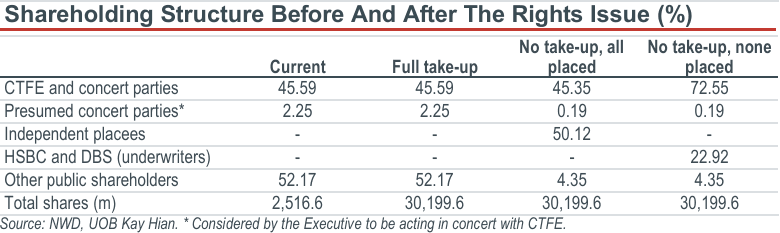
- ull underwritten may increase control concentration. CTFE (45.3%) will take up its full entitlement of about HK$11.3b and underwrite up to a further 29.7% of the issue, with HSBC and DBS underwriting the remaining 25%. We expect capital contribution from CTFE to range between HK$11b-20b.
Highlights
- NWD has proposed an 11-for-1 rights issue at HK$0.90 per share to raise HK$24.9b, an 81.5% discount to the last close, fully underwritten by CTFE, HSBC and DBS. It is inter-conditional with a two-year extension of HK$82.0b of bank loans after a 10% prepayment.
- The rights issue is expected to lower net gearing by 20.0ppt to 48.3% and lower adjusted net gearing to 71%. Cash to short-term debt ratio is expected to recover to 1x. However, financial risks remain with 70% gearing ratio. The share count rises 12-fold, lowering our NAV per share by 89.1%.
- Maintain HOLD with a lower target price of HK$2.70 (previously HK$6.44), including the value of the rights. Excluding the rights, our NAV-derived target price is HK$1.05, based on a narrower NAV discount of 70% (previously 80%) to our post-rights NAV, reflecting the improved debt metrics.
Analysis
- Issue price at fair discount to diluted NAV; completion is conditional. New World Development (NWD) has proposed a 11-for-1 rights issue, issuing 27.68b rights shares at HK$0.90, raising HK$24.1b net. The price is 26.9% below the theoretical ex-rights price (TERP) of HK$1.23. Considering the dilution effect, this issue price is at 75%/85% discount to our estimated and company’s reported NAV per share of HK$3.5/HK$5.8, respectively, so the issue price is not cheap in our view. The issue is inter-conditional with the prepayment of 10% of HK$82.0b of offshore bank loans due Mar 27-Dec 29 and a two-year extension of the remaining HK$73.8b, which needs all lenders to sign. The whitewash waiver needs at least 75% of independent shareholders’votes.
- ull underwritten may increase control concentration. CTFE (45.3%) will take up its full entitlement of about HK$11.3b and underwrite up to a further 29.7% of the issue, with HSBC and DBS underwriting the remaining 25%. We expect capital contribution from CTFE to range between HK$11b-20b.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$2.885
HK$2.700
-6.4%
HK$6.44
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Geely Auto (175 HK): 3Q26: Earnings Slightly Miss Our Estimates On Share-based Payments

6 Nov 2026
Sino Biopharmaceutical (1177 HK): US$7b Boehringer Ingelheim Deal To Boost Growth In 2027

13 Nov 2026
Edge Medical (2675 HK): Price War Clouds 2026 Revenue; Seeking Strategic Shift Toward High-end Market Via New Product Launches
Our latest research

17 Nov 2026
Baidu Inc (9888 HK): 3Q26: Earnings Beat; AI Cloud Growth Cushions Ad Weakness

16 Nov 2026
ChangXin Memory Technologies (688825 CH): China’s Rising DRAM Champion Amid The Memory Supercycle
13 Nov 2026