

Company Coverage
Geely Auto (175 HK): 3Q26: Earnings Slightly Miss Our Estimates On Share-based Payments
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$13.57
HK$21.00
58.4%
HK$29.00
Analyst
Highlights
- 3Q26 adjusted net profit of Rmb5.2b (+31.6% yoy/+1.7% qoq) met consensus forecast but slightly missed our estimate, due to share-based payment.
- Forward earnings growth will be driven by new techs, strong product line-ups, overseas expansion and premiumisation.
- We cut our 2026-28 net profit forecasts by 11%/2%/2% to Rmb18.91b/Rmb26.86b/Rmb33.64b respectively to factor in forex loss and share-based payments.
- Maintain BUY and cut target price from HK$29.00 to HK$21.00.
Analysis
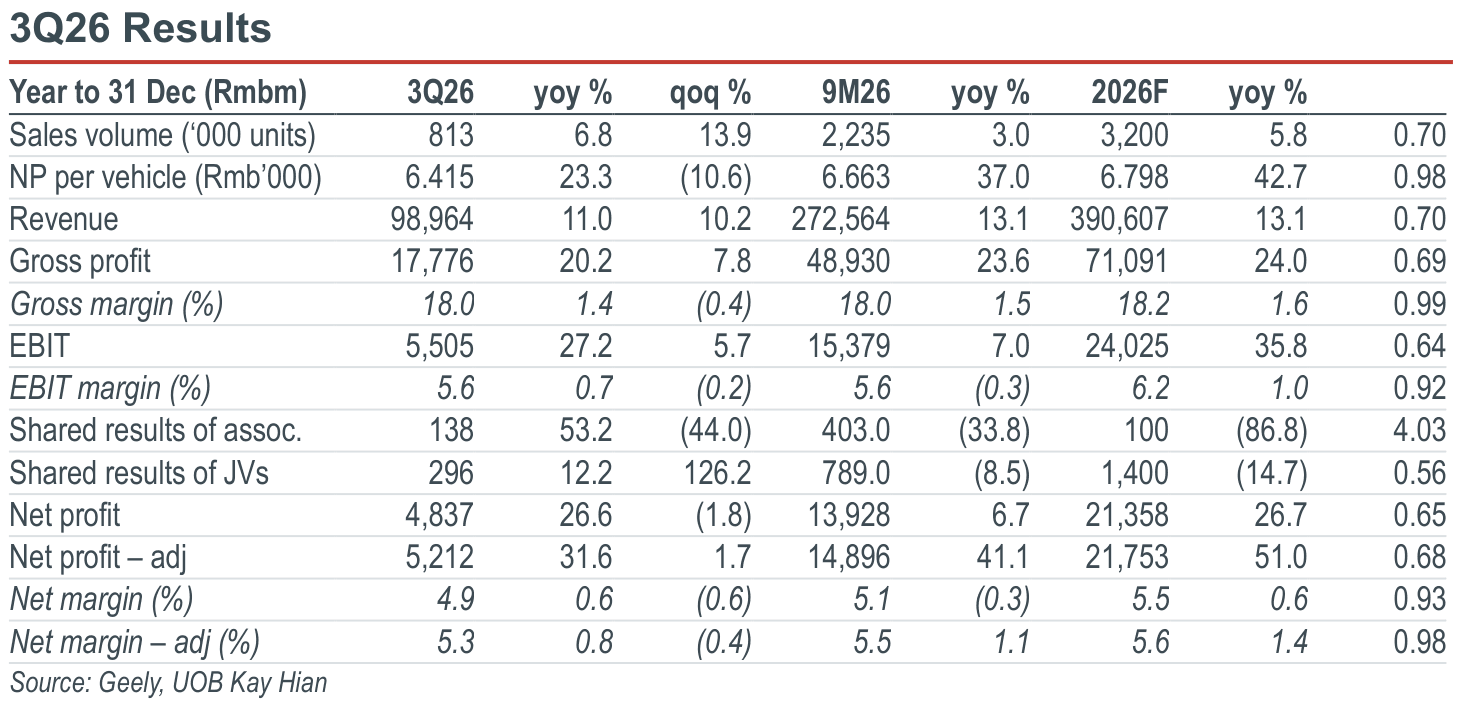
- 3Q26 core earnings slightly missed our estimates but met consensus, with reported net profit of Rmb4,837m (+26.6% yoy/-1.8% qoq), vs our estimate of Rmb5,125m and consensus estimate of Rmb4,847m, and adjusted net profit of Rmb5,212m (+31.6% yoy/+1.7% qoq), vs our forecast of Rmb5,525m and consensus forecast of Rmb5,186m. The slight core earnings miss to our estimates stemmed from share-based payments.
- Revenue in line. Revenue grew 11% yoy/10% qoq in 3Q26 on 6.8%/13.9% qoq sales volume growth. This brings 9M26 revenue to Rmb272.56b (+13.1% yoy), representing 70% of our 2026 estimate.
- Revenue in line. Revenue grew 11% yoy/10% qoq in 3Q26 on 6.8%/13.9% qoq sales volume growth. This brings 9M26 revenue to Rmb272.56b (+13.1% yoy), representing 70% of our 2026 estimate.
Highlights
- 3Q26 adjusted net profit of Rmb5.2b (+31.6% yoy/+1.7% qoq) met consensus forecast but slightly missed our estimate, due to share-based payment.
- Forward earnings growth will be driven by new techs, strong product line-ups, overseas expansion and premiumisation.
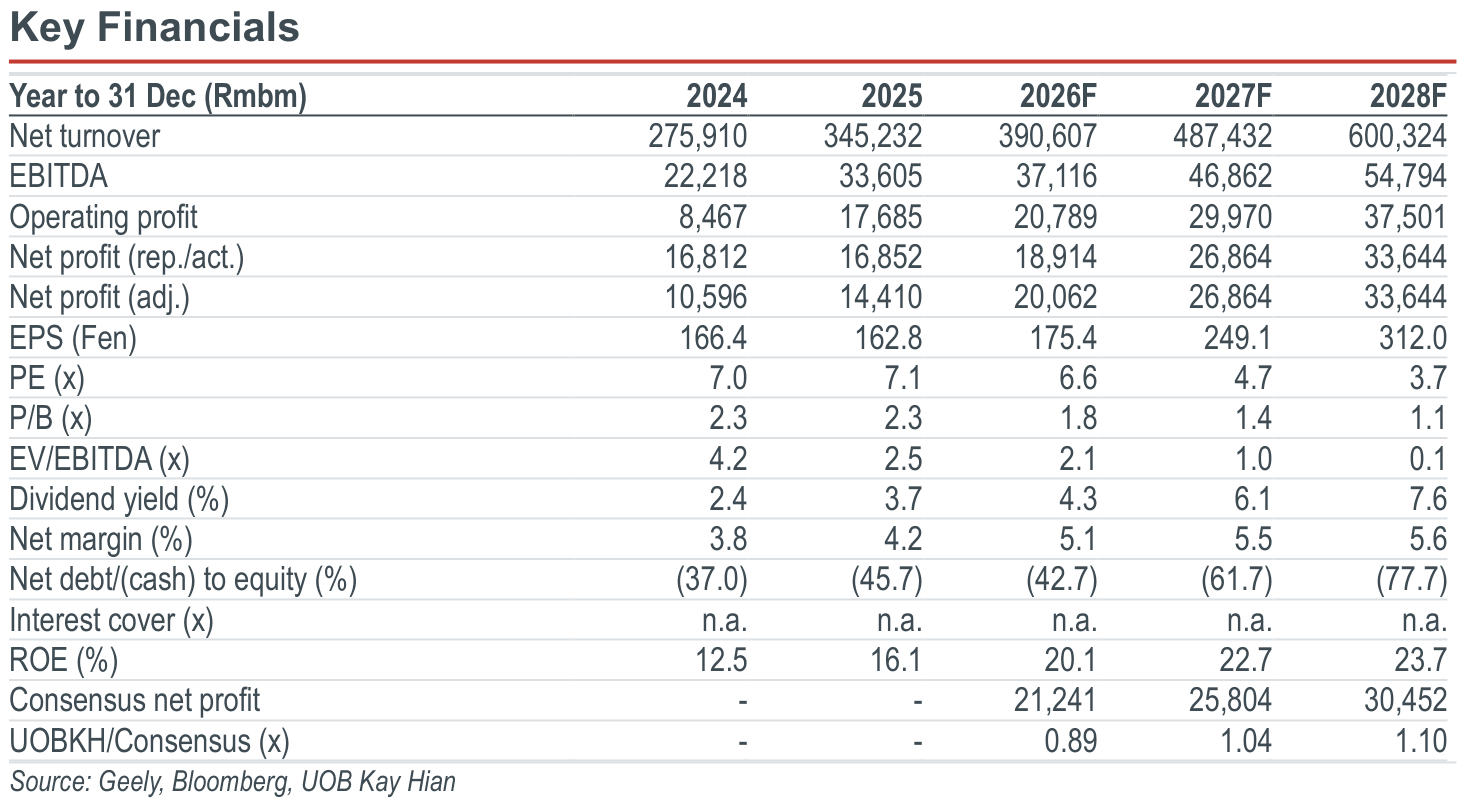
- We cut our 2026-28 net profit forecasts by 11%/2%/2% to Rmb18.91b/Rmb26.86b/Rmb33.64b respectively to factor in forex loss and share-based payments.
- Maintain BUY and cut target price from HK$29.00 to HK$21.00.
Analysis
- 3Q26 core earnings slightly missed our estimates but met consensus, with reported net profit of Rmb4,837m (+26.6% yoy/-1.8% qoq), vs our estimate of Rmb5,125m and consensus estimate of Rmb4,847m, and adjusted net profit of Rmb5,212m (+31.6% yoy/+1.7% qoq), vs our forecast of Rmb5,525m and consensus forecast of Rmb5,186m. The slight core earnings miss to our estimates stemmed from share-based payments.
- Revenue in line. Revenue grew 11% yoy/10% qoq in 3Q26 on 6.8%/13.9% qoq sales volume growth. This brings 9M26 revenue to Rmb272.56b (+13.1% yoy), representing 70% of our 2026 estimate.
- Revenue in line. Revenue grew 11% yoy/10% qoq in 3Q26 on 6.8%/13.9% qoq sales volume growth. This brings 9M26 revenue to Rmb272.56b (+13.1% yoy), representing 70% of our 2026 estimate.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$13.57
HK$21.00
58.4%
HK$29.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00

28 Oct 2026
Huizhou Desay SV (002920 CH): 3Q26: Revenue Growth Accelerates To 24%, But Earnings Miss On Subsidy Cuts, Credit Provisions, Associates’ Losses, And Tax Hikes

30 Oct 2026
Foxconn Industrial Internet (601138 CH): 3Q26: Sustained AI infrastructure demand drives earnings beat
Our latest research
30 Oct 2026
TA: CITIC (0267 HK) / Geely Automobile (0175 HK)

30 Oct 2026
Budweiser APAC (1876 HK): 3Q26: Revenue In Line But EBITDA Misses

30 Oct 2026