

Company Coverage
China Resources Mixc Lifestyle (1209 HK): Oct 26 Operational Update: SSS Slips; Cutting Mall Forecasts And Target Price
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$37.50
HK$50.00
+33.3%
HK$55.00
Analyst
Analyst
Highlights
- We estimate CR Mixc's mall retail sales grew by low single digits yoy in Oct 26, with SSS down slightly. Luxury malls reported weaker SSS than the overall portfolio for the first time this year. In 10M26, we estimate total retail sales grew by double digits yoy and SSS rose by mid-single digits, with luxury malls in line with the portfolio.
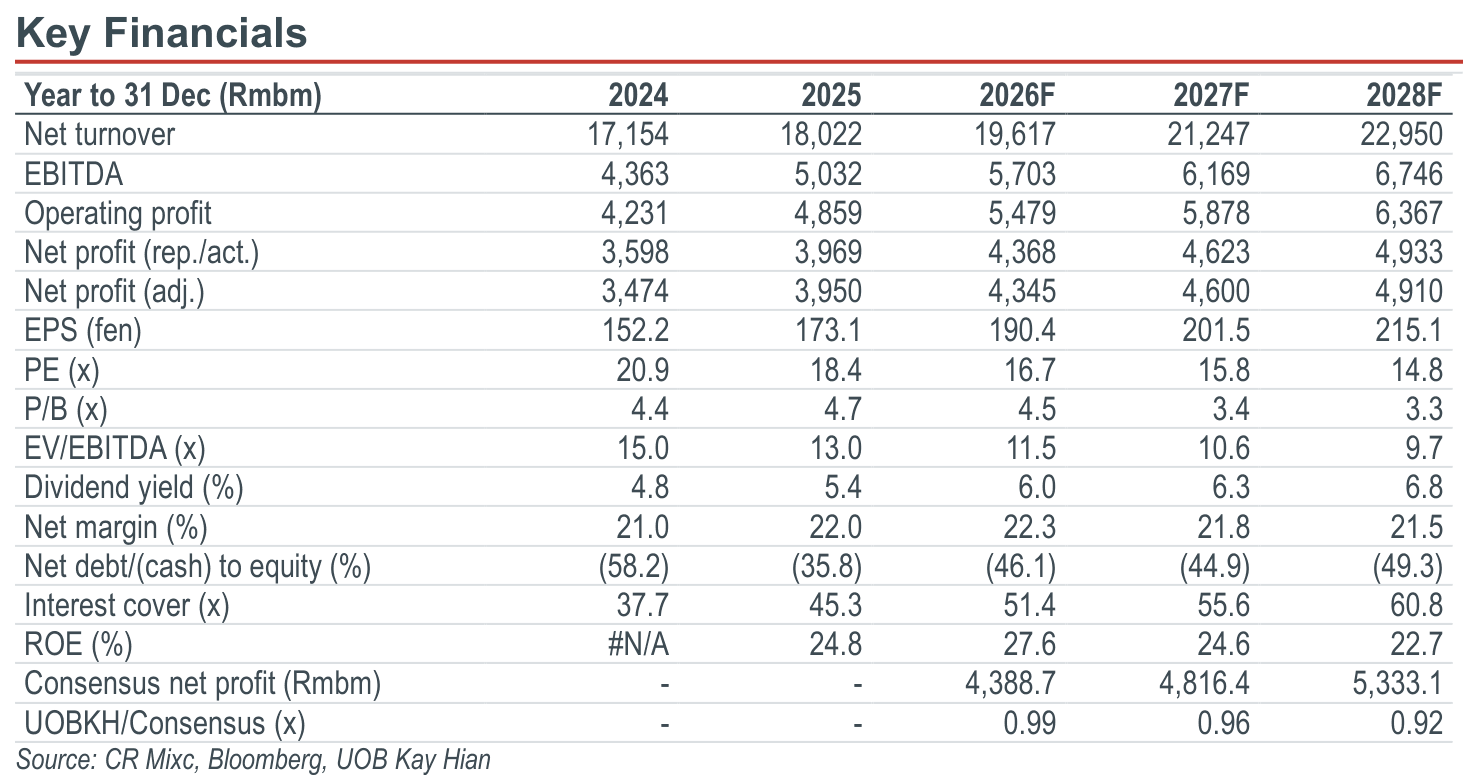
- We expect luxury sales growth to slow and SSS to decline in 1H27. We cut our 2026-28 mall revenue growth forecasts to 14.1%/9%/10% and our core net profit forecasts by 0.9%/5.7%/8.2% respectively. We still expect CR Mixc to meet its 2026 guidance of double-digit core net profit growth.
- We use DCF (WACC: 8.7%, terminal growth rate: 2.5%) to derive our target price of HK$50.00 (from HK$55.00 previously). Maintain BUY.
Analysis
- Mall retail sales slowed in October. We estimate total retail sales across CR Mixc's malls grew by low single digits yoy in Oct 26, slower than the high single-digit growth we estimated for Sep 26, with same-store sales (SSS) down slightly yoy. SSS at its luxury malls was weaker than the overall portfolio, marking the first such instance this year. For 10M26, we estimate total retail sales grew by double digits yoy with SSS up by mid-single digits. SSS growth at its luxury malls should be broadly in line with the overall portfolio.
- We lower our mall forecasts for 2027. We expect luxury sales growth to slow and SSS to decline in 1H27, owing to the negative wealth effect of weak property and stock markets. We cut our 2026-28 mall revenue growth forecasts from 15%/15%/14% to 14.1%/9%/10% respectively, and our 2027-28 mall gross margin from 75.9% to 75.0%. New mall openings should support revenue growth, with five openings in 4Q26 (12 in 2026) and 16 in 2027.
Valuation/Recommendation
- Maintain BUY and cut target price from HK$55.00 to HK$50.00. We use DCF (WACC: 8.7%, terminal growth rate: 2.5%) and raise our beta assumption to 0.9 from 0.8, which lifts our WACC from 8.2% to 8.7%. We raise the beta as we expect mid- to high-end retail sales to be hit harder than overall retail sales in 1H27. The stock trades at 17.2x 2026F PE and a 5.8% 2026F dividend yield, and our target price implies 22.5x 2026F PE.
Highlights
- We estimate CR Mixc's mall retail sales grew by low single digits yoy in Oct 26, with SSS down slightly. Luxury malls reported weaker SSS than the overall portfolio for the first time this year. In 10M26, we estimate total retail sales grew by double digits yoy and SSS rose by mid-single digits, with luxury malls in line with the portfolio.
- We expect luxury sales growth to slow and SSS to decline in 1H27. We cut our 2026-28 mall revenue growth forecasts to 14.1%/9%/10% and our core net profit forecasts by 0.9%/5.7%/8.2% respectively. We still expect CR Mixc to meet its 2026 guidance of double-digit core net profit growth.
- We use DCF (WACC: 8.7%, terminal growth rate: 2.5%) to derive our target price of HK$50.00 (from HK$55.00 previously). Maintain BUY.
Analysis
- Mall retail sales slowed in October. We estimate total retail sales across CR Mixc's malls grew by low single digits yoy in Oct 26, slower than the high single-digit growth we estimated for Sep 26, with same-store sales (SSS) down slightly yoy. SSS at its luxury malls was weaker than the overall portfolio, marking the first such instance this year. For 10M26, we estimate total retail sales grew by double digits yoy with SSS up by mid-single digits. SSS growth at its luxury malls should be broadly in line with the overall portfolio.
- We lower our mall forecasts for 2027. We expect luxury sales growth to slow and SSS to decline in 1H27, owing to the negative wealth effect of weak property and stock markets. We cut our 2026-28 mall revenue growth forecasts from 15%/15%/14% to 14.1%/9%/10% respectively, and our 2027-28 mall gross margin from 75.9% to 75.0%. New mall openings should support revenue growth, with five openings in 4Q26 (12 in 2026) and 16 in 2027.
Valuation/Recommendation
- Maintain BUY and cut target price from HK$55.00 to HK$50.00. We use DCF (WACC: 8.7%, terminal growth rate: 2.5%) and raise our beta assumption to 0.9 from 0.8, which lifts our WACC from 8.2% to 8.7%. We raise the beta as we expect mid- to high-end retail sales to be hit harder than overall retail sales in 1H27. The stock trades at 17.2x 2026F PE and a 5.8% 2026F dividend yield, and our target price implies 22.5x 2026F PE.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$37.50
HK$50.00
+33.3%
HK$55.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Midea Group (000333 CH): 3Q26: EBIT Declines 3%; Targets Positive Sales Growth For 4Q26

18 Nov 2026
JD.com (9618 HK): 3Q26: Operating Beat On Margin Expansion And FD Loss Reduction; Retail Returns To Growth

30 Oct 2026
Geely Auto (175 HK): 3Q26: Earnings Slightly Miss Our Estimates On Share-based Payments
Our latest research

20 Nov 2026
NetEase (9999 HK): 3Q26: Revenue And Earnings Miss On Softer Games; Gross Margin Expands

20 Nov 2026
Alibaba Group (9988 HK): 2Q27: Cloud Revenue Beat; Margin Expansion; FCF Outflow Narrows
20 Nov 2026