

Company Coverage
NetEase (9999 HK): 3Q26: Revenue And Earnings Miss On Softer Games; Gross Margin Expands
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
HK$186.90
HK$173.00
-7.4%
HK$252.00
Analyst
Analyst
Highlights
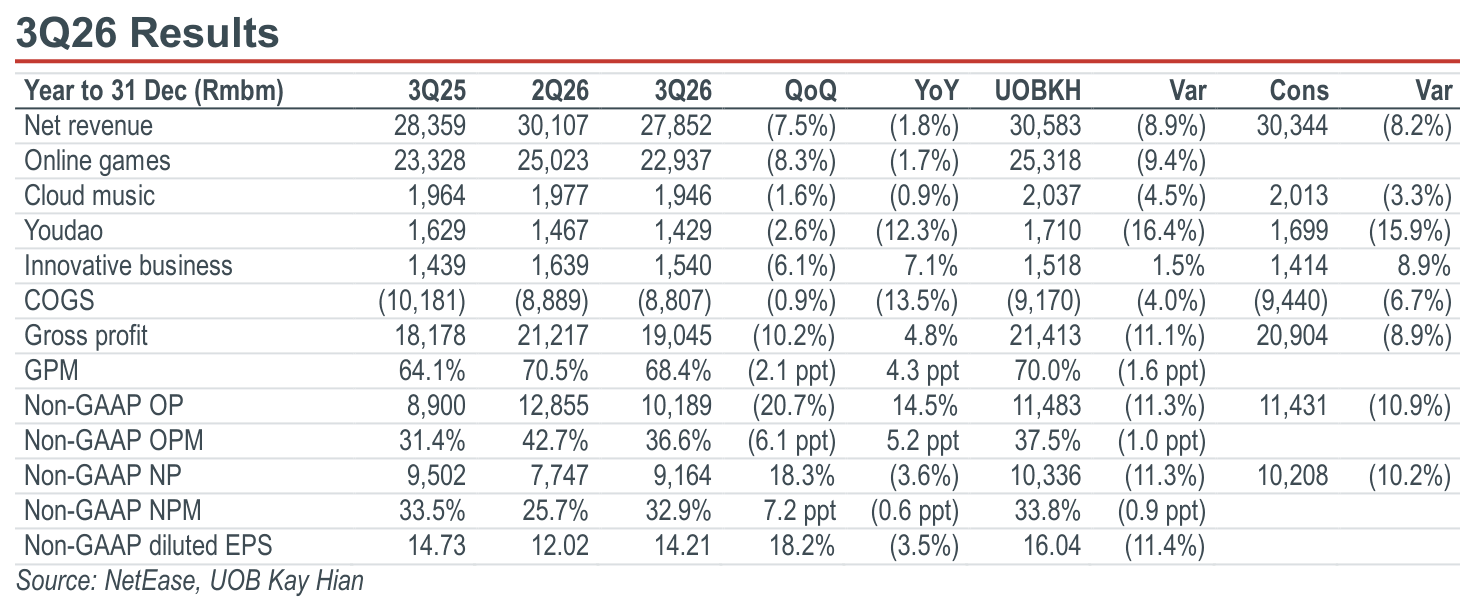
- NetEase’s 3Q26 revenue and earnings missed expectations. Revenue fell 1.8% yoy to Rmb27.9b, 8-9% below our and consensus estimates, mainly due to weaker games revenue. Gross margin expanded 4.3ppt yoy to 68.4% on lower revenue-sharing costs. Non-GAAP net profit fell 3.6% yoy to Rmb9.2b, 10-11% below our and consensus estimates, weighed down by lower investment income and a higher effective tax rate.
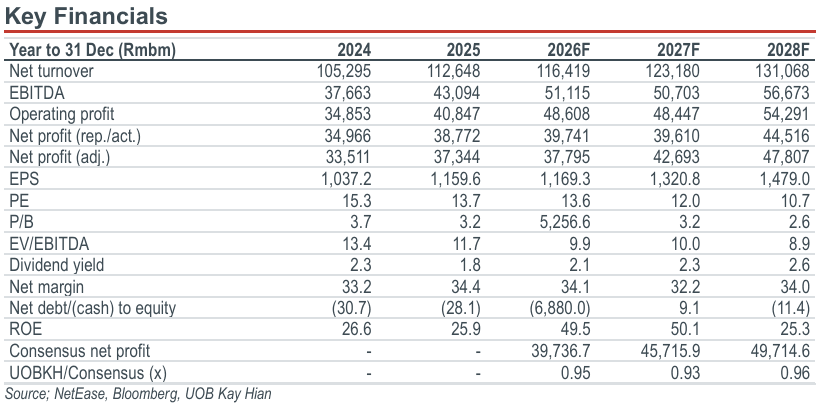
- Downgrade to HOLD with a lower target price of HK$173.00 (US$111.00).
Analysis
- Online games declined on self-developed titles; deferred revenue growth slowed. Games and related VAS revenue fell 1.7% yoy (2Q26: +9.7%) and 8.3% qoq to Rmb22.9b, 9.4% below our estimate, as certain self-developed titles softened. Sea of Remnants fell short of launch expectations due to complex gameplay. Where Winds Meet performed well in 3Q26 after NetEase addressed earlier feedback that its PC version needed more content. Segment gross margin rose 5.0ppt yoy to 74.3% (2Q26: 76.1%), lifting gross profit 5.4% yoy to Rmb17.1b. Deferred revenue rose 4.7% qoq to Rmb20.2b, though yoy growth slowed to 3.8% from 14% in 2Q26.
- Stable Cloud Music revenue, with Youdao revenue down despite margin expansion. Cloud Music revenue remained broadly flat, down 0.9% yoy (2Q26: +0.4%) to Rmb1.9b, 4.5% below our estimate. Gross margin for the segment rose 0.5ppt yoy to 35.9% (2Q26: 37.4%), with gross profit broadly stable at Rmb698m. Youdao revenue fell 12.3% yoy (2Q26: +3.5%) to Rmb1.4b, 16.4% below our estimate, mainly due to lower revenue from smart devices and online marketing services. Youdao’s gross margin expanded 1.3ppt yoy to 43.6% (2Q26: 48.9%), while gross profit fell 9.5% yoy to Rmb623m. In addition, revenue from innovative businesses and others rose 7.1% yoy to Rmb1.5b, 1.5% ahead of our estimate.
Highlights
- NetEase’s 3Q26 revenue and earnings missed expectations. Revenue fell 1.8% yoy to Rmb27.9b, 8-9% below our and consensus estimates, mainly due to weaker games revenue. Gross margin expanded 4.3ppt yoy to 68.4% on lower revenue-sharing costs. Non-GAAP net profit fell 3.6% yoy to Rmb9.2b, 10-11% below our and consensus estimates, weighed down by lower investment income and a higher effective tax rate.
- Downgrade to HOLD with a lower target price of HK$173.00 (US$111.00).
Analysis
- Online games declined on self-developed titles; deferred revenue growth slowed. Games and related VAS revenue fell 1.7% yoy (2Q26: +9.7%) and 8.3% qoq to Rmb22.9b, 9.4% below our estimate, as certain self-developed titles softened. Sea of Remnants fell short of launch expectations due to complex gameplay. Where Winds Meet performed well in 3Q26 after NetEase addressed earlier feedback that its PC version needed more content. Segment gross margin rose 5.0ppt yoy to 74.3% (2Q26: 76.1%), lifting gross profit 5.4% yoy to Rmb17.1b. Deferred revenue rose 4.7% qoq to Rmb20.2b, though yoy growth slowed to 3.8% from 14% in 2Q26.
- Stable Cloud Music revenue, with Youdao revenue down despite margin expansion. Cloud Music revenue remained broadly flat, down 0.9% yoy (2Q26: +0.4%) to Rmb1.9b, 4.5% below our estimate. Gross margin for the segment rose 0.5ppt yoy to 35.9% (2Q26: 37.4%), with gross profit broadly stable at Rmb698m. Youdao revenue fell 12.3% yoy (2Q26: +3.5%) to Rmb1.4b, 16.4% below our estimate, mainly due to lower revenue from smart devices and online marketing services. Youdao’s gross margin expanded 1.3ppt yoy to 43.6% (2Q26: 48.9%), while gross profit fell 9.5% yoy to Rmb623m. In addition, revenue from innovative businesses and others rose 7.1% yoy to Rmb1.5b, 1.5% ahead of our estimate.
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
HK$186.90
HK$173.00
-7.4%
HK$252.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

20 Nov 2026
Kuaishou Technology (1024 HK): 3Q26: Revenue Misses; 4Q26 Outlook Remains Challenging

18 Nov 2026
Tencent Music Entertainment Group (1698 HK): 3Q26: Revenue Misses But Earnings Hold Up

19 Nov 2026
Tencent Holdings (700 HK): 3Q26: Higher AI Costs Result In Operating Profit Miss and Weigh on FCF
Our latest research

20 Nov 2026
Alibaba Group (9988 HK): 2Q27: Cloud Revenue Beat; Margin Expansion; FCF Outflow Narrows
20 Nov 2026
TA: Semiconductor Manufacturing International (0981 HK) / Meituan (3690 HK)

20 Nov 2026