

Company Coverage
Kuaishou Technology (1024 HK): 3Q26: Revenue Misses; 4Q26 Outlook Remains Challenging
SELL (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
HK$23.04
HK$19.00
-17.5%
HK$35.00
Analyst
Analyst
Highlights
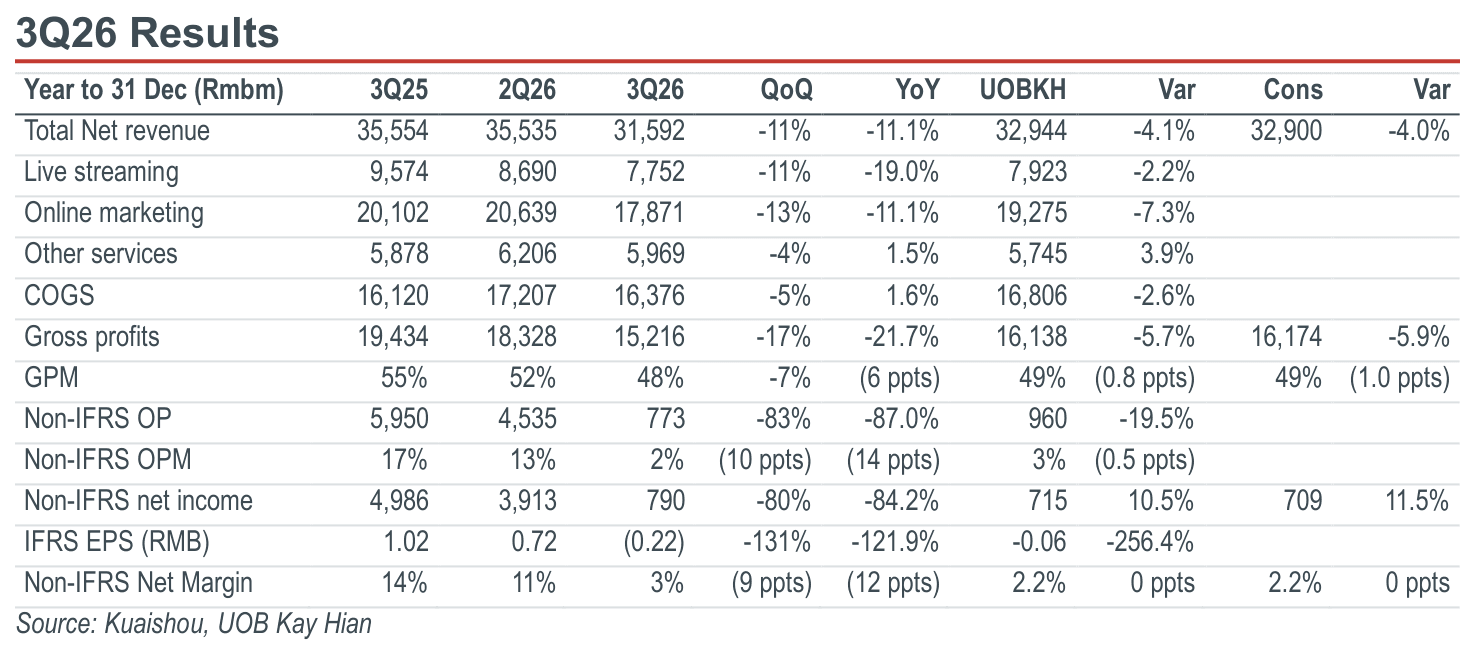
- Kuaishou’s 3Q26 revenue missed expectations, while earnings beat. Revenue fell 11.1% yoy to Rmb31.6b, around 4% below both our estimate and consensus, on weaker online marketing and live-streaming revenue. Gross margin contracted 6.5ppt yoy to 48.2%, reflecting higher revenue-sharing and bandwidth costs. Non-IFRS net profit fell 84.2% yoy to Rmb790m but exceeded both our estimate and consensus. Management expects revenue and margins to remain under pressure in 4Q26.
- Downgrade to SELL with a lower target price of HK$19.00.
Analysis
- Weak 3Q26 top-line performance. Kuaishou Technology’s (Kuaishou) online marketing revenue fell 11.1% yoy to Rmb17.9b in 3Q26 (2Q26: +4.4%), as intensifying e-commerce competition weighed on merchant ad spending. E-commerce GMV also declined yoy, reflecting cautious discretionary spending and lower subsidies on selected products. Higher compliance costs led merchants to tighten their advertising budgets and focus more on returns. Ad spending in the content consumption segment more than doubled yoy, supported by strong demand for AI-generated short dramas. Live-streaming revenue declined 19.0% yoy to Rmb7.8b (2Q26: -13.5%). Other services revenue grew 1.5% yoy to Rmb6.0b, as higher games and Kling AI revenue more than offset lower e-commerce revenue.
- Margin overview. Gross profit fell 21.7% yoy to Rmb15.2b in 3Q26, with gross profit margin down 6.5ppt yoy to 48.2%. Non-IFRS operating profit declined 87.0% yoy to Rmb773m, with margin down 14.3ppt yoy to 2.4%. R&D expenses rose 41.9% yoy on higher Kling AI investment, partly offset by a 9.0% yoy decline in selling and marketing expenses. Domestic operating profit fell 92.2% yoy to Rmb420m, while overseas operating loss narrowed to Rmb23m from Rmb25m in 2Q26 and Rmb64m in 3Q25.
Highlights
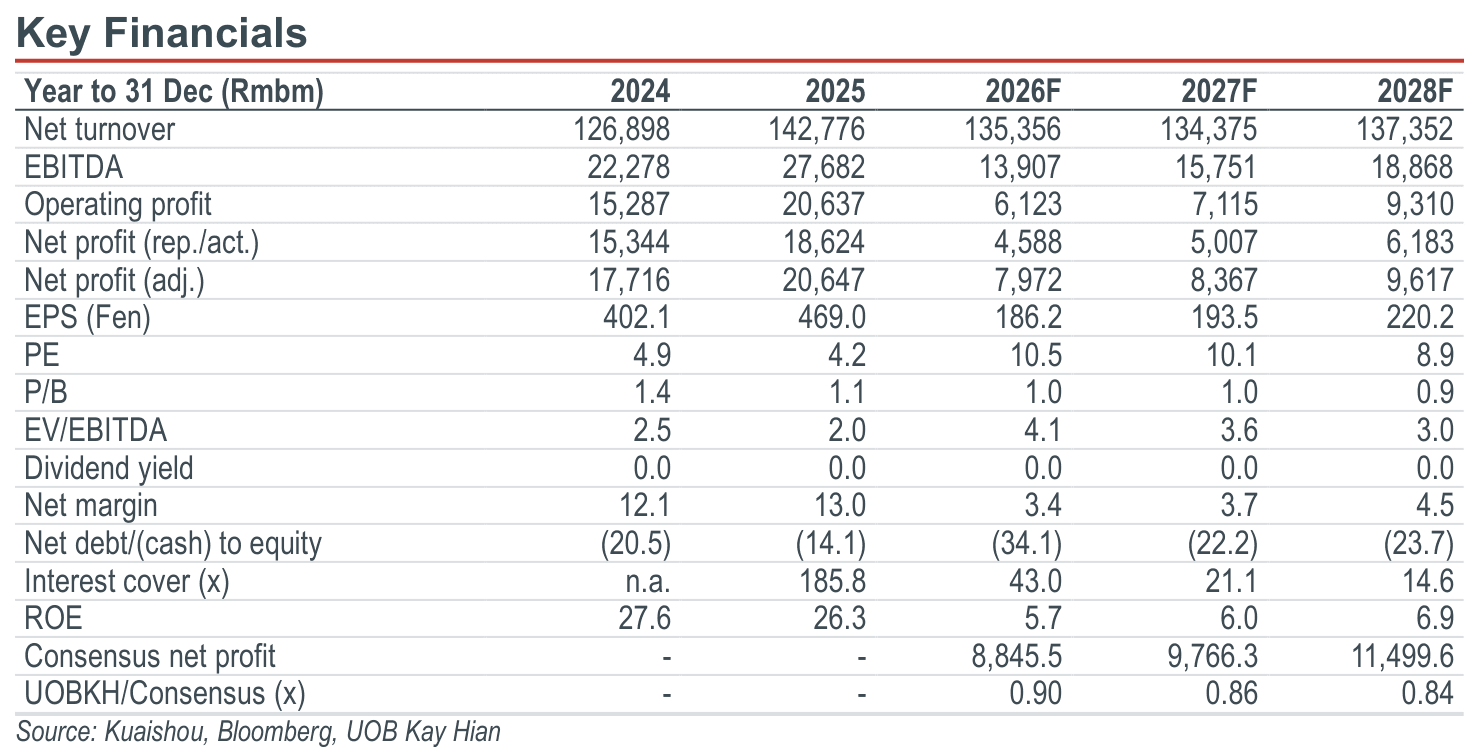
- Kuaishou’s 3Q26 revenue missed expectations, while earnings beat. Revenue fell 11.1% yoy to Rmb31.6b, around 4% below both our estimate and consensus, on weaker online marketing and live-streaming revenue. Gross margin contracted 6.5ppt yoy to 48.2%, reflecting higher revenue-sharing and bandwidth costs. Non-IFRS net profit fell 84.2% yoy to Rmb790m but exceeded both our estimate and consensus. Management expects revenue and margins to remain under pressure in 4Q26.
- Downgrade to SELL with a lower target price of HK$19.00.
Analysis
- Weak 3Q26 top-line performance. Kuaishou Technology’s (Kuaishou) online marketing revenue fell 11.1% yoy to Rmb17.9b in 3Q26 (2Q26: +4.4%), as intensifying e-commerce competition weighed on merchant ad spending. E-commerce GMV also declined yoy, reflecting cautious discretionary spending and lower subsidies on selected products. Higher compliance costs led merchants to tighten their advertising budgets and focus more on returns. Ad spending in the content consumption segment more than doubled yoy, supported by strong demand for AI-generated short dramas. Live-streaming revenue declined 19.0% yoy to Rmb7.8b (2Q26: -13.5%). Other services revenue grew 1.5% yoy to Rmb6.0b, as higher games and Kling AI revenue more than offset lower e-commerce revenue.
- Margin overview. Gross profit fell 21.7% yoy to Rmb15.2b in 3Q26, with gross profit margin down 6.5ppt yoy to 48.2%. Non-IFRS operating profit declined 87.0% yoy to Rmb773m, with margin down 14.3ppt yoy to 2.4%. R&D expenses rose 41.9% yoy on higher Kling AI investment, partly offset by a 9.0% yoy decline in selling and marketing expenses. Domestic operating profit fell 92.2% yoy to Rmb420m, while overseas operating loss narrowed to Rmb23m from Rmb25m in 2Q26 and Rmb64m in 3Q25.
SELL (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
HK$23.04
HK$19.00
-17.5%
HK$35.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

20 Nov 2026
NetEase (9999 HK): 3Q26: Revenue And Earnings Miss On Softer Games; Gross Margin Expands

18 Nov 2026
Tencent Music Entertainment Group (1698 HK): 3Q26: Revenue Misses But Earnings Hold Up

17 Nov 2026
KE Holdings Inc (2423 HK): 3Q26: Strong Earnings Beat On Margin Expansion And Lower Opex
Our latest research
20 Nov 2026
NetEase (9999 HK): 3Q26: Revenue And Earnings Miss On Softer Games; Gross Margin Expands

20 Nov 2026
Alibaba Group (9988 HK): 2Q27: Cloud Revenue Beat; Margin Expansion; FCF Outflow Narrows
20 Nov 2026