
Company Coverage
Hesai Group (2525 HK): 3Q26: Core Earnings Up 16% yoy; Robotics Products Ramping Up
BUY (Maintained)
Current price:
Target price:
Upside:
HK$15.07
HK$29.00
92.4%
Analyst
Highlights
- Hesai posted mixed 3Q26 results with the beats on LiDAR ASP and SGI revenue offsetting the LiDAR sales miss. Core earnings grew 16% yoy, with the SGI loss partly offsetting the core LiDAR business’ 88% EBIT growth.
- Forward earnings will be driven by the stabilisation of ADAS LiDAR prices, as well as robotics businesses. The company expects robotics businesses to contribute 50-60% of revenue in 2027, up from 40-50% in 2026.
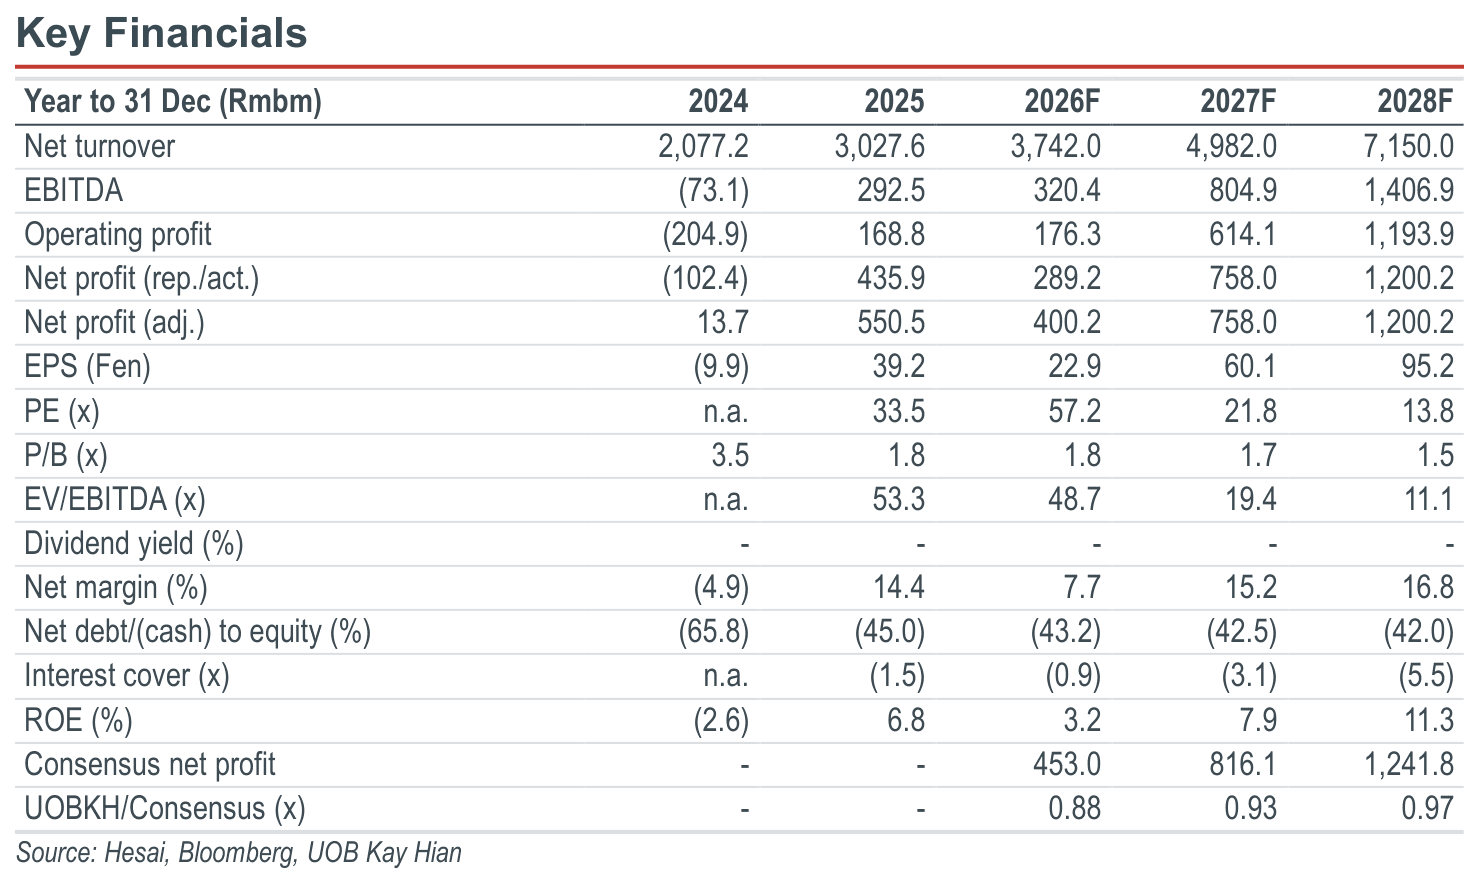
- We cut our 2026 GAAP net profit forecast by 28% to the bigger share-based payment and forex loss, and keep those for 2027-28 at Rmb758m/Rmb1.2b respectively. Maintain BUY. Target price: HK$29.00.
Analysis
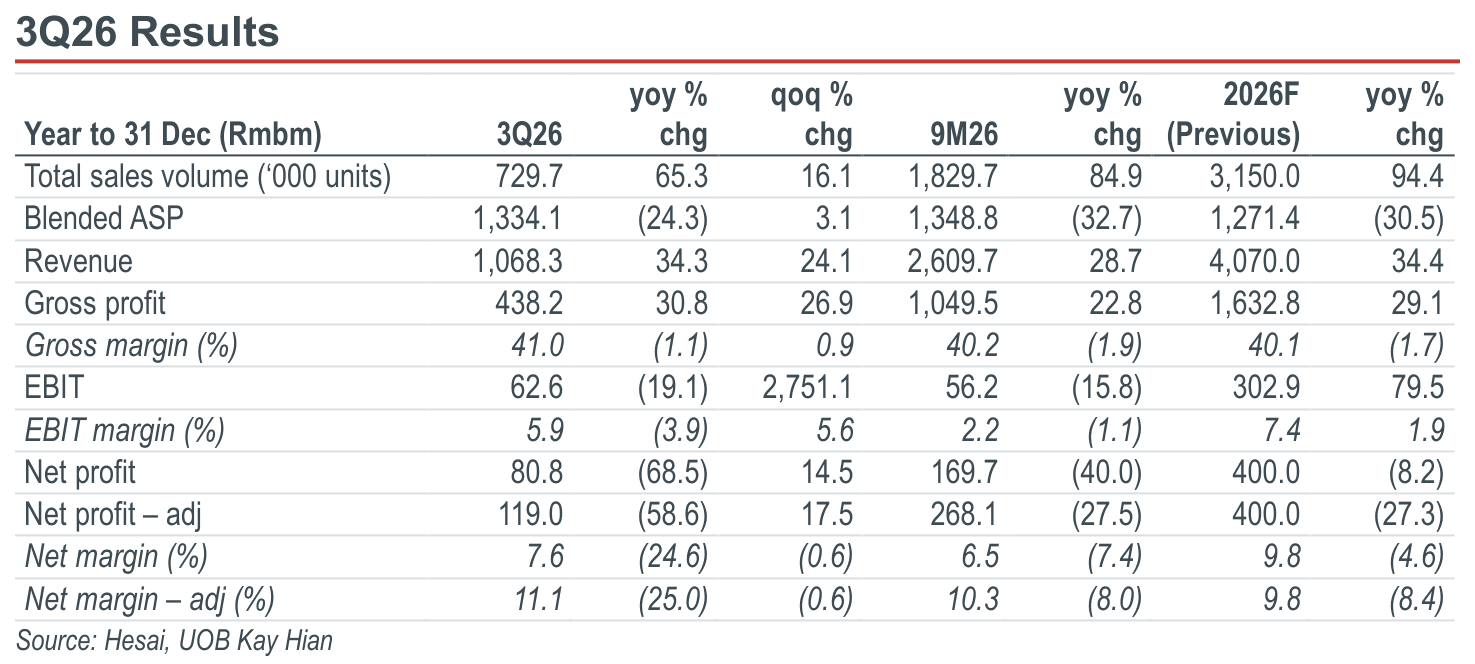
- Hesai Group (Hesai) reported mixed 3Q26 results, with the beats on LiDAR ASP and Strategic Growth Initiatives (SGI) revenue offsetting the LiDAR shipment miss. Overall, the continued profitable scaling in its core LiDAR business and strong SGI growth boosted core earnings by 16% yoy.
- LiDAR shipments reached 729,673 units (+65.3% yoy/+16% qoq), 7% below our forecast and 11% below consensus estimate, due to softer sequential robotics LiDAR shipments (91,600 units/+51.1% yoy/-35.6% qoq), especially the robotic lawn mower LiDARs.
- Blended ASP was Rmb1,340 (-26% yoy/+3% qoq), 15% above our estimate, due to the stabilisation of ADAS LiDAR prices and higher share of robotaxi LiDARs in sales mix.
- LiDAR shipments reached 729,673 units (+65.3% yoy/+16% qoq), 7% below our forecast and 11% below consensus estimate, due to softer sequential robotics LiDAR shipments (91,600 units/+51.1% yoy/-35.6% qoq), especially the robotic lawn mower LiDARs.
Highlights
- Hesai posted mixed 3Q26 results with the beats on LiDAR ASP and SGI revenue offsetting the LiDAR sales miss. Core earnings grew 16% yoy, with the SGI loss partly offsetting the core LiDAR business’ 88% EBIT growth.
- Forward earnings will be driven by the stabilisation of ADAS LiDAR prices, as well as robotics businesses. The company expects robotics businesses to contribute 50-60% of revenue in 2027, up from 40-50% in 2026.
- We cut our 2026 GAAP net profit forecast by 28% to the bigger share-based payment and forex loss, and keep those for 2027-28 at Rmb758m/Rmb1.2b respectively. Maintain BUY. Target price: HK$29.00.
Analysis
- Hesai Group (Hesai) reported mixed 3Q26 results, with the beats on LiDAR ASP and Strategic Growth Initiatives (SGI) revenue offsetting the LiDAR shipment miss. Overall, the continued profitable scaling in its core LiDAR business and strong SGI growth boosted core earnings by 16% yoy.
- LiDAR shipments reached 729,673 units (+65.3% yoy/+16% qoq), 7% below our forecast and 11% below consensus estimate, due to softer sequential robotics LiDAR shipments (91,600 units/+51.1% yoy/-35.6% qoq), especially the robotic lawn mower LiDARs.
- Blended ASP was Rmb1,340 (-26% yoy/+3% qoq), 15% above our estimate, due to the stabilisation of ADAS LiDAR prices and higher share of robotaxi LiDARs in sales mix.
- LiDAR shipments reached 729,673 units (+65.3% yoy/+16% qoq), 7% below our forecast and 11% below consensus estimate, due to softer sequential robotics LiDAR shipments (91,600 units/+51.1% yoy/-35.6% qoq), especially the robotic lawn mower LiDARs.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$15.07
HK$29.00
92.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

22 Oct 2026
Fuyao Glass (3606 HK): 3Q26: Earnings Dragged By Higher Sea Freight Costs And One-off Expenses; Cut Target Price To HK$77.00

27 Oct 2026
EVE Energy (300014 CH): 3Q26: Earnings Up 60% yoy/4.5% qoq, Missing Estimates; Cut Target Price To Rmb57.00

30 Oct 2026
Geely Auto (175 HK): 3Q26: Earnings Slightly Miss Our Estimates On Share-based Payments
Our latest research
12 Nov 2026
TA: CITIC (0267 HK) / Innovent Biologics (1801 HK)
11 Nov 2026
TA: China Tower (0788 HK) / Pop Mart International Group (9992 HK)

9 Nov 2026