
Company Coverage
FIT Hon Teng (6088 HK): 3Q26: Profitability Under Pressure; Significant 2026 Operating Profit Guidance Cut
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$2.91
HK$4.20
44.2%
HK$9.19
Analyst
Analyst
Highlights
FIT’s 3Q26 revenue grew 4.0% yoy to US$1,378m but operating profit declined 38.8% yoy to US$58m, impacted by higher material costs and slower-than-expected facility ramp-up. 9M26 revenue and net profit represented 69% and 32% of our full-year estimates respectively.
Management guided down consumer interconnect revenue to a mid-20s percentage decline and cut its 2026 operating profit guidance from 70% yoy growth to flattish growth due to continued margin pressure and production ramp-up. It targets 2027 operating profit to grow faster than revenue, with official guidance to be announced in Mar 27.
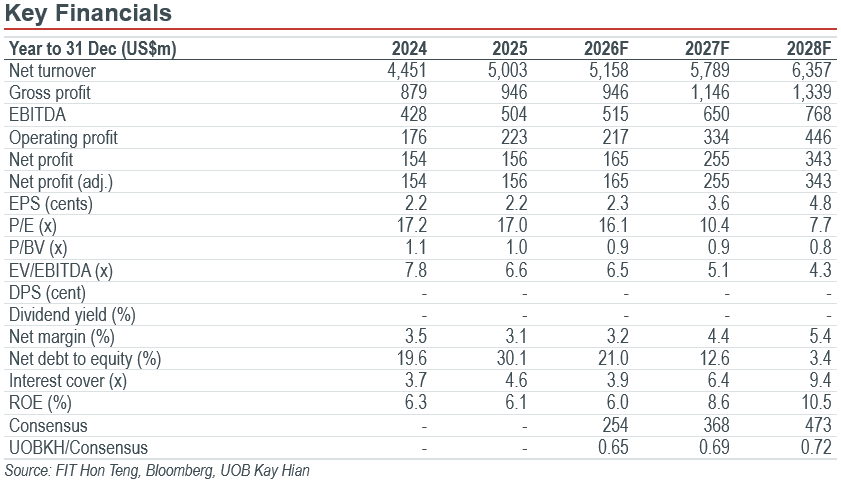
Maintain BUY but lower our target price from HK$9.19 to HK$4.20, based on a lower 2027F PE of 15.0x and lower earnings estimates. FIT trades at 10.4x 2027F PE, vs its 2021–26 historical mean of 15.1x.
Analysis
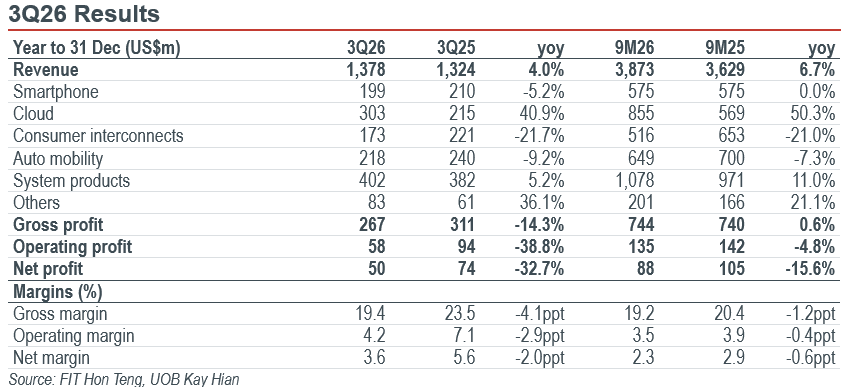
3Q26 results. FIT Hon Teng’s (FIT) 3Q26 revenue grew 4.0% yoy to US$1,378m, bringing 9M26 revenue to US$3,873m, or 68.5% of our full-year revenue estimate. Gross profit fell 14.3% yoy to US$267m in 3Q26, with gross margin narrowing 4.1ppt yoy to 19.4%. 3Q26 operating profit declined 38.8% yoy to US$58m, impacted by higher material costs, slower-than-expected facility ramp-up (particularly in Vietnam) and lower-than-expected cloud revenue. Stripping out the negative forex impact, 9M26 operating profit would have grown approximately 31% yoy.
Highlights
FIT’s 3Q26 revenue grew 4.0% yoy to US$1,378m but operating profit declined 38.8% yoy to US$58m, impacted by higher material costs and slower-than-expected facility ramp-up. 9M26 revenue and net profit represented 69% and 32% of our full-year estimates respectively.
Management guided down consumer interconnect revenue to a mid-20s percentage decline and cut its 2026 operating profit guidance from 70% yoy growth to flattish growth due to continued margin pressure and production ramp-up. It targets 2027 operating profit to grow faster than revenue, with official guidance to be announced in Mar 27.
Maintain BUY but lower our target price from HK$9.19 to HK$4.20, based on a lower 2027F PE of 15.0x and lower earnings estimates. FIT trades at 10.4x 2027F PE, vs its 2021–26 historical mean of 15.1x.
Analysis
3Q26 results. FIT Hon Teng’s (FIT) 3Q26 revenue grew 4.0% yoy to US$1,378m, bringing 9M26 revenue to US$3,873m, or 68.5% of our full-year revenue estimate. Gross profit fell 14.3% yoy to US$267m in 3Q26, with gross margin narrowing 4.1ppt yoy to 19.4%. 3Q26 operating profit declined 38.8% yoy to US$58m, impacted by higher material costs, slower-than-expected facility ramp-up (particularly in Vietnam) and lower-than-expected cloud revenue. Stripping out the negative forex impact, 9M26 operating profit would have grown approximately 31% yoy.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$2.91
HK$4.20
44.2%
HK$9.19
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Shenzhen Mindray Bio-Medical Electronics (300760 CH) - 9M26: Results In Line; Overseas And Emerging Businesses To Continue Driving Growth In 2027

6 Nov 2026
BeOne Medicines (6160 HK) - 3Q26: Results Outperform; Raising 2026 Guidance Again

2 Nov 2026
Inner Mongolia Yili Industrial Group (600887 CH) - 3Q26: Revenue Misses But Operating Margin Expansion Continues; Reiterates MSD Revenue Growth Target For 2026
Our latest research

9 Nov 2026
Galaxy Entertainment Group (27 HK): 3Q26: Market Share Gains; Normalised EBITDA Down 9% qoq On Margin Pressure

9 Nov 2026
WuXi AppTec (2359 HK): Enabling AIDD And AI4S Through Operational Excellence
6 Nov 2026