Company Coverage
CR Mixc Lifestyle (1209 HK): 3Q26 Operational Update: Double-digit Earnings Growth In Line With Expectations; New Mall Openings On Track
BUY (Maintained)
Current price:
Target price:
Upside:
HK$39.10
HK$55.00
+40.7%
Analyst
Analyst
Highlights
- We expect CR Mixc to achieve its 2026 target of double-digit core net profit growth, with the commercial segment remaining the main driver of growth and margin.
- We expect mall tenant sales to grow by double digits yoy in 9M26 (same-store: mid-single-digits), slower than in 1H26, with tenant sales performing better during the National Day holidays than in Sep 26. We expect 12 mall openings and around 20 new mall signings in 2026.
- We expect the full-year OCF/core net profit ratio to stay above 1.0x and the 100% payout to hold. Maintain BUY, target price: HK$55.00.
Analysis
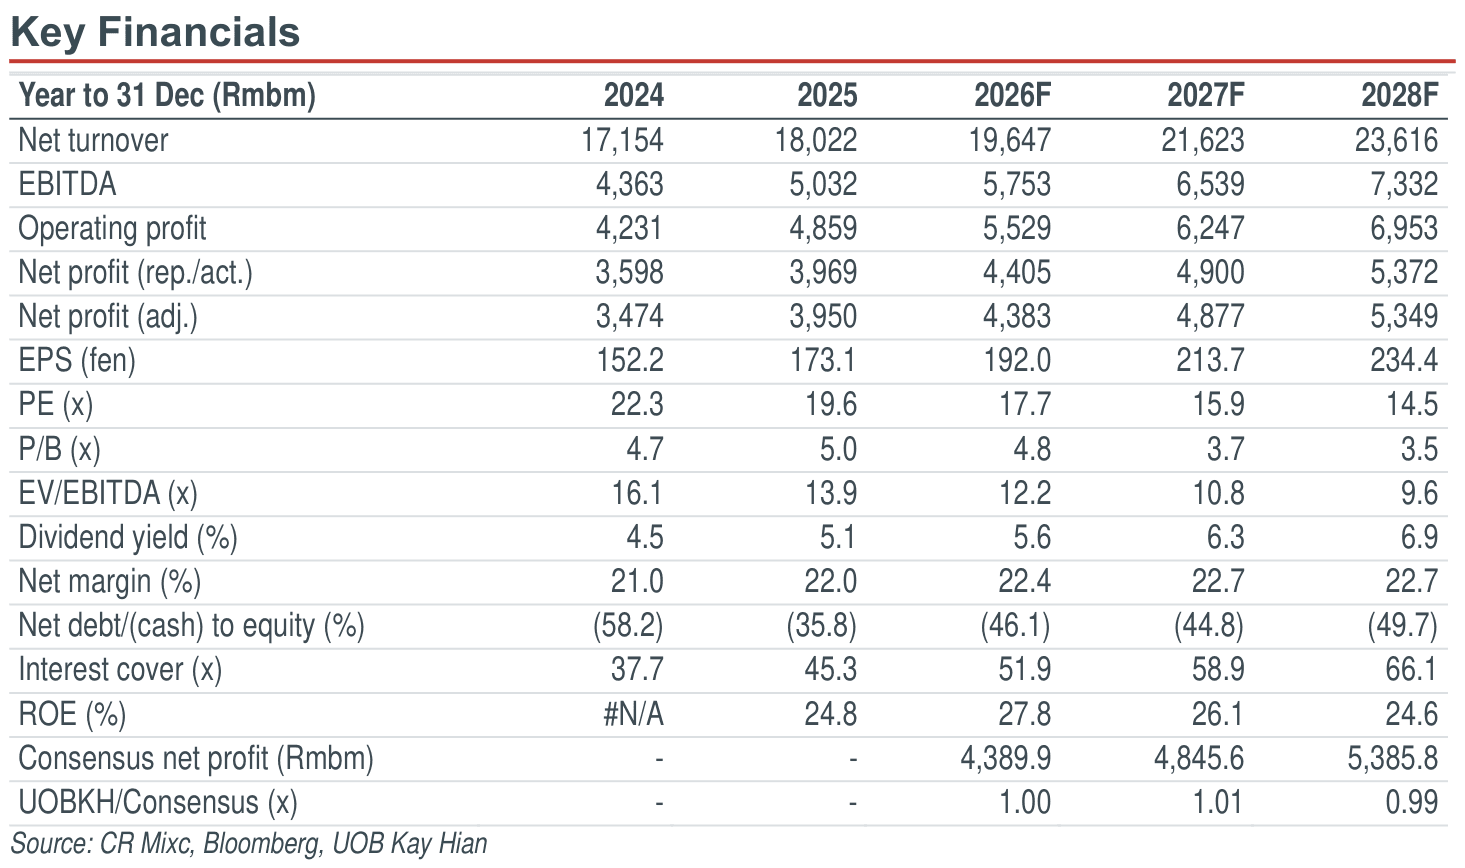
- 3Q26 on track with double-digit profit growth intact. We expect China Resources Mixc Lifestyle Services (CR Mixc) to achieve its 2026 target of double-digit core net profit growth, in line with our forecast of 11.0% yoy growth to Rmb4.38b; 1H26 core net profit already accounted for 50.9% of our full-year estimate. Overall, the property management segment is expected to provide stable revenue growth, and the commercial business should remain the main growth and margin driver, supported by mall openings in 4Q26.
- Shopping mall business remained resilient. We expect total retail sales across CR Mixc malls to have grown by double-digits yoy in 9M26, with same-store sales (SSS) up by mid-single-digits (1H26: +10.2%) and luxury malls outperforming the overall portfolio. We estimate growth eased gradually from a strong 1Q26; in Sep 26 alone, overall retail sales grew by high single-digits yoy while SSS was flat. For the 2026 National Day holiday, we expect total retail sales to have grown by double-digits with mid-single-digit SSS growth, better than Sep 26, although luxury malls lagged the portfolio. We expect CR Mixc to maintain double-digit retail sales growth for the full year.
- Mall openings and expansion on track. We estimate that five new malls opened in 3Q26, taking the total to seven by end-Sep 26 and leaving five for 4Q26 to reach 12 openings in 2026. On mall expansion, we estimate it secured nine third-party projects and eight from parent CR Land in 9M26, mostly in Tier 1 and Tier 2 cities such as Beijing and Shenzhen.
Highlights
- We expect CR Mixc to achieve its 2026 target of double-digit core net profit growth, with the commercial segment remaining the main driver of growth and margin.
- We expect mall tenant sales to grow by double digits yoy in 9M26 (same-store: mid-single-digits), slower than in 1H26, with tenant sales performing better during the National Day holidays than in Sep 26. We expect 12 mall openings and around 20 new mall signings in 2026.
- We expect the full-year OCF/core net profit ratio to stay above 1.0x and the 100% payout to hold. Maintain BUY, target price: HK$55.00.
Analysis
- 3Q26 on track with double-digit profit growth intact. We expect China Resources Mixc Lifestyle Services (CR Mixc) to achieve its 2026 target of double-digit core net profit growth, in line with our forecast of 11.0% yoy growth to Rmb4.38b; 1H26 core net profit already accounted for 50.9% of our full-year estimate. Overall, the property management segment is expected to provide stable revenue growth, and the commercial business should remain the main growth and margin driver, supported by mall openings in 4Q26.
- Shopping mall business remained resilient. We expect total retail sales across CR Mixc malls to have grown by double-digits yoy in 9M26, with same-store sales (SSS) up by mid-single-digits (1H26: +10.2%) and luxury malls outperforming the overall portfolio. We estimate growth eased gradually from a strong 1Q26; in Sep 26 alone, overall retail sales grew by high single-digits yoy while SSS was flat. For the 2026 National Day holiday, we expect total retail sales to have grown by double-digits with mid-single-digit SSS growth, better than Sep 26, although luxury malls lagged the portfolio. We expect CR Mixc to maintain double-digit retail sales growth for the full year.
- Mall openings and expansion on track. We estimate that five new malls opened in 3Q26, taking the total to seven by end-Sep 26 and leaving five for 4Q26 to reach 12 openings in 2026. On mall expansion, we estimate it secured nine third-party projects and eight from parent CR Land in 9M26, mostly in Tier 1 and Tier 2 cities such as Beijing and Shenzhen.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$39.10
HK$55.00
+40.7%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

21 Sept 2026
Alibaba Health Information Technology (241 HK): 1HFY27 Preview: Lowers FY27 Revenue Growth Target To 7-10% yoy On Subsidy Optimisation; Earnings Guidance Unchanged

8 Oct 2026
Geely Auto (175 HK): Exports And New Technologies Offset Weak Domestic Sales
Our latest research
21 Oct 2026
TA: CK Asset (1113 HK) / Nongfu Spring (9633 HK)

21 Oct 2026
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow

21 Oct 2026