

Country Daily
Momenta Global / Budweiser APAC / BYD Electronics / Foxconn Industrial Internet / Geely Auto / Haier Smart Home / Midea Group / NAURA Technology / New Oriental Education / Zhejiang Sanhua Intelligent Controls
Analyst
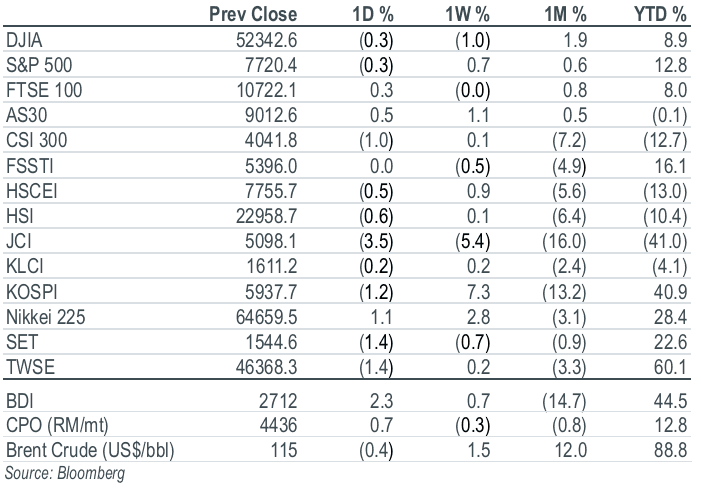
Key Indices
Top Stories
Initiate Coverage | Momenta Global (6880 HK/BUY/HK$146.00/Target: HK$270.00)
Initiate coverage on Momenta with BUY and a target price of HK$270.00. Momenta is the largest independent provider of driving-automation software globally, with a data flywheel of more than 1m vehicles returning about 630,000 clips a day.
Company Results | Budweiser APAC (1876 HK/BUY/HK$5.81/Target: HK$8.30)
Bud APAC’s 3Q26 revenue was in line but EBITDA missed. Management reiterated that China’s near-term priority is to stabilise volume and market share, while continuing to step up commercial investments. In addition, management does not expect any further meaningful one-off impacts related to India’s provision. On shareholder returns, management states that if business performance continues to face pressure and does not improve, maintaining the current dividend level could become increasingly challenging. Maintain BUY; cut target price by 11% to HK$8.30.
Company Results | BYD Electronics (285 HK/SELL/HK$22.24/Target: HK$14.50)
BYDE reported weak results again. Revenue of Rmb45b was in line, but margins missed consensus as consumer devices continued to drag profitability. Bottom line registered a 35% sequential recovery at Rmb537m but still missed consensus expectation by 18%. Management sees strong opportunities in its AI infrastructure-related business and expects robust growth through 2027, but the consumer electronic business seems to have more downside going forward. Maintain SELL; keep target price unchanged at HK$14.50.
Company Results | Foxconn Industrial Internet (601138 CH/BUY/Rmb45.22/Target: Rmb77.60)
FII’s 3Q26 top- and bottom line results beat consensus estimates by 6.6% and 1.8% respectively, driven by sustained AI computing demand and rising customer share. Cloud-computing and networking revenue maintained strong growth, supported by accelerating AI server and high-speed switch shipments. We raise our 2026-28 net profit forecasts by 1.0%/9.4%/10.5% respectively. Maintain BUY with a target price of Rmb77.60.
Company Results | Geely Auto (175 HK/BUY/HK$13.57/Target: HK$21.00)
3Q26 adjusted net profit of Rmb5.2b (+31.6% yoy/+1.7% qoq) met consensus forecast but slightly missed our estimate, due to share-based payment. Forward earnings growth will be driven by new techs, strong product line-ups, overseas expansion and premiumisation. We cut our 2026-28 net profit forecasts by 11%/2%/2% respectively to factor in forex loss and share-based payments. Maintain BUY on Geely and cut target price from HK$29.00 to HK$21.00.
Company Results | Haier Smart Home (6690 HK/BUY/HK$18.94/Target: HK$26.00)
Haier’s 3Q26 net profit declined 12% yoy. Domestic revenue declined double-digits, dragged by air conditioners, while overseas revenue remained flat. For 4Q26, management targets a return to domestic revenue growth. Regarding margins, raw material cost pressure is expected to persist. Management also indicated that an additional US tariff refund may be recognised in 4Q26 or next year, which could partially offset the ongoing costs from supply-chain restructuring in 4Q26. Maintain BUY; cut target price by 8% to HK$26.00.
Company Results | Midea Group (000333 CH/BUY/Rmb87.48/Target: Rmb116.80)
Midea’s 3Q26 EBIT declined 3% yoy, and reported net profit rose 26% yoy. Excluding investment gains, we estimate the recurring net profit would have declined 11%. In 3Q26, ToC revenue declined by high single digits yoy, with domestic sales down by more than 15%, partially offset by mid-single-digit growth in overseas sales. ToB revenue grew by high single digits. Looking ahead to 4Q26, management targets positive sales growth. Maintain BUY; raise target price by 4% to Rmb116.80.
Company Results | NAURA Technology Group (002371 CH/BUY/Rmb497.30/Target: Rmb783.20)
NAURA’s 3Q26 results were weaker than expected, with revenue growing only 1.3% yoy to Rmb11.3b, gross margin declining 2.0ppt yoy and net profit rising 5% yoy to Rmb2.0b. The miss was due to component shortages in 3Q26 which had pushed order deliveries to 4Q26. Thus, management kept its full-year revenue target of Rmb49b unchanged, implying a meaningful improvement in supply constraint in the near future. Maintain BUY but cut target price to Rmb783.20 to factor in the mounting macro-related risk.
Company Results | New Oriental Education (EDU US/BUY/US$50.72/Target: US$64.00)
EDU’s 1QFY27 results were broadly in line with expectations, with margins slightly below consensus. Revenue grew 23% yoy to US$1,874.5m, while non-GAAP net profit rose 16.5% yoy to US$301m, both broadly in line with our and consensus estimates. Non-GAAP net margin narrowed by approximately 1ppt yoy to 16%. EDU reiterated its FY27 revenue guidance of US$6,453.9m-6,680.3m, representing an intact 14-18% yoy growth, in line with consensus’ forecasts. Maintain BUY with a lower target price of US$64.00 (HK$50.00).
Company Results | Zhejiang Sanhua Intelligent Controls Co (002050 CH/BUY/Rmb36.82/Target: Rmb41.00)
3Q26 core net profit missed estimates at Rmb1,094m (+2% yoy/-14.9% qoq). The miss stems from revenue and opex hikes. Liquid cooling anchors growth through 2028, with robotics contributing from 2027, refrigeration expanding on overseas demand and auto on integration. Cut 2026-28 net profit forecasts by 9%/4%/6% Maintain BUY and cut the target prices for A-share/H-share to Rmb41.00/HK$48.00.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


Our latest research

29 Oct 2026
ASMPT / CSPC Innovation Pharmaceutical / Ningbo Joyson Electronic Corporation / Tsingtao Brewery / Tencent Holdings

28 Oct 2026
Huizhou Desay SV / Inovance Technology / Shuanghuan Driveline / Wuliangye Yibin / WuXi AppTec

27 Oct 2026