

Country Daily
Huizhou Desay SV / Inovance Technology / Shuanghuan Driveline / Wuliangye Yibin / WuXi AppTec
Analyst
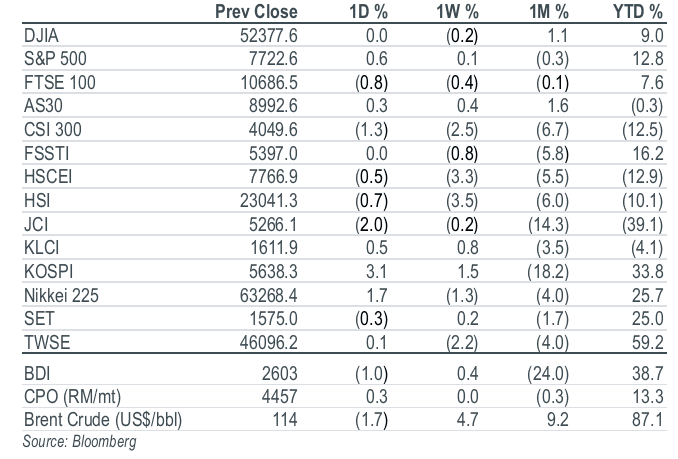
Key Indices
Top Stories
Company Results | Huizhou Desay SV (002920 CH/BUY/Rmb77.42/Target: Rmb105.00)
3Q26 net profit missed estimates at Rmb591m (+4.5% yoy, -24.6% qoq), as subsidy cuts, credit provisions, associate losses and a tax hike offset a 24% revenue beat. Forward earnings should be driven by new smart-driving programmes, overseas growth and customer diversification. We trim our 2026 net profit forecast by 1% to Rmb2.54b and raise our 2027-28 forecasts by 3%/8% to Rmb2.88b/Rmb3.41b. Maintain BUY on Huizhou Desay SV and cut target price from Rmb135.00 to Rmb105.00.
Company Results | Inovance Technology (300124 CH/BUY/Rmb53.31/Target: Rmb75.00)
Inovance’s 3Q26 results were mixed. Revenue was in line, rising 19% yoy to Rmb13.3b, but gross margin missed expectations and plunged 2.1ppt yoy to 25.5% due to costs hikes. Reported net profit was boosted by a Rmb419m fair value gain and increased 23.6% yoy to Rmb1.6b, but if we strip that out, core net profit would have declined 5% yoy to Rmb1.2b which is a 17% miss vs consensus. Going forward, top-line growth remains intact and margins are guided to recover as Inovance passes down cost hikes to its clients. Maintain BUY, cut target price to Rmb75.00.
Company Results | Shuanghuan Driveline (002472 CH/BUY/Rmb41.41/Target: Rmb52.00)
Shuanghuan's 3Q26 results were broadly in line. Revenue grew 14% yoy and 4% qoq, and gross margin recovered 0.7ppt qoq to 26.8%, while higher opex held net profit growth to 4% yoy and 10% qoq to Rmb333m. NEV gears and intelligent actuators remained the key growth driver with revenue growing 26%/31% yoy respectively. Going forward, growth is expected to be driven by overseas orders through its Hungary/Vietnam plant as well as export orders, while the accelerating penetration of coaxial reducers should provide a meaningful boost to product mix from 2027 onwards. Maintain BUY and raise target price to Rmb52.00.
Company Results | Wuliangye Yibin (000858 CH/SELL/Rmb75.38/Target: Rmb64.20)
Wuliangye’s 3Q26 revenue fell 38% yoy and net profit dropped 48% yoy, despite a revised base, primarily due to weaker-than-expected demand and elevated selling expenses. Cash inflow from sales of goods also worsened, reaching Rmb7.2b, up 1% yoy but down 41% qoq, and contract liabilities fell 4% yoy to Rmb8.9b. Cut target price by 18% to Rmb64.20; downgrade to SELL.
Company Results | WuXi AppTec (2359 HK/BUY/HK$185.60/Target: HK$220.00)
WuXi AppTec delivered strong 9M26 results, with total revenue and adjusted net profit expanding 38.6% yoy and 74.4% yoy respectively, beating market estimates and its growth guidance. Its backlog for continuing operations increased 36.4% yoy to Rmb76.7b at end-Sep 26. The company has raised its 2026 revenue target further from Rmb58.5b-60.5b to Rmb61.0b-61.9b, with continuing operations revenue growing 40-42% yoy (vs 35-39% previously). Maintain BUY and target price of HK$220.00.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


