

Country Daily
China Property Sector / EVE Energy / ZTE Corporation / Li Ning
Analyst
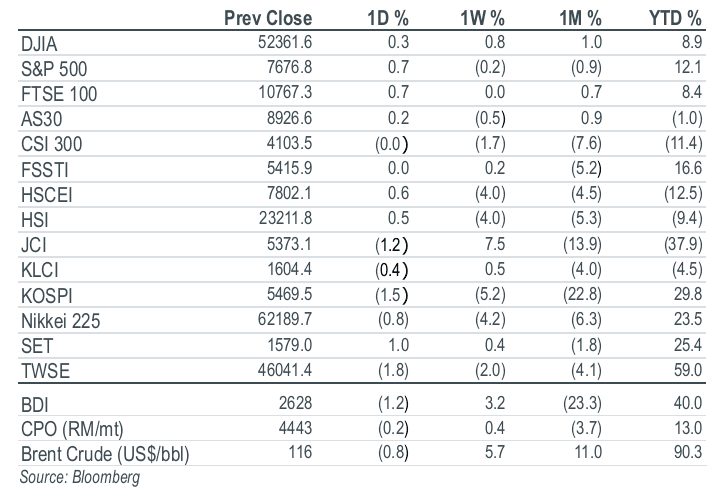
Key Indices
Top Stories
Sector Update | China Property
Supply continued to contract: Land sales revenue decreased 27.9% yoy in 9M26, with the decline narrowing gradually, and Tier 1 inventory months fell further in Oct 26, led by Beijing. Demand keeps diverging, with Tier 1 ahead of Tier 2 and second-hand ahead of new homes: Over 1-25 Oct 26, Tier 1 new-home/second-hand sales rose 2%/22% yoy respectively, while Tier 2 fell 23%/1%. ICE listing prices dropped 0.6% mom, suggesting more policy support is needed. Maintain UNDERWEIGHT on property sector.
Company Results | EVE Energy (300014 CH/BUY/Rmb47.21/Target: Rmb57.00)
3Q26 net profit missed our estimate at Rmb1,939m (+60.2% yoy/+4.5% qoq), due to subsidy cuts, tax hikes, and R&D costs. Forward revenue will be driven by a strong orderbook, but tax hikes will cap margins, and the inventory build-up amid a slump in lithium carbonate prices will probably lead to inventory provisions. We cut our 2026-28 net profit forecasts by 7%/17%/6% respectively. Maintain BUY and cut target price from Rmb85.00 to Rmb57.00.
Company Results | ZTE Corporation (763 HK/HOLD/HK$19.10/Target: HK$19.20)
3Q26 revenue beat consensus, but weak gross margin and higher-than-expected operating expenses weighed on operating profit. Growth should remain flattish in 4Q26 and moderate in 2027, as sluggish domestic telco demand offsets overseas growth. We cut 2026-28 earnings, maintain HOLD on ZTE and lower our target price to HK$19.20.
Company Update | Li Ning (2331 HK/BUY/HK$12.84/Target: HK$19.50)
Li Ning’s low single-digit retail sell-through decline in 3Q26 was below management’s expectations. For 4Q26, management highlights weather conditions and 11.11 as the key swing factors. However, with its full-year targets already incorporating a cautious view, management maintained its guidance. For Curry, management expects the full product portfolio to be rolled out after 4Q27. A board meeting will be held on 5 November to consider a special dividend. Maintain BUY but cut target price by 11% to HK$19.50.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


