Country Daily
Contemporary Amperex Technology Co / Fuyao Glass / Anta Sports
Analyst
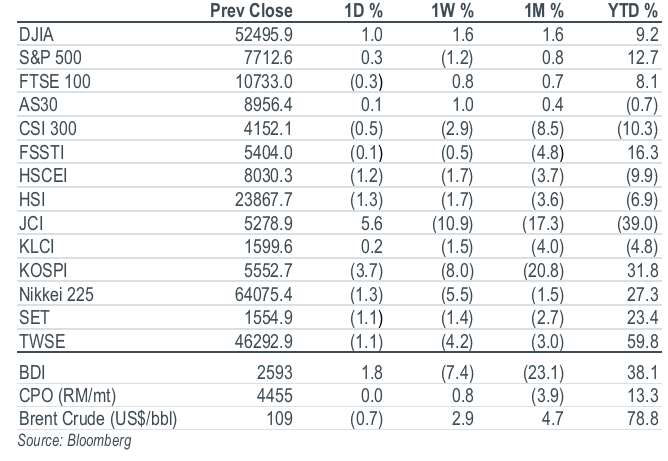
Key Indices
Top Stories
Company Results | Contemporary Amperex Technology Co (300750 CH/BUY/Rmb227.90/Target: Rmb343.00)
3Q26 net profit missed expectations at Rmb21.25b (+14.5% yoy/-5.8% qoq), as CATL absorbed export VAT hikes and the 2% consumption tax without passing them on. We expect a margin recovery as some tax costs are passed through via higher battery prices, though 2027 tax concession rollbacks remain a drag. We cut our 2026-28 net profit forecasts by 5%/10%/16% to Rmb89.1b/Rmb104.9b/Rmb116.4b respectively. Maintain BUY; cut target prices for A-share/H-share from Rmb585/HK$675 to Rmb343/HK$400.
Company Results | Fuyao Glass (3606 HK/BUY/HK$51.75/Target: HK$77.00)
3Q26 earnings were dragged by higher sea freight costs and one-off expenses. We expect margins to recover modestly in 4Q26 on easing sea freight costs, flat soda ash prices, and the absence of one-off costs. Sales volume and ASP will be driven by the accelerating industry consolidation, and vehicle intelligentisation overseas. We trim our 2026-28 net profit forecasts by 11%/8%/8% to Rmb8.58b/Rmb10.73b/Rmb12.12b respectively on lower margins. Maintain BUY on FYG and cut target price from HK$84.00 to HK$77.00.
Company Update | Anta Sports (2020 HK/BUY/HK$75.45/Target: HK$112.20)
Anta’s 3Q26 retail sales softened, with the Anta brand and Fila recording declines, while other brands maintained 25-30% growth. Supported by a solid start to 4Q26 during the Golden Week, management is confident about achieving full-year retail sales and operating margin targets, although government subsidies remain a swing factor for the Anta brand’s margin. For Puma, management will focus on China first, with Jack Wolfskin’s new stores tracking in line. Maintain BUY with an unchanged target price of HK$112.20.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


