

Country Daily
Lens Technology Xtep International Holdings
Analyst
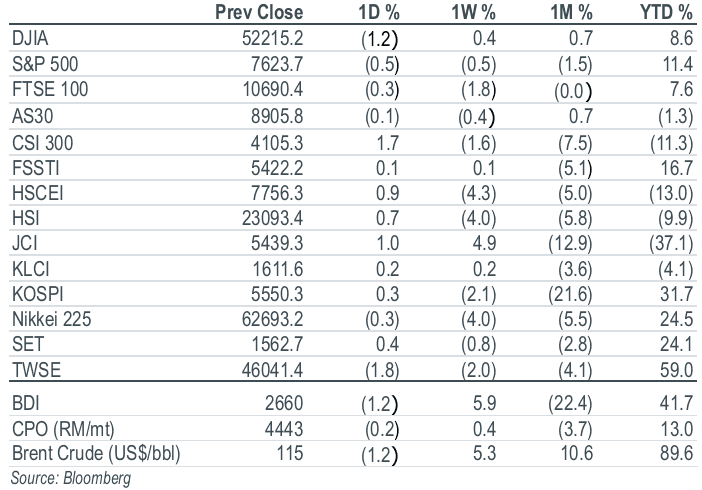
Key Indices
Top Stories
Company Results | Lens Technology (6613 HK/BUY/HK$16.39/Target: HK$21.50)
Lens Tech’s 3Q26 results came in below expectations, primarily due to: a) deliveries that were below its seasonal high to its large client as orders were pushed into 4Q; and b) a meaningful forex loss and elevated operating expenses. Earnings growth should improve meaningfully in 4Q26-1Q27, due to the aforementioned delayed delivery to the large client, stronger orders, and a contribution from new initiatives. Maintain BUY but slash the target prices of Lens A to Rmb32.10 and Lens H to HK$21.50.
Company Update | Xtep International Holdings (1368 HK/BUY/HK$3.67/Target: HK$5.40)
In 3Q26, the core Xtep brand’s offline sell-through remained under pressure while the e-commerce and kids businesses stayed relatively steady. Saucony’s sell-through picked up driven by its premiumisation strategy and category expansion. Management reiterated its full-year guidance for a low single-digit decline in group revenue, with Saucony and Merrell expected to deliver around 10% revenue growth, alongside a high single-digit net margin. Management also expects full-year gross margin to improve yoy. Maintain BUY. Cut target price by 4% to HK$5.40.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.

Our latest research

23 Oct 2026
China Automobile Weekly / Han’s Laser / Ping An Healthcare and Technology Company

22 Oct 2026
Contemporary Amperex Technology Co / Fuyao Glass / Anta Sports

21 Oct 2026