Country Daily
Greater China Small-Mid Cap Monthly / iFlytek Inc / Alibaba Group / CR Mixc Lifestyle / Lenovo Group
Analyst
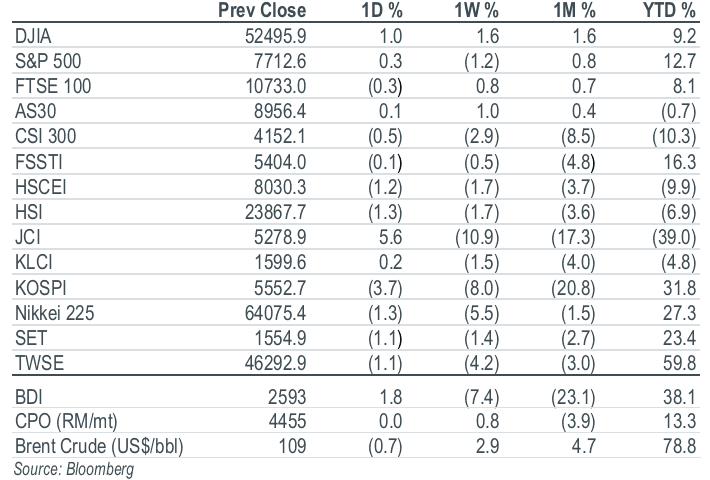
Key Indices
Top Stories
Strategy | BUY Karrie On 1HFY27 Optimism
Karrie's share price has corrected by about 40% from its previous peak in June mainly due to weakening market sentiment on AI-related stocks. Shipments of server enclosure products for the ASIC customer and Nvidia remain on track, with positive progress of customer qualification with two additional CSPs supporting near- to medium-term growth. We believe its current valuation at 8.0x FY27F PE and a 3.7% FY27F dividend yield are attractive and expect its 1HFY27 results to be announced in end-Nov 26 as a near-term catalyst.
Company Results | iFlytek Inc (002230 CH/SELL/Rmb36.12/Target: Rmb30.00)
iFLYTEK’s 3Q26 revenue missed expectations, rising 8.0% yoy to Rmb6.56b amid its ongoing business refocus. Gross margin eased 0.4ppt yoy to 40.0%. Attributable net profit rose 31.0% yoy to Rmb226m, supported by non-recurring investment gains and government grants, while net loss excluding non-recurring items reached Rmb126m as elevated R&D and selling expenses weighed on profitability. Cash collection improved, with further Spark upgrades scheduled for 22 October. Downgrade to SELL with a lower target price of Rmb30.00.
Company Update | Alibaba Group (9988 HK/BUY/HK$108.80/Target: HK$189.00)
Alibaba will report its 2QFY27 results in late-November, with revenue guided to grow 9% yoy to Rmb270b, slightly below our estimates. Adjusted EBITA should reach Rmb29b, above our Rmb22b forecast, supported by improving cloud profitability and narrowing instant retail and AI Labs and Applications losses. Cloud revenue growth should exceed 50% yoy, with EBITA margin reaching 12%, driven by a higher MaaS contribution and T-Head cost efficiencies. Maintain BUY with a higher target price of HK$189.00 (US$194.00).
Company Update | CR Mixc Lifestyle (1209 HK/BUY/HK$39.10/Target: HK$55.00)
We expect CR Mixc to deliver its 2026 target of double-digit core net profit growth. We estimate tenant sales across its malls to grow by double digits yoy in 9M26 (same-store: mid-single digits), with luxury malls outperforming. We expect seven new malls to have opened by end-Sep 26 and five more in 4Q26, and the full-year OCF/core net profit ratio to stay above 1.0x. We retain our 2026-28 forecasts. Maintain BUY with an unchanged target price of HK$55.00.
Company Update | Lenovo Group (992 HK/BUY/HK$25.26/Target: HK$49.00)
Lenovo will report its 2QFY27 results on 19 November. We expect revenue to grow 33% yoy to US$27b, adjusted operating margin to expand 3.0ppt yoy to 6.7%, and adjusted net profit to surge 88% yoy to US$1,226m. This is driven by the ISG business’ robust growth and margin expansion, and a resilient IDG business. Thus, we are turning more positive on Lenovo’s valuation story as growth drivers are increasingly skewed towards servers, as well as a its IDG business’ better-than-expected ability to pass down costs. Maintain BUY. Target price: HK$49.00.
Analyst
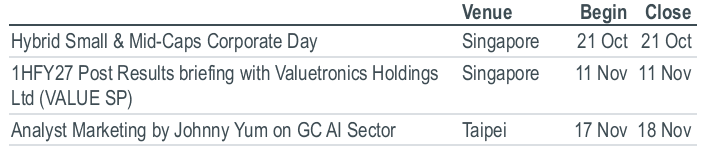
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


