

Country Daily
China Automobile Weekly / Alibaba Group / Kuaishou / Lenovo Group / NetEase / PDD Holdings / China Resources Mixc Lifestyle
Analyst
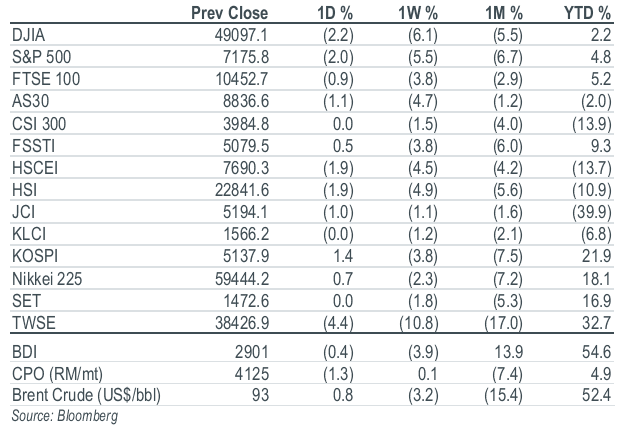
Key Indices
Top Stories
Sector Update | Automobile
NEV retail sales fell 13% yoy during 1-15 November, while ICE car retail sales almost halved. Memory chip prices could add Rmb4,000–8,000 to an ADAS-equipped BEV’s cost in 2027. MIIT will check supplier payment terms at 17 carmakers annually. We estimate Li Auto’s and Robosense’s 3Q26 net loss at Rmb1.7b (+172% yoy/flat qoq) and Rmb225m (+248% yoy/+186% qoq) respectively. Maintain MARKET WEIGHT. BUYs: BYD, Geely; SELLs: Li Auto, XPeng.
Company Results | Alibaba Group (9988 HK/BUY/HK$80.55/Target: HK$134.00)
Alibaba’s 2QFY27 results were mixed. Revenue rose 9.6% yoy to Rmb271.5b, broadly in line with our and consensus estimates. Adjusted EBITA more than doubled yoy to Rmb32.6b, beating our estimate by 6.1%, supported by a higher cloud EBITA margin and narrower quick commerce losses. Non-GAAP net profit rose 92.3% yoy to Rmb19.9b but missed our and consensus by 29%. Capex reached Rmb50.5b (+60% yoy), down from Rmb67.7b last quarter. Maintain BUY with a lower target price of HK$134.00 (US$137.00).
Company Results | Kuaishou (1024 HK/SELL/HK$23.04/Target: HK$19.00)
Kuaishou’s 3Q26 revenue missed expectations, while earnings beat. Revenue fell 11.1% yoy to Rmb31.6b, around 4% below both our estimate and consensus, on weaker online marketing and live-streaming revenue. Gross margin contracted 6.5ppt yoy to 48.2%, reflecting higher revenue-sharing and bandwidth costs. Non-IFRS net profit fell 84.2% yoy to Rmb790m but exceeded both our estimate and consensus. Management expects revenue and margins to remain under pressure in 4Q26. Downgrade to SELL with a lower target price of HK$19.00.
Company Results | Lenovo Group (992 HK/BUY/HK$16.25/Target: HK$30.50)
All three segments registered a solid beat with ISG business remaining the biggest growth driver as revenue grew 33% qoq and operating margins further expanding 0.5ppt qoq. Going forward, management remains confident in a resilient IDG business, elevated ISG growth, and sees no signs of slowdown in AI infrastructure capex beyond 2028. That said, we cut target price to HK$30.50 on a lower multiple as we factor in a sustained weakness in market sentiment towards AI infrastructure spending. Maintain BUY.
Company Results | NetEase (9999 HK/HOLD/HK$186.90/Target: HK$173.00)
NetEase’s 3Q26 revenue and earnings missed expectations. Revenue fell 1.8% yoy to Rmb27.9b, 8-9% below our and consensus estimates, mainly due to weaker games revenue. Gross margin expanded 4.3ppt yoy to 68.4% on lower revenue-sharing costs. Non-GAAP net profit fell 3.6% yoy to Rmb9.2b, 10-11% below our and consensus estimates, weighed down by lower investment income and a higher effective tax rate. Downgrade to HOLD with a lower target price of HK$173.00 (US$111.00).
Company Results | PDD Holdings (PDD US/BUY/US$77.45/Target: US$115.00)
PDD delivered a solid 3Q26 profit beat. Revenue was flat yoy at Rmb108.3b, around 6% below our and consensus estimates, as resilient domestic e-commerce monetisation offset Temu’s slowing growth. Lower sales and marketing expenses lifted non-GAAP operating profit by 20.5% yoy to Rmb32.6b, while non-GAAP net profit dropped 1.2% yoy to Rmb31.0b, 14-15% above our and consensus estimates. Maintain BUY with an unchanged target price of US$115.00.
Company Update | China Resources Mixc Lifestyle (1209 HK/BUY/HK$37.50/Target: HK$50.00)
We estimate total retail sales across CR Mixc’s malls grew by low single digits yoy in Oct 26. SSS dipped slightly with luxury malls reporting weaker SSS than the overall portfolio for the first time this year. 10M26 growth stayed at double digits. We expect luxury sales growth to slow and same-store sales to decline in 1H27, owing to the negative wealth effect. We trim our core net profit forecast and lower the target price to HK$50.00. Maintain BUY.
Top Stories
Sector Update | Automobile
NEV retail sales fell 13% yoy during 1-15 November, while ICE car retail sales almost halved. Memory chip prices could add Rmb4,000–8,000 to an ADAS-equipped BEV’s cost in 2027. MIIT will check supplier payment terms at 17 carmakers annually. We estimate Li Auto’s and Robosense’s 3Q26 net loss at Rmb1.7b (+172% yoy/flat qoq) and Rmb225m (+248% yoy/+186% qoq) respectively. Maintain MARKET WEIGHT. BUYs: BYD, Geely; SELLs: Li Auto, XPeng.
Company Results | Alibaba Group (9988 HK/BUY/HK$80.55/Target: HK$134.00)
Alibaba’s 2QFY27 results were mixed. Revenue rose 9.6% yoy to Rmb271.5b, broadly in line with our and consensus estimates. Adjusted EBITA more than doubled yoy to Rmb32.6b, beating our estimate by 6.1%, supported by a higher cloud EBITA margin and narrower quick commerce losses. Non-GAAP net profit rose 92.3% yoy to Rmb19.9b but missed our and consensus by 29%. Capex reached Rmb50.5b (+60% yoy), down from Rmb67.7b last quarter. Maintain BUY with a lower target price of HK$134.00 (US$137.00).
Company Results | Kuaishou (1024 HK/SELL/HK$23.04/Target: HK$19.00)
Kuaishou’s 3Q26 revenue missed expectations, while earnings beat. Revenue fell 11.1% yoy to Rmb31.6b, around 4% below both our estimate and consensus, on weaker online marketing and live-streaming revenue. Gross margin contracted 6.5ppt yoy to 48.2%, reflecting higher revenue-sharing and bandwidth costs. Non-IFRS net profit fell 84.2% yoy to Rmb790m but exceeded both our estimate and consensus. Management expects revenue and margins to remain under pressure in 4Q26. Downgrade to SELL with a lower target price of HK$19.00.
Company Results | Lenovo Group (992 HK/BUY/HK$16.25/Target: HK$30.50)
All three segments registered a solid beat with ISG business remaining the biggest growth driver as revenue grew 33% qoq and operating margins further expanding 0.5ppt qoq. Going forward, management remains confident in a resilient IDG business, elevated ISG growth, and sees no signs of slowdown in AI infrastructure capex beyond 2028. That said, we cut target price to HK$30.50 on a lower multiple as we factor in a sustained weakness in market sentiment towards AI infrastructure spending. Maintain BUY.
Company Results | NetEase (9999 HK/HOLD/HK$186.90/Target: HK$173.00)
NetEase’s 3Q26 revenue and earnings missed expectations. Revenue fell 1.8% yoy to Rmb27.9b, 8-9% below our and consensus estimates, mainly due to weaker games revenue. Gross margin expanded 4.3ppt yoy to 68.4% on lower revenue-sharing costs. Non-GAAP net profit fell 3.6% yoy to Rmb9.2b, 10-11% below our and consensus estimates, weighed down by lower investment income and a higher effective tax rate. Downgrade to HOLD with a lower target price of HK$173.00 (US$111.00).
Company Results | PDD Holdings (PDD US/BUY/US$77.45/Target: US$115.00)
PDD delivered a solid 3Q26 profit beat. Revenue was flat yoy at Rmb108.3b, around 6% below our and consensus estimates, as resilient domestic e-commerce monetisation offset Temu’s slowing growth. Lower sales and marketing expenses lifted non-GAAP operating profit by 20.5% yoy to Rmb32.6b, while non-GAAP net profit dropped 1.2% yoy to Rmb31.0b, 14-15% above our and consensus estimates. Maintain BUY with an unchanged target price of US$115.00.
Company Update | China Resources Mixc Lifestyle (1209 HK/BUY/HK$37.50/Target: HK$50.00)
We estimate total retail sales across CR Mixc’s malls grew by low single digits yoy in Oct 26. SSS dipped slightly with luxury malls reporting weaker SSS than the overall portfolio for the first time this year. 10M26 growth stayed at double digits. We expect luxury sales growth to slow and same-store sales to decline in 1H27, owing to the negative wealth effect. We trim our core net profit forecast and lower the target price to HK$50.00. Maintain BUY.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


