

Country Daily
ASMPT / CSPC Innovation Pharmaceutical / Ningbo Joyson Electronic Corporation / Tsingtao Brewery / Tencent Holdings
Analyst
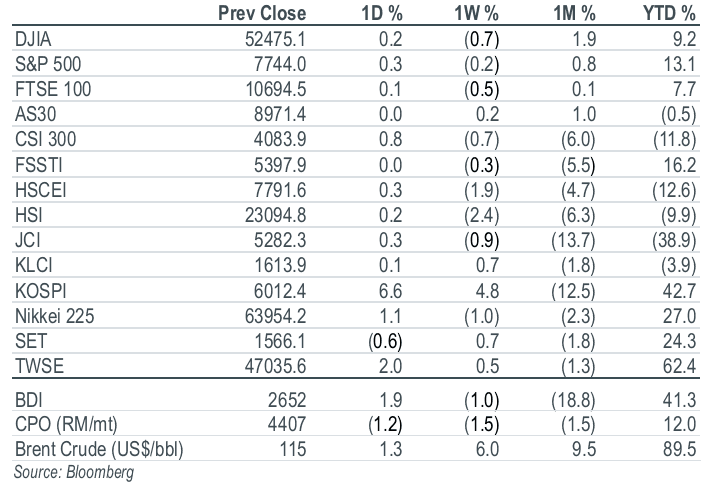
Key Indices
Top Stories
Company Results | ASMPT (522 HK/BUY/HK$118.30/Target: HK$184.00)
ASMPT’s 3Q26 revenue beat expectations while reported net profit was affected by share-based payments. Record bookings and a 1.69x book-to-bill ratio indicate robust demand, with 4Q26 guidance also exceeding consensus. Although memory-related TCB deliveries were delayed by HBM4 specification changes, mainstream tools and advanced-logic applications remain strong. Maintain BUY with a lower target price of HK$184.00.
Company Results | CSPC Innovation Pharmaceutical Co (300765 CH/BUY/Rmb38.24/Target: Rmb50.00)
CSPC Innovation’s 9M26 revenue rose 149.6% yoy to Rmb3,976.5m and net profit was Rmb1,209.9m, vs a net loss of Rmb24.0m in 9M25. 3Q26 revenue rose 35.5% yoy on a US$25m AstraZeneca milestone, but the net loss widened 141.0% yoy to Rmb51.3m. With SYS6010 meeting its Phase 3 primary endpoint and DP303c NDA accepted, we expect new launches to support earnings growth from 2028 onward. Maintain BUY. Lower the target price to Rmb50.00 reflecting its weaker 3Q26 earnings.
Company Results | Ningbo Joyson Electronic Corporation (600699 CH/HOLD/Rmb21.87/Target: Rmb19.00)
3Q26 net profit missed at Rmb219m (-47% yoy/-35% qoq) on renminbi appreciation, disposal, and chip-cost inflation. 9M26 new-order backlog slowed to Rmb61.5b (-13.9% yoy). Recovery depends on smart-driving ramp, global-OEM awards, robot components, and AIDC power. We cut our 2026-28 net profit forecasts by 31%/29%/26% on lower revenue/margins. Downgrade to HOLD, target price: Rmb19.00.
Company Results | Tsingtao Brewery (168 HK/BUY/HK$38.80/Target: HK$55.50)
Tsingtao Brewery’s 3Q26 net profit fell 17% yoy, primarily on a revenue decline, driven by lower volume yet partially offset by ASP increases, as well as gross margin contraction amid rising unit COGS and higher SG&A expenses. 3Q26 volume dropped 9% yoy, with the Tsingtao brand and secondary brand down 3% and 18% yoy respectively. Volume rose 1% yoy for mid-range to high-end products but decreased 17% yoy for other products. Maintain BUY; cut target price by 11% to HK$55.50.
Company Update | Tencent Holdings (700 HK/BUY/HK$387.60/Target: HK$537.00)
Tencent will report its 3Q26 results in mid-November. We expect Tencent’s revenue growth to remain solid at 9% yoy in 3Q26 despite macro headwinds, supported by stable gaming and resilient advertising driven by higher ad loads and improved eCPM. Operating profit is likely to remain flattish due to increased AI-related investment. Maintain BUY with a lower target price of HK$537.00.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


