
Analyst
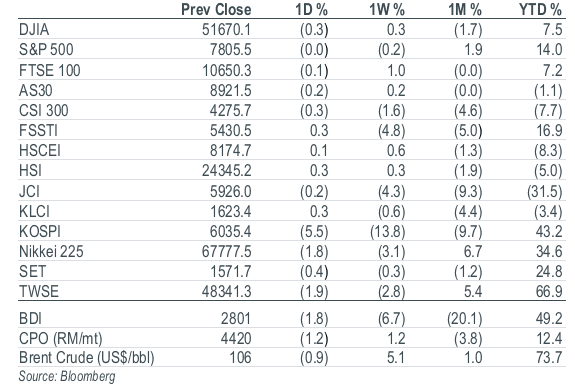
Key Indices
Top Stories
Company Update | JD.com (9618 HK/BUY/HK$104.90/Target: HK$148.00)
JD.com is expected to report its 3Q26 results in mid-November. We forecast group revenue growing 3.5% yoy to Rmb309.6b, broadly in line with consensus, supported by JD Retail’s return to positive growth. Retail operating margin should remain broadly stable yoy, while narrowing food delivery and Jingxi losses should support group earnings recovery, partly offset by a modest increase in international losses as JD continues its European expansion. Maintain BUY with an unchanged target price of HK$148.00 (US$38.00).
Company Update | Lenovo Group (992 HK/BUY/HK$31.10/Target: HK$49.00)
IDC’s 3Q26 preliminary PC shipment data indicates that Lenovo’s PC shipments declined 22.6% yoy and 10.2% qoq to 14.9m units, which is 8%/4% below our and consensus estimates. The miss was primarily due to a stronger-than-expected front-loading effect in 1H26, which in turn led to lower shipment numbers during the inventory digestion period. We trim our PC shipment forecast for Lenovo accordingly, but we also expect ASP hikes to mostly offset any shortfall in shipment volume. Maintain BUY. Target price: HK$49.00.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


