

Company Coverage
Lenovo Group (992 HK): 2QFY27: Robust AI Infrastructure Demand Drives Earnings Beat
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$16.25
HK$30.50
87.7%
HK$49.00
Analyst
Analyst
Highlights
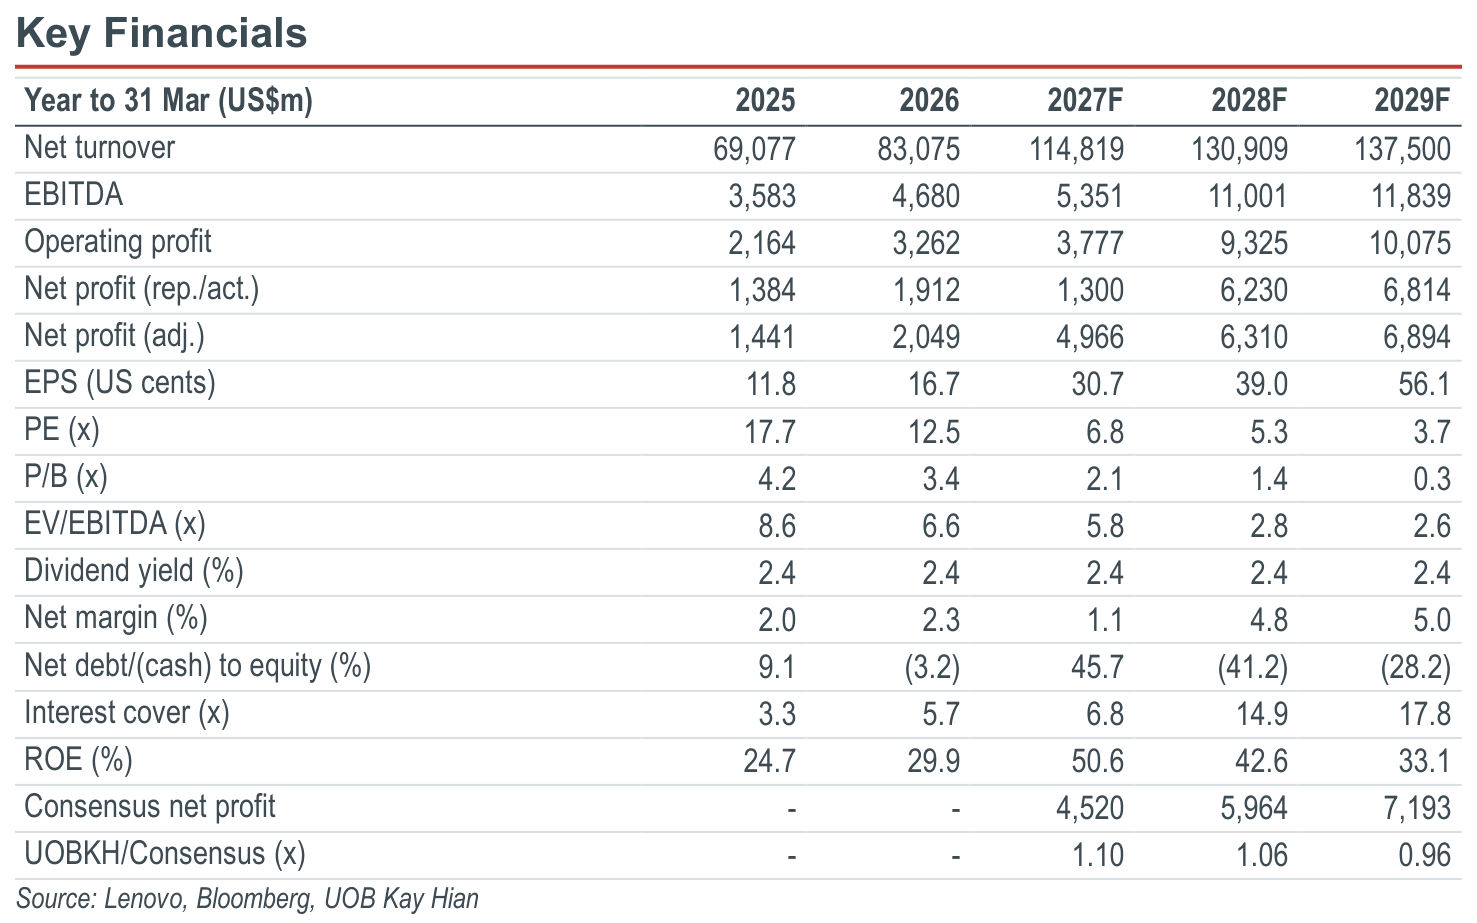
- ISG continues to drive robust top-line growth, supported by robust AI demand and a US$80b pipeline; and IDG’s sales and profitability are guided to remain resilient amid shipment declines, with PC volumes potentially reaching an inflection point in mid-27.
- Maintain BUY with a lower target price of HK$30.50..
Analysis
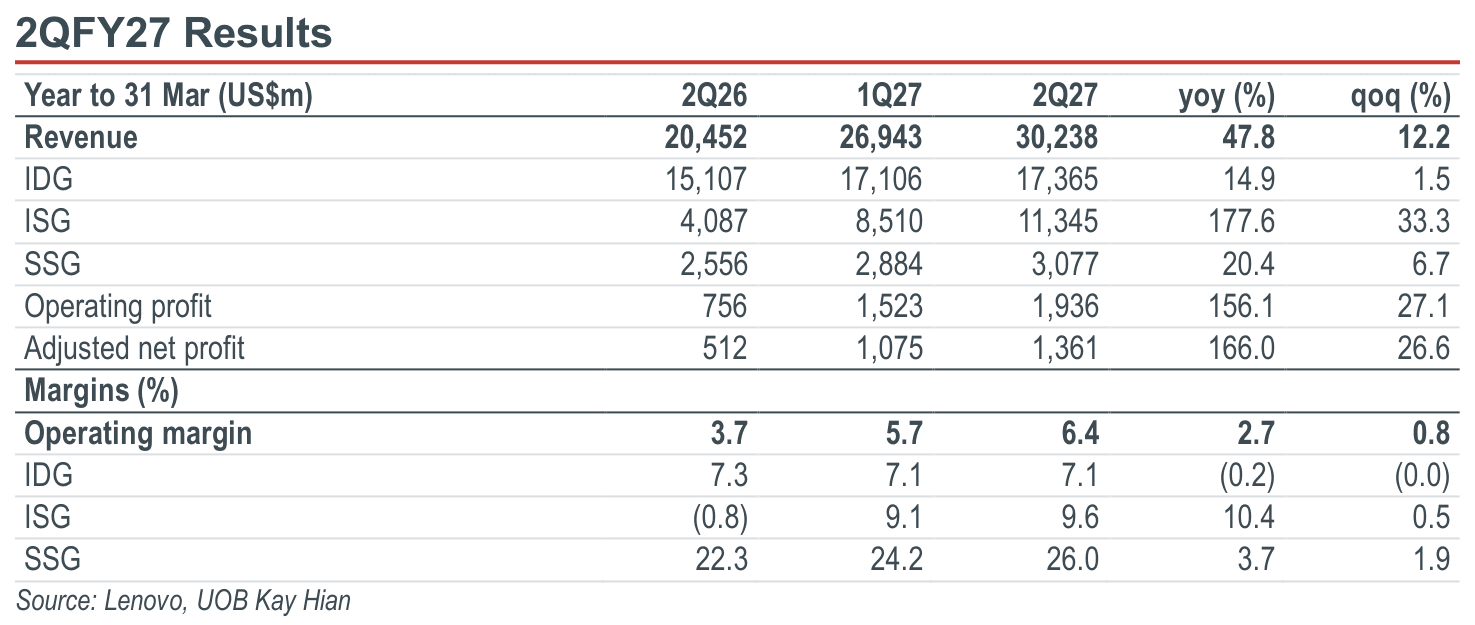
- ISG surge led a broad-based beat. Lenovo’s 2QFY27 revenue rose 47.8% yoy and 12.2% qoq to US$30.2b, beating our and consensus estimates by 10.9% and 8.8%, respectively. By segment, intelligent devices group (IDG) revenue increased 14.9% yoy and 1.5% qoq to US$17.4b, 3.6% and 2.4% above our and consensus estimates respectively. Infrastructure solutions group (ISG) revenue surged 177.6% yoy and 33.3% qoq to US$11.3b, exceeding our and consensus estimates by 26.2% and 18.6% respectively. Solutions and services group (SSG) revenue grew 20.4% yoy and 6.7% qoq to US$3.1b, broadly in line with expectations. Operating margins were a solid beat across all three segments as effective cost controls had more than offset the weaker-than-expected gross margins. As a result, adjusted net profit rose 166.0% yoy and 26.6% qoq to US$1.4b, beating our and consensus estimates by 11.0% and 6.8% respectively.
Highlights
- ISG continues to drive robust top-line growth, supported by robust AI demand and a US$80b pipeline; and IDG’s sales and profitability are guided to remain resilient amid shipment declines, with PC volumes potentially reaching an inflection point in mid-27.
- Maintain BUY with a lower target price of HK$30.50..
Analysis
- ISG surge led a broad-based beat. Lenovo’s 2QFY27 revenue rose 47.8% yoy and 12.2% qoq to US$30.2b, beating our and consensus estimates by 10.9% and 8.8%, respectively. By segment, intelligent devices group (IDG) revenue increased 14.9% yoy and 1.5% qoq to US$17.4b, 3.6% and 2.4% above our and consensus estimates respectively. Infrastructure solutions group (ISG) revenue surged 177.6% yoy and 33.3% qoq to US$11.3b, exceeding our and consensus estimates by 26.2% and 18.6% respectively. Solutions and services group (SSG) revenue grew 20.4% yoy and 6.7% qoq to US$3.1b, broadly in line with expectations. Operating margins were a solid beat across all three segments as effective cost controls had more than offset the weaker-than-expected gross margins. As a result, adjusted net profit rose 166.0% yoy and 26.6% qoq to US$1.4b, beating our and consensus estimates by 11.0% and 6.8% respectively.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$16.25
HK$30.50
87.7%
HK$49.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


