

分析員
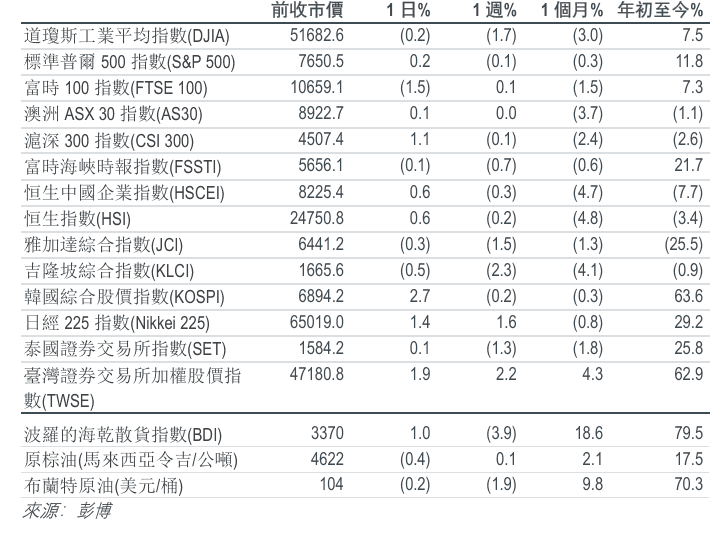
主要指數
重點要聞
行業最新動態 | 中國互聯網
中國的雲端運算及大型語言模型(LLM)企業正日漸進軍晶片研發領域,其戰略目標是降低算力成本、確保供應穩定,並提升模型與硬件的協同優化能力。 經濟效益最終體現為每權杖成本下降,以及人工智能資本支出回報提升。 維持「與大市一致」評級。 首選「買入」股份:阿里巴巴及智譜。
公司更新 | 阿里健康信息技術(241 HK/買入/港幣3.06元/目標價:港幣4元)
阿里健康將2027財年收入按年增長目標由10%至15%下調至7%至10%,同時維持經調整純利指引於人民幣19-23億元不變。此舉反映對商品價格補貼的主動優化,並將節省之資金重新投入於B2C+O2O供應鏈整合。因應創新藥業務動能、與阿里巴巴深化協同效應以及人工智能應用的拓展,我們將其2027財年收入按年增長預測由12.4%下調至8.5%,同時維持2027至2029財年收入與經調整純利複合年增長率分別為12%及15%。維持「買入」評級。目標價下調至港幣4元。
重點要聞
行業最新動態 | 中國互聯網
中國的雲端運算及大型語言模型(LLM)企業正日漸進軍晶片研發領域,其戰略目標是降低算力成本、確保供應穩定,並提升模型與硬件的協同優化能力。 經濟效益最終體現為每權杖成本下降,以及人工智能資本支出回報提升。 維持「與大市一致」評級。 首選「買入」股份:阿里巴巴及智譜。
公司更新 | 阿里健康信息技術(241 HK/買入/港幣3.06元/目標價:港幣4元)
阿里健康將2027財年收入按年增長目標由10%至15%下調至7%至10%,同時維持經調整純利指引於人民幣19-23億元不變。此舉反映對商品價格補貼的主動優化,並將節省之資金重新投入於B2C+O2O供應鏈整合。因應創新藥業務動能、與阿里巴巴深化協同效應以及人工智能應用的拓展,我們將其2027財年收入按年增長預測由12.4%下調至8.5%,同時維持2027至2029財年收入與經調整純利複合年增長率分別為12%及15%。維持「買入」評級。目標價下調至港幣4元。
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


