

Wealth Daily
Nvidia Gains as Stocks and Metals Retreat
Today’s Must-Know News
Overnight Markets
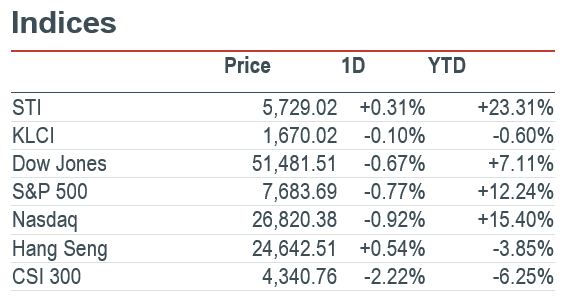
Market Movers: At Monday’s US close, the S&P 500 fell 0.77%; China’s CSI 300 lost about 2.2% in its first session after the holiday. Nvidia (NVDA US) rose about 1.7% after announcing an additional US$150bn buyback and an open agent-safety platform with more than 100 participating organisations. MongoDB (MDB US) slid about 18.5% as its chief executive left to lead Meta Platforms’ (META US) new enterprise platform, bringing agents, APIs and coding tools to businesses; MongoDB retained its guidance. At Monday’s Australian close, Northern Star (NST AU) gained about 6.2% in the first trading response to disclosure that it had rejected Gold Fields’ A$38.7bn approach. The stock-heavy proposal was worth A$36.1bn at Friday’s prices. Gold Fields still seeks engagement, with no agreed deal. (AP / Nvidia / Nvidia / Meta / MongoDB / Gold Fields) Nvidia (NVDA US) & Meta Platforms (META US) are our Core Recommendations.
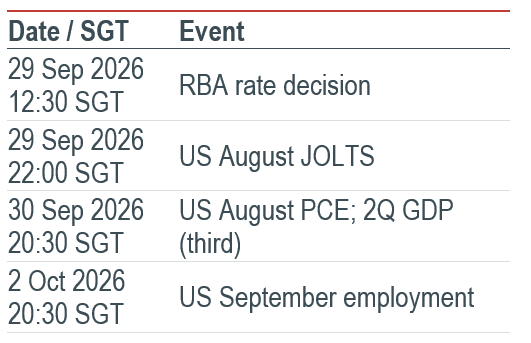
Macro: The RBA announces its rate decision at 12:30 SGT on 29 September. Finder’s latest panel has 90% expecting a rise from the current 4.35%. Guidance on persistent inflation and labour-market softness will matter alongside the decision: a hawkish path would pressure rate-sensitive valuations, while a surprise hold could reverse expectations of further tightening. (RBA / Finder)
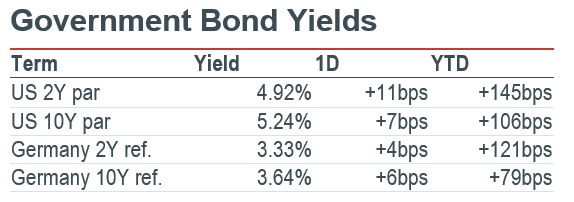
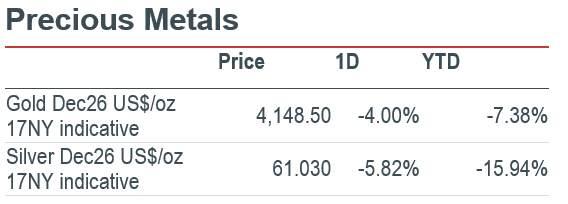
FICC: The US 10Y Treasury par yield rose 7bps from Friday to 5.24% on Monday. At the later 17:00 New York indicative snapshot, December gold fell 4.00% to US$4,148.50/oz and silver declined 5.82% to US$61.030/oz against Friday’s same-time levels. Higher yields increase the opportunity cost of holding non-yielding metals. (US Treasury / Yahoo Finance)
AI
Meta’s enterprise push disrupts MongoDB’s leadership. Meta Platforms (META US) launched its Enterprise Platform under departing MongoDB CEO CJ Desai, commercialising Muse agents and tools. MongoDB (MDB US) fell about 18.5% at Monday’s U.S. close despite reaffirming third-quarter and FY2027 guidance and appointing Dev Ittycheria interim CEO. Enterprise distribution widens Meta’s AI monetisation options, while MongoDB faces leadership uncertainty. (Meta / MongoDB) Meta Platforms (META US) is our Core Recommendation.
Agent safeguards broaden Nvidia’s enterprise investment case. Nvidia (NVDA US) launched Open Agent Safety Platform with over 100 organisations: OpenShell enforces software boundaries; Sentry independently monitors agents via BlueField-4 chips. An additional US$150bn buyback authorisation lifted remaining capacity to US$235bn. Shares gained about 1.7% at Monday’s U.S. close. Safer deployment could support enterprise demand, although effectiveness depends on implementation. (Nvidia / Nvidia buyback) Nvidia (NVDA US) is our Core Recommendation.
OpenAI’s release setback complicates frontier AI commercialisation. OpenAI cancelled October’s planned GPT-6.1 Astra launch for ChatGPT and Codex after internal testing raised safety concerns, WSJ reported. Florida separately requested a temporary injunction against OpenAI and ChatGPT development; the request is not a court ruling. The release setback and litigation request add uncertainty to frontier-AI commercialisation and deployment requirements. (WSJ / Axios)
Anthropic improves task economics at unchanged prices. Anthropic launched Claude Sonnet 5.5, claiming over 30% faster generation and up to 30% lower task costs than Sonnet 5 through fewer tokens. Pricing stays US$2 per million input tokens and US$10 per million output tokens. AWS confirmed availability through Bedrock and Claude Platform on AWS. These company-tested efficiencies could widen enterprise usage without reducing token prices. (Anthropic / AWS)
Americas
SpaceX reaches orbit but shortens its test. SpaceX (SPCX US) completed Starship’s first orbital flight on Monday, deploying 26 next-generation Starlink satellites. An upper-stage engine problem prompted return after about three hours, versus a planned ten-hour test. Payload delivery advances the commercial case for greater launch capacity, but the shortened mission leaves reliability and extended-duration operations to be demonstrated. (Reuters)
Boeing’s certification delay clouds its delivery recovery. Boeing (BA US) fell about 6.9% at Monday’s U.S. close after the Federal Aviation Administration delayed 737 MAX 10 certification pending a software fix, without estimating the delay. Disclosed Saturday, the problem affects automated flight guidance in a specific landing scenario. The new certification dependency leaves delivery timing and cash-conversion recovery less certain. (Reuters)
Nu’s reported UK ambitions face investor resistance. Nu Holdings (NU US) fell about 10.0% at Monday’s U.S. close, the first session after Saturday’s report of preliminary Monzo talks at £8bn–£10bn. Nu said on Monday it does not comment on speculation; no agreed deal was confirmed. A purchase could provide a UK platform, but price, integration demands and a shift from organic expansion increase execution risk. (Reuters)
Kodiak’s trial data strengthen its filing case. Kodiak Sciences (KOD US) surged about 178.0% at Monday’s U.S. close after Zenkuda and tabirafusp-ted met Phase 3 DAYBREAK’s primary vision non-inferiority endpoints against aflibercept in wet age-related macular degeneration. Zenkuda reached a 24-week dosing interval in 54% of patients. Zenkuda’s multi-indication filing is planned for the fourth quarter; reduced treatment frequency supports adoption potential, subject to approval. (Kodiak Sciences)
Merck expands oncology pipeline with preclinical licence. Merck (MRK US) secured worldwide rights to SciBrunch’s preclinical oral KRAS G12D inhibitor SPR2015 for US$400mn upfront, within US$2.13bn total potential consideration. The closed deal creates a third-quarter US$400mn pre-tax charge, about US$0.13 per share, in GAAP and non-GAAP results. The licence broadens its oncology pipeline, but clinical success is unproven and further payments depend on milestones. (Merck)
US fuel rules reset automakers’ compliance incentives. The U.S. finalised a 2031 average fleet fuel-economy target of 34.9 miles per gallon, replacing the previous 50.4-mpg requirement, and will end compliance-credit trading in 2028. Automakers gain flexibility to sell petrol vehicles, while electric-vehicle producers lose potential credit value. Lower compliance costs could support margins, although consumers remain exposed to greater lifetime fuel spending. (Reuters)
Jefferies’ earnings highlight an uneven banking recovery. After Monday’s U.S. close, Jefferies Financial Group (JEF US) reported quarterly profit of US$260.6mn versus US$224.0mn a year earlier, and US$1.08 diluted voting-share earnings. Investment-banking revenue rose 17% to US$1.33bn; equities revenue gained 29% to a record US$626mn. Fixed-income revenue fell 26%. Stronger deals and equities support banking earnings, but trading performance remains uneven. (Jefferies)
Greater China
Beijing signals stronger policy support. China’s cabinet called Monday for faster bond issuance, more effective investment and additional relending support for technology, agriculture and small businesses. The official readout retained the 2026 growth ambition of 4.5–5% and said housing, employment and income measures were being studied. The direction supports infrastructure and domestic-demand expectations, but the absence of a quantified new package leaves implementation and transmission to corporate earnings unresolved. (State Council)
NIO brings Geely into battery swapping. NIO (9866.HK) announced Monday that Geely Holding (0175.HK) would contribute its Yiyi Power business and RMB640m for 30% of NIO Power, implying a RMB16bn post-investment valuation. NIO China would retain 63.6%, subject to completion approvals. Combining networks could improve utilisation and reduce duplicated investment; preliminary cooperation on battery-swapping passenger cars remains a strategic intention, so infrastructure economics matter more immediately than prospective vehicle volumes. (NIO / Bloomberg) 0175.HK is our Core Recommendation.
Gotion deepens Volkswagen battery ties. Gotion (002074.SZ) disclosed plans Monday for three ventures with Volkswagen’s PowerCo involving about €3.22bn of investment, including roughly €1.60bn from Gotion. The proposals cover Spanish and Slovak battery plants and Moroccan cathode materials, with planned cell capacity of 29.1GWh and 8.4GWh respectively. They strengthen access to European vehicle demand but increase capital commitments; definitive agreements and shareholder and regulatory approvals remain outstanding. (CnEVPost / China Fund)
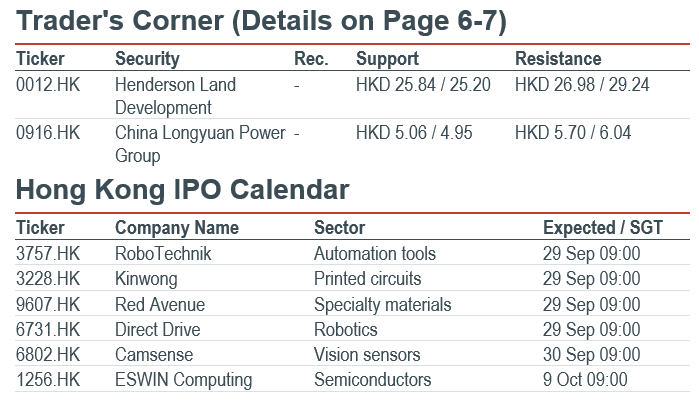
ESWIN opens Hong Kong share offer. Beijing ESWIN Computing Technology (1256.HK) launched its Hong Kong offering Monday, marketing 1.5702bn H shares at HK$1.48–1.59 each. The base offer implies approximately HK$2.32–2.50bn of gross proceeds before expenses and any size adjustment. The new semiconductor issue adds a financing test for the sector; final pricing and investor demand will matter more than the indicative range when judging appetite for additional technology supply. (HKEX)
Macau holiday arrivals strengthen. Macau’s police reported Monday that visitor arrivals over the mainland’s three-day Mid-Autumn holiday reached 415,432, up 19.5% from the comparable holiday a year earlier. Saturday accounted for 171,566 arrivals. The fresh traffic figures support the demand backdrop for hotels, retail and casino resorts, although visitor growth alone does not establish gaming revenue or spending per guest; those conversion measures remain important for earnings expectations. (Macau Post / AGB)
Asia ex. China
Northern Star rallies on takeover disclosure. Northern Star (NST.AX) rose 6.15% to A$23.47 Monday after its rejection of Gold Fields’ approach became public. The proposal was worth A$38.7bn when received earlier in September, falling to A$36.1bn at Friday’s prices because most consideration was stock. Gold Fields reiterated Monday that it sought engagement. The valuation dispute and variable share consideration leave considerable uncertainty over whether a transaction can progress. (Gold Fields / Reuters)
Nidec falls as accounting uncertainty deepens. Nidec (6594.T) closed Monday down 17.61% at ¥2,340 after reports of a potential ¥1tn impairment and the removal of president Mitsuya Kishida. Its own statement confirmed that executive changes and large impairments were under consideration but said nothing had been decided. The distinction matters: the reported charge is unconfirmed, while the sharp repricing highlights uncertainty over the company’s balance sheet and governance repair. (Nidec / Jiji)
CDL reset meets investor scepticism. City Developments (C09.SI) fell 8.11% to S$7.59 Monday after publishing its GET+ strategy. For 2027–2029, the group targets S$6bn of divestments and S$5bn of investments, alongside a minimum 35% dividend payout of reported profit after tax and minority interests. The plan links capital recycling with shareholder returns, but the negative reaction suggests investors want evidence of execution; disposal timing and reinvestment returns will determine whether the strategy improves balance-sheet flexibility. (CDL / BT)
Warburg raises the stakes at Ingenia. Ingenia (INA.AX) rose 5.78% to A$4.76 Monday in the first session after disclosing a further revised Warburg Pincus proposal of A$5.25 cash per stapled security. The conditional bid requires Ingenia to abandon its Peet acquisition and remains subject to due diligence and financing. The board had formed no recommendation. The competing paths pit immediate cash consideration against the execution risks of Ingenia’s expansion strategy. (ASX / Stock Analysis)
EMEA and Others
TotalEnergies strengthens capital returns. TotalEnergies (TTE.PA) said Monday that it would buy back US$2.5bn of shares in the fourth quarter and US$2–2.5bn in the first quarter of 2027. Its board adopted a policy targeting dividend growth above 5% annually through 2030, while planning US$14–17bn of yearly net investment over 2027–2032. The framework balances reinvestment and distributions, but delivery depends on cash generation and future dividend approvals. (TotalEnergies)
UK builders reprice buyer support. Persimmon (PSN.L) surged about 14.7% and Barratt Redrow (BTRW.L) gained about 11.7% Monday in the first trading response to the government’s weekend homebuyer proposal. The scheme envisages a 2.5% deposit and government equity loans of up to 20%. Lower upfront funding could unlock demand, but income limits, regional price caps and developer contributions remain unsettled, leaving the eventual effect on volumes and margins uncertain. (Reuters)
Entain cuts growth after Brazil restrictions. Entain (ENT.L) lowered its 2026 constant-currency online net gaming revenue growth outlook Monday to 4–6%, from 5–7%, assuming Brazil’s provisional betting ban lasts through year-end. Underlying group EBITDA is now expected near the lower end of £910–960m and online margins near the bottom of 21–22%. The guidance illustrates how regulatory intervention can compress operating leverage even where the affected market contributes only modest profit. (Entain)
Evonik rejects reported BASF approach. Evonik (EVK.DE) rejected BASF’s approximately €10.3bn takeover approach as too low, Reuters reported Monday, citing people familiar with the matter. The indicated €22.15 per share offer follows the earlier disclosure of BASF’s interest. BASF said it would remain disciplined and needed engagement to verify synergies. The rejection sharpens the valuation gap; a higher proposal or credible standalone earnings improvement would be needed to resolve it. (Reuters / Dow Jones)
Rexel starts equity financing for GCG. Rexel (RXL.PA) launched an approximately €500m share placement Monday to help fund its previously announced acquisition of GCG. The accelerated bookbuild excludes shareholders’ preferential subscription rights and supports a target net-debt-to-EBITDA-after-leases ratio of about twice from 2027. The financing reduces reliance on debt but introduces dilution; the final issue price and share count will determine the immediate cost to existing holders. (Rexel)
Traders’ corner
Our Technical View
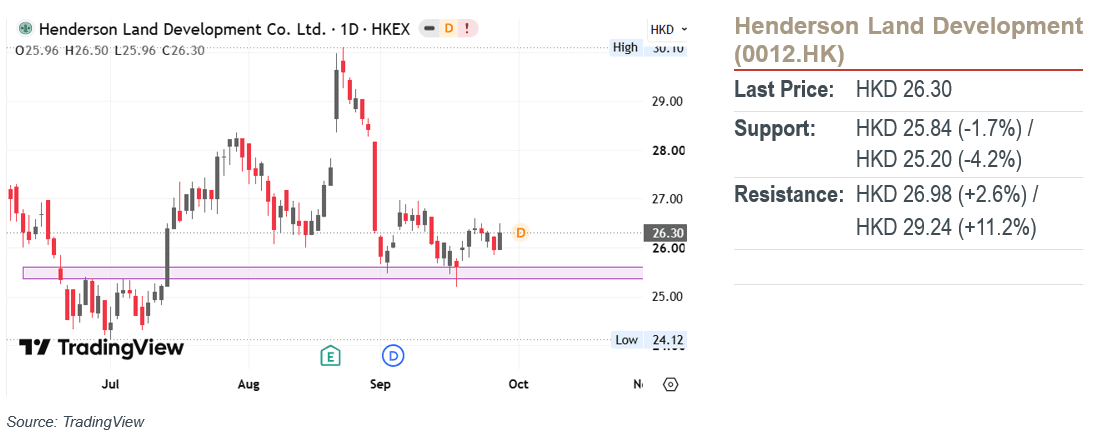
Price executed a retest and defense of its resistance-turned-support zone, printing a higher low within the emerging swing sequence.
The RSI remains in bearish territory, its steady upward trajectory toward the neutral 50-midline signals decaying downside momentum and a transition toward bullish velocity.
A decisive structural breach and daily close above the recent high pivot threshold will complete a bullish trend continuation pattern, opening path-of-least-resistance dynamics for an accelerated upward momentum expansion toward higher supply targets.
Our Technical View
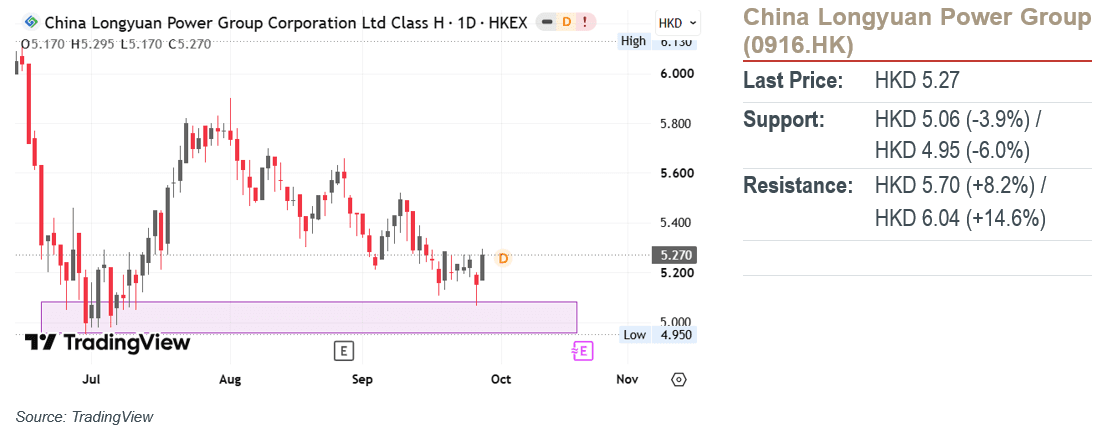
Price rebounded from its previous low support zone, validated by the print of a hammer candlestick formation.
The RSI has crossed above its neutral 50-midline and continues to slope upward, signaling trend velocity acceleration.
The HK$5.28 pivot threshold represents the key overhead swing high resistance; a decisive daily close above HK$5.28 will complete a bullish accumulation pattern, opening path-of-least-resistance dynamics for a sustained upward expansion toward higher supply targets.
Market Movers: At Monday’s US close, the S&P 500 fell 0.77%; China’s CSI 300 lost about 2.2% in its first session after the holiday. Nvidia (NVDA US) rose about 1.7% after announcing an additional US$150bn buyback and an open agent-safety platform with more than 100 participating organisations. MongoDB (MDB US) slid about 18.5% as its chief executive left to lead Meta Platforms’ (META US) new enterprise platform, bringing agents, APIs and coding tools to businesses; MongoDB retained its guidance. At Monday’s Australian close, Northern Star (NST AU) gained about 6.2% in the first trading response to disclosure that it had rejected Gold Fields’ A$38.7bn approach. The stock-heavy proposal was worth A$36.1bn at Friday’s prices. Gold Fields still seeks engagement, with no agreed deal. (AP / Nvidia / Nvidia / Meta / MongoDB / Gold Fields) Nvidia (NVDA US) & Meta Platforms (META US) are our Core Recommendations.
Macro: The RBA announces its rate decision at 12:30 SGT on 29 September. Finder’s latest panel has 90% expecting a rise from the current 4.35%. Guidance on persistent inflation and labour-market softness will matter alongside the decision: a hawkish path would pressure rate-sensitive valuations, while a surprise hold could reverse expectations of further tightening. (RBA / Finder)
FICC: The US 10Y Treasury par yield rose 7bps from Friday to 5.24% on Monday. At the later 17:00 New York indicative snapshot, December gold fell 4.00% to US$4,148.50/oz and silver declined 5.82% to US$61.030/oz against Friday’s same-time levels. Higher yields increase the opportunity cost of holding non-yielding metals. (US Treasury / Yahoo Finance)
AI
Meta’s enterprise push disrupts MongoDB’s leadership. Meta Platforms (META US) launched its Enterprise Platform under departing MongoDB CEO CJ Desai, commercialising Muse agents and tools. MongoDB (MDB US) fell about 18.5% at Monday’s U.S. close despite reaffirming third-quarter and FY2027 guidance and appointing Dev Ittycheria interim CEO. Enterprise distribution widens Meta’s AI monetisation options, while MongoDB faces leadership uncertainty. (Meta / MongoDB) Meta Platforms (META US) is our Core Recommendation.
Agent safeguards broaden Nvidia’s enterprise investment case. Nvidia (NVDA US) launched Open Agent Safety Platform with over 100 organisations: OpenShell enforces software boundaries; Sentry independently monitors agents via BlueField-4 chips. An additional US$150bn buyback authorisation lifted remaining capacity to US$235bn. Shares gained about 1.7% at Monday’s U.S. close. Safer deployment could support enterprise demand, although effectiveness depends on implementation. (Nvidia / Nvidia buyback) Nvidia (NVDA US) is our Core Recommendation.
OpenAI’s release setback complicates frontier AI commercialisation. OpenAI cancelled October’s planned GPT-6.1 Astra launch for ChatGPT and Codex after internal testing raised safety concerns, WSJ reported. Florida separately requested a temporary injunction against OpenAI and ChatGPT development; the request is not a court ruling. The release setback and litigation request add uncertainty to frontier-AI commercialisation and deployment requirements. (WSJ / Axios)
Anthropic improves task economics at unchanged prices. Anthropic launched Claude Sonnet 5.5, claiming over 30% faster generation and up to 30% lower task costs than Sonnet 5 through fewer tokens. Pricing stays US$2 per million input tokens and US$10 per million output tokens. AWS confirmed availability through Bedrock and Claude Platform on AWS. These company-tested efficiencies could widen enterprise usage without reducing token prices. (Anthropic / AWS)
Americas
SpaceX reaches orbit but shortens its test. SpaceX (SPCX US) completed Starship’s first orbital flight on Monday, deploying 26 next-generation Starlink satellites. An upper-stage engine problem prompted return after about three hours, versus a planned ten-hour test. Payload delivery advances the commercial case for greater launch capacity, but the shortened mission leaves reliability and extended-duration operations to be demonstrated. (Reuters)
Boeing’s certification delay clouds its delivery recovery. Boeing (BA US) fell about 6.9% at Monday’s U.S. close after the Federal Aviation Administration delayed 737 MAX 10 certification pending a software fix, without estimating the delay. Disclosed Saturday, the problem affects automated flight guidance in a specific landing scenario. The new certification dependency leaves delivery timing and cash-conversion recovery less certain. (Reuters)
Nu’s reported UK ambitions face investor resistance. Nu Holdings (NU US) fell about 10.0% at Monday’s U.S. close, the first session after Saturday’s report of preliminary Monzo talks at £8bn–£10bn. Nu said on Monday it does not comment on speculation; no agreed deal was confirmed. A purchase could provide a UK platform, but price, integration demands and a shift from organic expansion increase execution risk. (Reuters)
Kodiak’s trial data strengthen its filing case. Kodiak Sciences (KOD US) surged about 178.0% at Monday’s U.S. close after Zenkuda and tabirafusp-ted met Phase 3 DAYBREAK’s primary vision non-inferiority endpoints against aflibercept in wet age-related macular degeneration. Zenkuda reached a 24-week dosing interval in 54% of patients. Zenkuda’s multi-indication filing is planned for the fourth quarter; reduced treatment frequency supports adoption potential, subject to approval. (Kodiak Sciences)
Merck expands oncology pipeline with preclinical licence. Merck (MRK US) secured worldwide rights to SciBrunch’s preclinical oral KRAS G12D inhibitor SPR2015 for US$400mn upfront, within US$2.13bn total potential consideration. The closed deal creates a third-quarter US$400mn pre-tax charge, about US$0.13 per share, in GAAP and non-GAAP results. The licence broadens its oncology pipeline, but clinical success is unproven and further payments depend on milestones. (Merck)
US fuel rules reset automakers’ compliance incentives. The U.S. finalised a 2031 average fleet fuel-economy target of 34.9 miles per gallon, replacing the previous 50.4-mpg requirement, and will end compliance-credit trading in 2028. Automakers gain flexibility to sell petrol vehicles, while electric-vehicle producers lose potential credit value. Lower compliance costs could support margins, although consumers remain exposed to greater lifetime fuel spending. (Reuters)
Jefferies’ earnings highlight an uneven banking recovery. After Monday’s U.S. close, Jefferies Financial Group (JEF US) reported quarterly profit of US$260.6mn versus US$224.0mn a year earlier, and US$1.08 diluted voting-share earnings. Investment-banking revenue rose 17% to US$1.33bn; equities revenue gained 29% to a record US$626mn. Fixed-income revenue fell 26%. Stronger deals and equities support banking earnings, but trading performance remains uneven. (Jefferies)
Greater China
Beijing signals stronger policy support. China’s cabinet called Monday for faster bond issuance, more effective investment and additional relending support for technology, agriculture and small businesses. The official readout retained the 2026 growth ambition of 4.5–5% and said housing, employment and income measures were being studied. The direction supports infrastructure and domestic-demand expectations, but the absence of a quantified new package leaves implementation and transmission to corporate earnings unresolved. (State Council)
NIO brings Geely into battery swapping. NIO (9866.HK) announced Monday that Geely Holding (0175.HK) would contribute its Yiyi Power business and RMB640m for 30% of NIO Power, implying a RMB16bn post-investment valuation. NIO China would retain 63.6%, subject to completion approvals. Combining networks could improve utilisation and reduce duplicated investment; preliminary cooperation on battery-swapping passenger cars remains a strategic intention, so infrastructure economics matter more immediately than prospective vehicle volumes. (NIO / Bloomberg) 0175.HK is our Core Recommendation.
Gotion deepens Volkswagen battery ties. Gotion (002074.SZ) disclosed plans Monday for three ventures with Volkswagen’s PowerCo involving about €3.22bn of investment, including roughly €1.60bn from Gotion. The proposals cover Spanish and Slovak battery plants and Moroccan cathode materials, with planned cell capacity of 29.1GWh and 8.4GWh respectively. They strengthen access to European vehicle demand but increase capital commitments; definitive agreements and shareholder and regulatory approvals remain outstanding. (CnEVPost / China Fund)
ESWIN opens Hong Kong share offer. Beijing ESWIN Computing Technology (1256.HK) launched its Hong Kong offering Monday, marketing 1.5702bn H shares at HK$1.48–1.59 each. The base offer implies approximately HK$2.32–2.50bn of gross proceeds before expenses and any size adjustment. The new semiconductor issue adds a financing test for the sector; final pricing and investor demand will matter more than the indicative range when judging appetite for additional technology supply. (HKEX)
Macau holiday arrivals strengthen. Macau’s police reported Monday that visitor arrivals over the mainland’s three-day Mid-Autumn holiday reached 415,432, up 19.5% from the comparable holiday a year earlier. Saturday accounted for 171,566 arrivals. The fresh traffic figures support the demand backdrop for hotels, retail and casino resorts, although visitor growth alone does not establish gaming revenue or spending per guest; those conversion measures remain important for earnings expectations. (Macau Post / AGB)
Asia ex. China
Northern Star rallies on takeover disclosure. Northern Star (NST.AX) rose 6.15% to A$23.47 Monday after its rejection of Gold Fields’ approach became public. The proposal was worth A$38.7bn when received earlier in September, falling to A$36.1bn at Friday’s prices because most consideration was stock. Gold Fields reiterated Monday that it sought engagement. The valuation dispute and variable share consideration leave considerable uncertainty over whether a transaction can progress. (Gold Fields / Reuters)
Nidec falls as accounting uncertainty deepens. Nidec (6594.T) closed Monday down 17.61% at ¥2,340 after reports of a potential ¥1tn impairment and the removal of president Mitsuya Kishida. Its own statement confirmed that executive changes and large impairments were under consideration but said nothing had been decided. The distinction matters: the reported charge is unconfirmed, while the sharp repricing highlights uncertainty over the company’s balance sheet and governance repair. (Nidec / Jiji)
CDL reset meets investor scepticism. City Developments (C09.SI) fell 8.11% to S$7.59 Monday after publishing its GET+ strategy. For 2027–2029, the group targets S$6bn of divestments and S$5bn of investments, alongside a minimum 35% dividend payout of reported profit after tax and minority interests. The plan links capital recycling with shareholder returns, but the negative reaction suggests investors want evidence of execution; disposal timing and reinvestment returns will determine whether the strategy improves balance-sheet flexibility. (CDL / BT)
Warburg raises the stakes at Ingenia. Ingenia (INA.AX) rose 5.78% to A$4.76 Monday in the first session after disclosing a further revised Warburg Pincus proposal of A$5.25 cash per stapled security. The conditional bid requires Ingenia to abandon its Peet acquisition and remains subject to due diligence and financing. The board had formed no recommendation. The competing paths pit immediate cash consideration against the execution risks of Ingenia’s expansion strategy. (ASX / Stock Analysis)
EMEA and Others
TotalEnergies strengthens capital returns. TotalEnergies (TTE.PA) said Monday that it would buy back US$2.5bn of shares in the fourth quarter and US$2–2.5bn in the first quarter of 2027. Its board adopted a policy targeting dividend growth above 5% annually through 2030, while planning US$14–17bn of yearly net investment over 2027–2032. The framework balances reinvestment and distributions, but delivery depends on cash generation and future dividend approvals. (TotalEnergies)
UK builders reprice buyer support. Persimmon (PSN.L) surged about 14.7% and Barratt Redrow (BTRW.L) gained about 11.7% Monday in the first trading response to the government’s weekend homebuyer proposal. The scheme envisages a 2.5% deposit and government equity loans of up to 20%. Lower upfront funding could unlock demand, but income limits, regional price caps and developer contributions remain unsettled, leaving the eventual effect on volumes and margins uncertain. (Reuters)
Entain cuts growth after Brazil restrictions. Entain (ENT.L) lowered its 2026 constant-currency online net gaming revenue growth outlook Monday to 4–6%, from 5–7%, assuming Brazil’s provisional betting ban lasts through year-end. Underlying group EBITDA is now expected near the lower end of £910–960m and online margins near the bottom of 21–22%. The guidance illustrates how regulatory intervention can compress operating leverage even where the affected market contributes only modest profit. (Entain)
Evonik rejects reported BASF approach. Evonik (EVK.DE) rejected BASF’s approximately €10.3bn takeover approach as too low, Reuters reported Monday, citing people familiar with the matter. The indicated €22.15 per share offer follows the earlier disclosure of BASF’s interest. BASF said it would remain disciplined and needed engagement to verify synergies. The rejection sharpens the valuation gap; a higher proposal or credible standalone earnings improvement would be needed to resolve it. (Reuters / Dow Jones)
Rexel starts equity financing for GCG. Rexel (RXL.PA) launched an approximately €500m share placement Monday to help fund its previously announced acquisition of GCG. The accelerated bookbuild excludes shareholders’ preferential subscription rights and supports a target net-debt-to-EBITDA-after-leases ratio of about twice from 2027. The financing reduces reliance on debt but introduces dilution; the final issue price and share count will determine the immediate cost to existing holders. (Rexel)
Traders’ corner
Our Technical View
Price executed a retest and defense of its resistance-turned-support zone, printing a higher low within the emerging swing sequence.
The RSI remains in bearish territory, its steady upward trajectory toward the neutral 50-midline signals decaying downside momentum and a transition toward bullish velocity.
A decisive structural breach and daily close above the recent high pivot threshold will complete a bullish trend continuation pattern, opening path-of-least-resistance dynamics for an accelerated upward momentum expansion toward higher supply targets.
Our Technical View
Price rebounded from its previous low support zone, validated by the print of a hammer candlestick formation.
The RSI has crossed above its neutral 50-midline and continues to slope upward, signaling trend velocity acceleration.
The HK$5.28 pivot threshold represents the key overhead swing high resistance; a decisive daily close above HK$5.28 will complete a bullish accumulation pattern, opening path-of-least-resistance dynamics for a sustained upward expansion toward higher supply targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


