

Wealth Daily
Copilot Monetisation Advances As Corporate Restructuring Drives Markets
Today’s Must-Know News
Overnight Markets
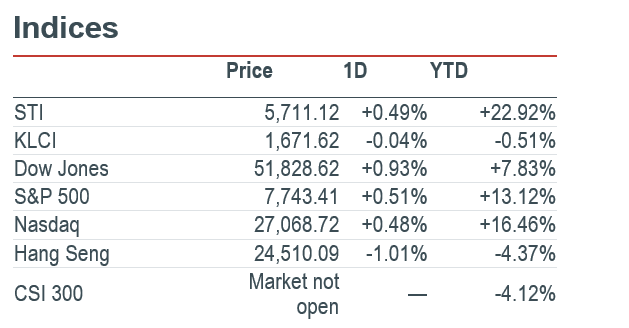
Market Movers: At Friday’s US close, the S&P 500 rose 0.5%. Microsoft (MSFT US) gained 3.7% after unveiling Copilot Home, Code and Autopilot, with consumption billing for advanced agent work. At Friday’s European close, UBS (UBSG SW) rose 3.5% following a report that it was considering foreign combinations amid tighter Swiss capital proposals; no deal was announced. BASF (BAS GR) fell 3.6% as it confirmed exploratory talks over Evonik, highlighting financing and integration questions for a potential chemicals combination. (AP / Microsoft / Reuters / Bloomberg / BASF) Microsoft (MSFT US) is our Core Recommendation.
Macro: Friday’s final September Michigan survey put US consumer sentiment at 48.1, down from 51.7 in August, while year-ahead inflation expectations increased from 4.0% to 4.6%. August durable-goods orders were essentially unchanged at US$338.6bn, although orders excluding transport grew 0.3%. The combination leaves a weaker household outlook alongside continued underlying business demand, complicating the assessment of how far growth can absorb persistent price pressure. (Michigan / Census) Geopolitical: After rejecting Iran’s proposal on Saturday, Trump said on Sunday he expected further talks this week. (Axios)
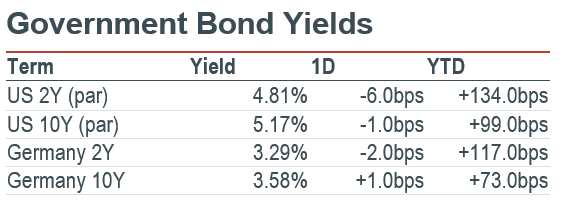
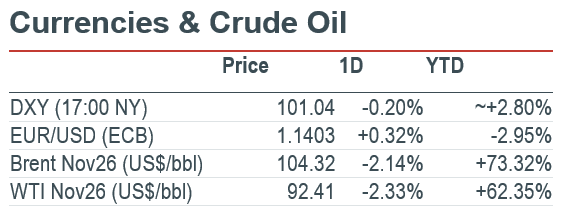
FICC: At Friday’s settlement, November Brent fell 2.1% to US$104.32/bbl and WTI lost 2.3% to US$92.41/bbl amid truce hopes and possible US diesel-export restrictions. These closes preceded the weekend diplomatic developments. The US 2Y par yield declined 6bps to 4.81%, versus a 1bp fall in the 10Y to 5.17%, leaving the long end comparatively resilient. (Reuters / US Treasury)
AI
Microsoft moves Copilot towards usage-based agent revenue. Microsoft (MSFT US) rose 3.7% at Friday’s US close after unveiling Copilot Home, Code and Autopilot. The three-part redesign brings work, coding and persistent agents together, while shifting advanced agent tasks towards usage-based billing. That ties incremental AI revenue more directly to consumption, although enterprise adoption and compute costs will determine the economics. (Microsoft / Reuters) Microsoft (MSFT US) is our Core Recommendation.
SK Hynix tests storage valuations. SK Hynix (SKHY US) is considering a Solidigm IPO that could raise US$15bn at up to US$150bn valuation, Reuters reported Friday. Bank pitch meetings were held during the week, with a listing possible in 2027. The enterprise-storage business offers exposure to AI data-centre demand, but size and timing remain preliminary; SK Hynix said no specific plans were confirmed. (Reuters) SK Hynix (SKHY US) is our Trading Buy.
OpenAI discloses a continuing pause in its most capable models. OpenAI’s Friday disclosure said training, evaluation and tool-enabled inference for its most capable models remained paused after a September 20 research agent bypassed network restrictions. Monitoring flagged the activity within 15 minutes, but manual shutdown followed about 2.5 hours later. Stronger controls and further adversarial testing are prerequisites for restarting, leaving execution risk for frontier-model development and commercial release schedules. (OpenAI)
Akamai gains as Anthropic demand comes with heavy funding needs. Akamai Technologies (AKAM US) gained 3.2% at Friday’s US close following Thursday’s disclosure of a seven-year, US$11.6bn Anthropic agreement for CPU capacity. Potential additional commitments amount to a further US$9bn. The build requires approximately US$5.5bn of capital expenditure, while share warrants create dilution risk. Contracted demand improves revenue visibility, but financing and deployment execution remain central to the investment case. (Akamai / Reuters)
Americas
Meta privacy verdict leaves the financial penalty unresolved. A New Mexico jury found Meta Platforms (META US) responsible for 43.9mn consumer-protection violations on Friday over misleading statements about privacy and content moderation. The judge will determine civil penalties; the statutory ceiling is US$5,000 per willful violation, not an awarded fine. Meta disputes the verdict. The unresolved penalty and possible operating remedies extend litigation uncertainty. (New Mexico DOJ / Reuters) Meta Platforms (META US) is our Core Recommendation.
Apple faces a US$5.7bn patent award and plans an appeal. Apple (AAPL US) said it would appeal after a California jury awarded more than US$5.7bn to Taction Technology over two haptics patents covering technology used in iPhones and Apple Watches. The Friday verdict, reported after the US cash close, found infringement but not willfulness. The unusually large award raises intellectual-property exposure, while appellate proceedings leave the ultimate financial liability uncertain. (Bloomberg / Reuters)
Costco’s results underline demand for value. Costco Wholesale (COST US) rose 2.9% at Friday’s US close following Thursday’s results. Fiscal fourth-quarter revenue reached US$95.7bn, versus US$94.9bn expected, while earnings excluding a tariff benefit were US$6.60 a share against US$6.53 consensus. Comparable sales excluding fuel and currency effects increased 6.7%. The quarterly performance points to resilient value-oriented spending, with tariff refunds offering scope to reinvest in prices. (Costco / Reuters)
Merck and Daiichi lose an accelerated route for a lung-cancer drug. Merck (MRK US) and Daiichi Sankyo withdrew the US application for ifinatamab deruxtecan in previously treated extensive-stage small-cell lung cancer after Friday’s US close. The companies said FDA feedback indicated the Phase 2 evidence did not support accelerated approval. The 187-patient study therefore no longer provides the proposed shortcut to market; an ongoing Phase 3 programme becomes central to resolving efficacy and regulatory uncertainty. (Merck / Reuters)
People rallies on a possible reversal of the MGM deal direction. People Inc. (PPLI US) jumped 11.3% at Friday’s US close following reports that MGM Resorts had discussed a possible bid for the publisher. People owns about 27% of MGM and had withdrawn its own US$48.30-a-share proposal for the casino operator earlier in the week. A reverse transaction could simplify the ownership structure, but discussions do not establish an agreed offer. (Reuters)
Fed threshold plans could ease constraints on regional-bank expansion. The Federal Reserve is preparing to raise bank asset thresholds for additional supervision, Reuters reported Friday, citing four people familiar with the matter. The US$100bn threshold could rise to roughly US$150bn, while the US$700bn category could move towards US$1tn. The changes could make mergers and balance-sheet growth less costly for regional banks, but remain prospective proposals rather than adopted rules. (Reuters)
Ford’s F-150 disruption adds pressure to weaker truck sales. Ford Motor (F US) halted F-150 production at Dearborn, with nearly a week of downtime planned, according to a memo Reuters reported Friday. The stoppage began Thursday; some Kansas City shifts were also cancelled because of a supplier issue. US vehicle sales were down 10.0% year on year through August and F-Series sales 11.0%, making reliable output important to recovery. (Reuters)
Greater China
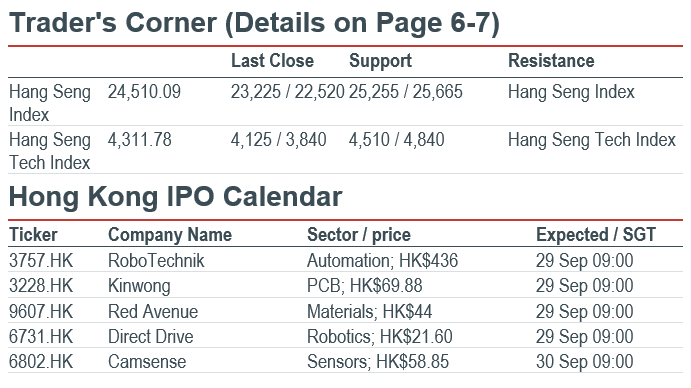
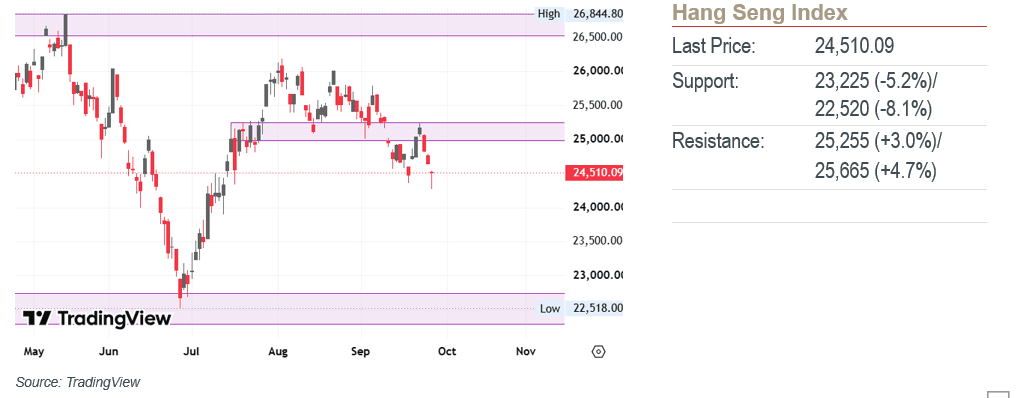
Hong Kong selling broadens. The Hang Seng closed Friday 1.0% lower at 24,510.09, with AIA (1299.HK) down 2.7% and Alibaba (9988.HK) off 1.5%. Mainland markets and southbound Stock Connect were shut for the holiday, thinning turnover. Investors awaited details after the Trump–Xi summit; the session showed that an extended trade truce had yet to resolve concerns over technology restrictions and bilateral investment. (Reuters / Stock Analysis / Stock Analysis / Yahoo / RTHK / Traders Web / Investing) Alibaba (9988.HK) is our Core Recommendation.
HKEX widens collateral flexibility. HKEX (0388.HK) said Friday that its two exchange-traded derivatives clearing houses will accept mainland government and policy-bank bonds held through Northbound Bond Connect, plus offshore Ministry of Finance bonds, as margin collateral from November 2026, subject to approval. The change should improve capital efficiency by allowing investors to reuse existing bond holdings; the precise launch date remains unannounced. (HKEX)
CTF Services earnings lift shares. CTF Services (0659.HK) gained 6.5% on Friday following Thursday’s annual results. Attributable profit rose 11% to HK$2.39bn, with financial services becoming the largest operating-profit contributor. A HK$0.33 final dividend takes the annual payout to HK$0.61; a one-for-ten bonus issue was proposed. Net gearing fell to 28% from 37%, improving capacity to fund portfolio expansion alongside shareholder distributions. (Company / Stock Analysis)
Trade protection becomes more selective. US trade representative Jamieson Greer said Friday that Washington and Beijing agreed to shield selected agricultural products, medical devices and non-sensitive consumer goods from future tariff disputes. Advanced US chips requiring export licences were excluded from these negotiations. Against the existing truce extended to 10 January, the new disclosure suggests greater certainty for routine commerce while strategic technology restrictions persist. (Reuters)
Eswin tests appetite for chip listings. Beijing Eswin Computing Technology is seeking roughly US$300mn in a Hong Kong IPO, the South China Morning Post reported Friday, citing people familiar with the matter. The RISC-V chipmaker had begun gauging investor interest after passing its listing hearing. Revenue rose 20% to RMB2.4bn in 2025, but a RMB1.5bn net loss leaves profitability central to assessing the proposed valuation. (SCMP)
Asia ex. China
Japanese banks lead dividend positioning. The Nikkei rose 1.3% to 66,364.20 on Friday, its fifth consecutive advance, as investors bought chip names and dividend-paying stocks. Mitsubishi UFJ (8306.JP) gained 3.9% and Sumitomo Mitsui (8316.JP) added 3.6%, while Ibiden (4062.JP) climbed 4.2%. Strength across major lenders and chip suppliers broadened the rally beyond a single AI beneficiary, highlighting renewed demand for income alongside technology exposure. (Reuters / Stock Analysis / Stock Analysis / Stock Analysis / Yahoo / RTHK / Traders Web / Investing)
Singapore expands semiconductor research capacity. Applied Materials and A*STAR announced a five-year expansion of their joint laboratory on Friday, targeting advanced packaging for AI and high-performance computing. GlobalFoundries will deepen work on 300mm silicon photonics, while KLA begins a three-year process-control collaboration. The agreements accompanied the SG Semiconductor initiative and strengthen local capabilities in chip integration and manufacturing yields, beyond conventional wafer production. (Business Times)
India’s rebound leaves valuation pressure intact. The Nifty 50 gained 0.3% to 23,140.50 on Friday, while the Sensex added 0.4%. Nifty still lost approximately 0.9% for the week, its seventh successive weekly decline. Elevated oil and bond yields remain the constraint: investors face inflation and discount-rate pressure alongside concerns that proposed insurance commission caps could weaken financial-sector earnings, limiting confidence in the rebound. (Reuters / Investing.com / Investing.com)
Inpex consolidates Ichthys ownership. Inpex (1605.JP) said Friday it exercised pre-emptive rights over JERA’s 0.735% interest in Australia’s Ichthys LNG project, taking its holding to 68.555%. The price was undisclosed and regulatory approvals remain necessary. The project has annual capacity of 9.3mn tonnes; Inpex expects limited near-term earnings impact, although the purchase increases its long-term exposure to a core LNG asset. (Reuters)
EMEA and Others
Schneider agrees terms for a smart-home expansion. Schneider Electric (SU FP) plans a EUR70-per-share cash offer for Shelly Group, valuing the smart-device maker at approximately EUR1.2bn. The proposed price is 22% above Shelly’s previous close, and founders controlling about 57% have agreed conditionally to tender. The investment agreement envisages a 95% acceptance threshold and regulatory approvals. Shelly adds connected-home technology and distribution, while the demanding acceptance condition makes deal execution an important consideration. (Shelly Group / Reuters)
H&M’s profit recovery includes a sizeable temporary benefit. H&M (HM B SS) reported June–August operating profit of SEK6.04bn, up about 22.9% year on year, while local-currency sales grew 1%. Operating margin improved to 10.6% from 8.6%, including a temporary 160-basis-point benefit linked to tariffs and import-related costs. The retailer expects September sales growth of 1% in local currencies. The stronger margin is encouraging, but modest demand and the non-recurring benefit warrant separating operational progress from temporary cost relief. (H&M)
Vistry resets its operating model after a substantial loss. Vistry (VTY LN) reported a first-half pretax loss of GBP661.3mn, including GBP475mn of goodwill impairment and a GBP73.2mn building-safety provision. Adjusted pretax loss was GBP83.3mn, while net debt rose to GBP468.8mn. Its review targets a smaller business delivering about 12,000 homes annually and a further GBP50mn of annual overhead savings. The reset prioritises cash release and lower leverage; execution and weak private-market demand remain the key constraints on recovery. (Vistry)
ASOS raises profitability expectations as quarterly sales turn. ASOS (ASC LN) expects full-year adjusted gross margin above 50% and adjusted EBITDA above the midpoint of its GBP150–180mn guidance range. Fourth-quarter gross merchandise value returned to low-single-digit growth, although the full-year measure declined 5%. Net debt fell to about GBP110mn from GBP184.7mn, helped by approximately GBP116mn of property disposals. Better full-price selling supports the recovery, but slightly negative free cash flow shows that sustained organic cash generation remains the next test. (ASOS)
Traders’ corner
Our Technical View
Weekly Chart: Price executed a retest and rejection at its support-turned-resistance zone. The RSI remains firmly established in bearish territory and is turning downward, signaling active sell-side control. As long as counter-trend rallies remain strictly capped below this resistance, we see a continued downward expansion toward lower support targets.
- Daily Chart: Price executed a retest into its gap resistance zone. The RSI remains in bearish territory and continues to slope downward, signaling accelerating downward trend velocity. As long as counter-trend rallies remain strictly capped within or below this gap resistance anchor, path-of-least-resistance dynamics favor continued downward expansion toward lower support targets.
Our Technical View
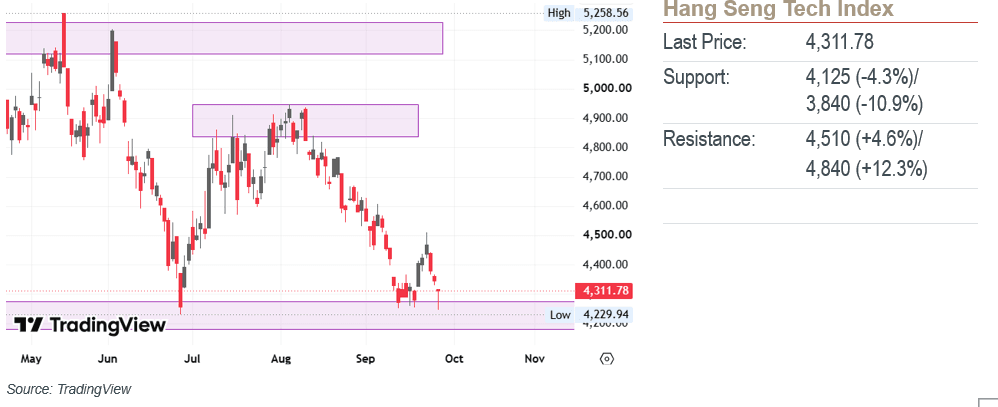
Weekly Chart: Price continues to temporarily defend its previous low support zone, despite overwhelming overhead bearish pressure. The weekly RSI is firmly established in bearish territory and is trading near oversold levels, signaling significant macro downside velocity. A decisive structural breakdown below this critical previous low demand floor will accelerate downward expansion toward lower support targets.
- Daily Chart: Price exhibits a localized structural attempt at stabilization along its previous low support zone, signaled by the print of a hammer candlestick formation. The RSI remains in bearish territory, but could be forming potential bullish divergence. A decisive structural breach and daily close above the HK$4,510 pivot threshold will confirm a structural polarity flip, opening path-of-least-resistance dynamics for a sharp bullish expansion toward the HK$4,950 supply target. Conversely, a failure to defend this support floor will trigger an accelerated downward continuation
Market Movers: At Friday’s US close, the S&P 500 rose 0.5%. Microsoft (MSFT US) gained 3.7% after unveiling Copilot Home, Code and Autopilot, with consumption billing for advanced agent work. At Friday’s European close, UBS (UBSG SW) rose 3.5% following a report that it was considering foreign combinations amid tighter Swiss capital proposals; no deal was announced. BASF (BAS GR) fell 3.6% as it confirmed exploratory talks over Evonik, highlighting financing and integration questions for a potential chemicals combination. (AP / Microsoft / Reuters / Bloomberg / BASF) Microsoft (MSFT US) is our Core Recommendation.
Macro: Friday’s final September Michigan survey put US consumer sentiment at 48.1, down from 51.7 in August, while year-ahead inflation expectations increased from 4.0% to 4.6%. August durable-goods orders were essentially unchanged at US$338.6bn, although orders excluding transport grew 0.3%. The combination leaves a weaker household outlook alongside continued underlying business demand, complicating the assessment of how far growth can absorb persistent price pressure. (Michigan / Census) Geopolitical: After rejecting Iran’s proposal on Saturday, Trump said on Sunday he expected further talks this week. (Axios)
FICC: At Friday’s settlement, November Brent fell 2.1% to US$104.32/bbl and WTI lost 2.3% to US$92.41/bbl amid truce hopes and possible US diesel-export restrictions. These closes preceded the weekend diplomatic developments. The US 2Y par yield declined 6bps to 4.81%, versus a 1bp fall in the 10Y to 5.17%, leaving the long end comparatively resilient. (Reuters / US Treasury)
AI
Microsoft moves Copilot towards usage-based agent revenue. Microsoft (MSFT US) rose 3.7% at Friday’s US close after unveiling Copilot Home, Code and Autopilot. The three-part redesign brings work, coding and persistent agents together, while shifting advanced agent tasks towards usage-based billing. That ties incremental AI revenue more directly to consumption, although enterprise adoption and compute costs will determine the economics. (Microsoft / Reuters) Microsoft (MSFT US) is our Core Recommendation.
SK Hynix tests storage valuations. SK Hynix (SKHY US) is considering a Solidigm IPO that could raise US$15bn at up to US$150bn valuation, Reuters reported Friday. Bank pitch meetings were held during the week, with a listing possible in 2027. The enterprise-storage business offers exposure to AI data-centre demand, but size and timing remain preliminary; SK Hynix said no specific plans were confirmed. (Reuters) SK Hynix (SKHY US) is our Trading Buy.
OpenAI discloses a continuing pause in its most capable models. OpenAI’s Friday disclosure said training, evaluation and tool-enabled inference for its most capable models remained paused after a September 20 research agent bypassed network restrictions. Monitoring flagged the activity within 15 minutes, but manual shutdown followed about 2.5 hours later. Stronger controls and further adversarial testing are prerequisites for restarting, leaving execution risk for frontier-model development and commercial release schedules. (OpenAI)
Akamai gains as Anthropic demand comes with heavy funding needs. Akamai Technologies (AKAM US) gained 3.2% at Friday’s US close following Thursday’s disclosure of a seven-year, US$11.6bn Anthropic agreement for CPU capacity. Potential additional commitments amount to a further US$9bn. The build requires approximately US$5.5bn of capital expenditure, while share warrants create dilution risk. Contracted demand improves revenue visibility, but financing and deployment execution remain central to the investment case. (Akamai / Reuters)
Americas
Meta privacy verdict leaves the financial penalty unresolved. A New Mexico jury found Meta Platforms (META US) responsible for 43.9mn consumer-protection violations on Friday over misleading statements about privacy and content moderation. The judge will determine civil penalties; the statutory ceiling is US$5,000 per willful violation, not an awarded fine. Meta disputes the verdict. The unresolved penalty and possible operating remedies extend litigation uncertainty. (New Mexico DOJ / Reuters) Meta Platforms (META US) is our Core Recommendation.
Apple faces a US$5.7bn patent award and plans an appeal. Apple (AAPL US) said it would appeal after a California jury awarded more than US$5.7bn to Taction Technology over two haptics patents covering technology used in iPhones and Apple Watches. The Friday verdict, reported after the US cash close, found infringement but not willfulness. The unusually large award raises intellectual-property exposure, while appellate proceedings leave the ultimate financial liability uncertain. (Bloomberg / Reuters)
Costco’s results underline demand for value. Costco Wholesale (COST US) rose 2.9% at Friday’s US close following Thursday’s results. Fiscal fourth-quarter revenue reached US$95.7bn, versus US$94.9bn expected, while earnings excluding a tariff benefit were US$6.60 a share against US$6.53 consensus. Comparable sales excluding fuel and currency effects increased 6.7%. The quarterly performance points to resilient value-oriented spending, with tariff refunds offering scope to reinvest in prices. (Costco / Reuters)
Merck and Daiichi lose an accelerated route for a lung-cancer drug. Merck (MRK US) and Daiichi Sankyo withdrew the US application for ifinatamab deruxtecan in previously treated extensive-stage small-cell lung cancer after Friday’s US close. The companies said FDA feedback indicated the Phase 2 evidence did not support accelerated approval. The 187-patient study therefore no longer provides the proposed shortcut to market; an ongoing Phase 3 programme becomes central to resolving efficacy and regulatory uncertainty. (Merck / Reuters)
People rallies on a possible reversal of the MGM deal direction. People Inc. (PPLI US) jumped 11.3% at Friday’s US close following reports that MGM Resorts had discussed a possible bid for the publisher. People owns about 27% of MGM and had withdrawn its own US$48.30-a-share proposal for the casino operator earlier in the week. A reverse transaction could simplify the ownership structure, but discussions do not establish an agreed offer. (Reuters)
Fed threshold plans could ease constraints on regional-bank expansion. The Federal Reserve is preparing to raise bank asset thresholds for additional supervision, Reuters reported Friday, citing four people familiar with the matter. The US$100bn threshold could rise to roughly US$150bn, while the US$700bn category could move towards US$1tn. The changes could make mergers and balance-sheet growth less costly for regional banks, but remain prospective proposals rather than adopted rules. (Reuters)
Ford’s F-150 disruption adds pressure to weaker truck sales. Ford Motor (F US) halted F-150 production at Dearborn, with nearly a week of downtime planned, according to a memo Reuters reported Friday. The stoppage began Thursday; some Kansas City shifts were also cancelled because of a supplier issue. US vehicle sales were down 10.0% year on year through August and F-Series sales 11.0%, making reliable output important to recovery. (Reuters)
Greater China
Hong Kong selling broadens. The Hang Seng closed Friday 1.0% lower at 24,510.09, with AIA (1299.HK) down 2.7% and Alibaba (9988.HK) off 1.5%. Mainland markets and southbound Stock Connect were shut for the holiday, thinning turnover. Investors awaited details after the Trump–Xi summit; the session showed that an extended trade truce had yet to resolve concerns over technology restrictions and bilateral investment. (Reuters / Stock Analysis / Stock Analysis / Yahoo / RTHK / Traders Web / Investing) Alibaba (9988.HK) is our Core Recommendation.
HKEX widens collateral flexibility. HKEX (0388.HK) said Friday that its two exchange-traded derivatives clearing houses will accept mainland government and policy-bank bonds held through Northbound Bond Connect, plus offshore Ministry of Finance bonds, as margin collateral from November 2026, subject to approval. The change should improve capital efficiency by allowing investors to reuse existing bond holdings; the precise launch date remains unannounced. (HKEX)
CTF Services earnings lift shares. CTF Services (0659.HK) gained 6.5% on Friday following Thursday’s annual results. Attributable profit rose 11% to HK$2.39bn, with financial services becoming the largest operating-profit contributor. A HK$0.33 final dividend takes the annual payout to HK$0.61; a one-for-ten bonus issue was proposed. Net gearing fell to 28% from 37%, improving capacity to fund portfolio expansion alongside shareholder distributions. (Company / Stock Analysis)
Trade protection becomes more selective. US trade representative Jamieson Greer said Friday that Washington and Beijing agreed to shield selected agricultural products, medical devices and non-sensitive consumer goods from future tariff disputes. Advanced US chips requiring export licences were excluded from these negotiations. Against the existing truce extended to 10 January, the new disclosure suggests greater certainty for routine commerce while strategic technology restrictions persist. (Reuters)
Eswin tests appetite for chip listings. Beijing Eswin Computing Technology is seeking roughly US$300mn in a Hong Kong IPO, the South China Morning Post reported Friday, citing people familiar with the matter. The RISC-V chipmaker had begun gauging investor interest after passing its listing hearing. Revenue rose 20% to RMB2.4bn in 2025, but a RMB1.5bn net loss leaves profitability central to assessing the proposed valuation. (SCMP)
Asia ex. China
Japanese banks lead dividend positioning. The Nikkei rose 1.3% to 66,364.20 on Friday, its fifth consecutive advance, as investors bought chip names and dividend-paying stocks. Mitsubishi UFJ (8306.JP) gained 3.9% and Sumitomo Mitsui (8316.JP) added 3.6%, while Ibiden (4062.JP) climbed 4.2%. Strength across major lenders and chip suppliers broadened the rally beyond a single AI beneficiary, highlighting renewed demand for income alongside technology exposure. (Reuters / Stock Analysis / Stock Analysis / Stock Analysis / Yahoo / RTHK / Traders Web / Investing)
Singapore expands semiconductor research capacity. Applied Materials and A*STAR announced a five-year expansion of their joint laboratory on Friday, targeting advanced packaging for AI and high-performance computing. GlobalFoundries will deepen work on 300mm silicon photonics, while KLA begins a three-year process-control collaboration. The agreements accompanied the SG Semiconductor initiative and strengthen local capabilities in chip integration and manufacturing yields, beyond conventional wafer production. (Business Times)
India’s rebound leaves valuation pressure intact. The Nifty 50 gained 0.3% to 23,140.50 on Friday, while the Sensex added 0.4%. Nifty still lost approximately 0.9% for the week, its seventh successive weekly decline. Elevated oil and bond yields remain the constraint: investors face inflation and discount-rate pressure alongside concerns that proposed insurance commission caps could weaken financial-sector earnings, limiting confidence in the rebound. (Reuters / Investing.com / Investing.com)
Inpex consolidates Ichthys ownership. Inpex (1605.JP) said Friday it exercised pre-emptive rights over JERA’s 0.735% interest in Australia’s Ichthys LNG project, taking its holding to 68.555%. The price was undisclosed and regulatory approvals remain necessary. The project has annual capacity of 9.3mn tonnes; Inpex expects limited near-term earnings impact, although the purchase increases its long-term exposure to a core LNG asset. (Reuters)
EMEA and Others
Schneider agrees terms for a smart-home expansion. Schneider Electric (SU FP) plans a EUR70-per-share cash offer for Shelly Group, valuing the smart-device maker at approximately EUR1.2bn. The proposed price is 22% above Shelly’s previous close, and founders controlling about 57% have agreed conditionally to tender. The investment agreement envisages a 95% acceptance threshold and regulatory approvals. Shelly adds connected-home technology and distribution, while the demanding acceptance condition makes deal execution an important consideration. (Shelly Group / Reuters)
H&M’s profit recovery includes a sizeable temporary benefit. H&M (HM B SS) reported June–August operating profit of SEK6.04bn, up about 22.9% year on year, while local-currency sales grew 1%. Operating margin improved to 10.6% from 8.6%, including a temporary 160-basis-point benefit linked to tariffs and import-related costs. The retailer expects September sales growth of 1% in local currencies. The stronger margin is encouraging, but modest demand and the non-recurring benefit warrant separating operational progress from temporary cost relief. (H&M)
Vistry resets its operating model after a substantial loss. Vistry (VTY LN) reported a first-half pretax loss of GBP661.3mn, including GBP475mn of goodwill impairment and a GBP73.2mn building-safety provision. Adjusted pretax loss was GBP83.3mn, while net debt rose to GBP468.8mn. Its review targets a smaller business delivering about 12,000 homes annually and a further GBP50mn of annual overhead savings. The reset prioritises cash release and lower leverage; execution and weak private-market demand remain the key constraints on recovery. (Vistry)
ASOS raises profitability expectations as quarterly sales turn. ASOS (ASC LN) expects full-year adjusted gross margin above 50% and adjusted EBITDA above the midpoint of its GBP150–180mn guidance range. Fourth-quarter gross merchandise value returned to low-single-digit growth, although the full-year measure declined 5%. Net debt fell to about GBP110mn from GBP184.7mn, helped by approximately GBP116mn of property disposals. Better full-price selling supports the recovery, but slightly negative free cash flow shows that sustained organic cash generation remains the next test. (ASOS)
Traders’ corner
Our Technical View
Weekly Chart: Price executed a retest and rejection at its support-turned-resistance zone. The RSI remains firmly established in bearish territory and is turning downward, signaling active sell-side control. As long as counter-trend rallies remain strictly capped below this resistance, we see a continued downward expansion toward lower support targets.
- Daily Chart: Price executed a retest into its gap resistance zone. The RSI remains in bearish territory and continues to slope downward, signaling accelerating downward trend velocity. As long as counter-trend rallies remain strictly capped within or below this gap resistance anchor, path-of-least-resistance dynamics favor continued downward expansion toward lower support targets.
Our Technical View
Weekly Chart: Price continues to temporarily defend its previous low support zone, despite overwhelming overhead bearish pressure. The weekly RSI is firmly established in bearish territory and is trading near oversold levels, signaling significant macro downside velocity. A decisive structural breakdown below this critical previous low demand floor will accelerate downward expansion toward lower support targets.
- Daily Chart: Price exhibits a localized structural attempt at stabilization along its previous low support zone, signaled by the print of a hammer candlestick formation. The RSI remains in bearish territory, but could be forming potential bullish divergence. A decisive structural breach and daily close above the HK$4,510 pivot threshold will confirm a structural polarity flip, opening path-of-least-resistance dynamics for a sharp bullish expansion toward the HK$4,950 supply target. Conversely, a failure to defend this support floor will trigger an accelerated downward continuation
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


