

Analyst
Wendy Chen
wendy.chen@uobkh.comAnalyst
Wang Qi, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Key US Market Indices
Index | Price | Past 2-Week Return | YTD Return |
S&P 500 | 7,743 | 1.1% | 13.1% |
Dow Jones Industrial Average | 51,829 | -1.4% | 7.8% |
Nasdaq Composite | 27,069 | 2.8% | 16.5% |
Source: UOB Kay Hian and iFinD, as of September 28, 2026.
- First rate hike in three years. Post hotter-than-expected CPI inflation and employment print for August, the Fed raised rates by 25bps in September – its first hike in over three years, validating our top prediction of the Fed Wildcard in 2026. The FOMC’s hawkish stance underscores Chair Warsh's determination to restore Fed credibility amid persistent inflation and market complacency.
- Focus on the terminal rate. The stock market response has been volatile yet relatively measured (see below). Now the shoe has dropped, investors have likely shifted their focus to the length of the tightening cycle, namely the terminal rate and how long the Fed will remain restrictive. Inflation, particularly oil-driven inflation, will be key to answering both questions. We’ll therefore continue to monitor the oil-Iran nexus closely.
- Nasdaq leads; market divergence widens. Following the Fed rate hike, US equities posted mixed performance over the past two weeks. The tech-heavy Nasdaq Composite led with a 2.8% gain, while the Dow Jones retreated 1.4%. The S&P 500 managed a modest 1.1% gain, pushing its YTD return to 13.1%. This divergence reflects the ongoing rotation back into AI-driven megacaps and growth names, while higher rates weigh on value and cyclical stocks. It seems that strong AI-related earnings are overriding macro headwinds – at least for now – effectively acting as a “sorting mechanism”.
- 3Q earnings season: the sorting mechanism at work. Despite S&P’s double-digit YTD return, its forward P/E multiple has compressed from 22x to 19x this year. This multiple contraction reflects higher costs of capital (10Y yields touching 5.2%), AI disruption fears (lower valuation for software), and robust earnings growth among core AI companies. The sorting mechanism mentioned above could become even more evident during the upcoming earnings season, as investors increasingly reward perceived AI winners and companies with strong earnings momentum.
- Must-read: Our Leading Investor Signals cover Trump’s latest trades on page 4.
- Best performing sectors: Info Tech (XLK) +4.7%, Health Care (XLV) +3.6%, Communication Services (XLC) +0.7%.
- Potential movers and shakers:
Positive | Meta (META), AMD (AMD), Intel (INTC), Netflix Inc (NFLX), Walt Disney (DIS), Eli Lilly & Co. (LLY), AbbVie Inc. (ABBV), Berkshire Hathaway Class B (BRK/B), Micron (MU US) |
Neutral | Verizon Communications Inc (VZ), Tesla (TSLA US), Louis Vuitton Moët Hennessy (MC FP/LVMUY US), On Holding AG (ONON US), Nike (NKE US) |
Negative | McDonald’s (MCD US) |
- Must Watch Events: US Sep Labour Data (Oct 2), US Sep CPI/PPI data (Oct 14). Earnings: MU (Sep 30), JPM (Oct 13), ASML (Oct 14), TSM (Oct 16), MSFT (est Oct 29), META (est Oct 29), GOOGL (est Oct 29), LLY (Oct 29). Details below.
Date | Macro Data | Sector / Company Events |
Sep 30 |
| Earnings: MU |
Oct 1 | Initial Jobless Claims, S&P Sep PMI-Mfg Final | Earnings: NKE |
Oct 2 | US Sep Labor data (NFP/ Unemployment Rate), |
|
Oct 5 | S&P Sep PMI-Svcs Final |
|
Oct 6 | US Aug Exports & Imports |
|
Oct 8 | Initial Jobless Claims | TSMC September Monthly Sales. |
Oct 13 |
| Semicon West (till Oct 15). |
Oct 14 | US Sep CPI | Earnings: BAC, ASML NA |
Oct 15 | Initial Jobless Claims, US Sep PPI, US Sep Retail Sales, New Yuan Loans, Outstanding Loan Growth, Total Social Financing, |
|
Oct 16 | US Sep Capacity Utilisation | Earnings: TSM est |
Oct 20 |
| Earnings: NFLX, VZ est |
Oct 21 |
| Earnings: IBM, KO est, |
Oct 22 | Initial Jobless Claims | Earnings: NOK, PG est, TSLA est |
Oct 23 | S&P Global PMI-Mfg & Svcs Flash. | Oracle AI World Tour (till Oct 28). |
Oct 26 |
|
|
Oct 27 | US Aug House Price Index | Earnings: PYPL, UPS est |
Oct 28 |
| European Central Bank interest rate decisions (till Oct 29). |
Oct 29 | Initial Jobless Claims, Fed Interest Rate Decision, US 3Q GDP, US Sep Personal Income/Spending, US Sep PCE | Bank of Japan rate decision (till Oct 30). |
Leading Investor Signals
One of our key messages is that Trump moves markets, and so do influential leaders such as Nvidia CEO Jensen Huang and Tesla’s Elon Musk. Their words and actions often draw attention to specific investments, shape investor sentiment and drive short-term price swings across markets. It is important to track such signals to understand where investor focus is shifting, how market narratives may evolve, and what potential risks and opportunities lie ahead. We hope you find such insights useful.
President Trump’s Trade Disclosures
Trump’s July 2026 disclosures showed the largest net purchases in the Vanguard Dividend Appreciation ETF (VIG) and iShares Russell 1000 ETF (IWB), at USD 1.0-5.0mn each. Other net buys include Home Depot (HD; USD 0.25–0.56mn), Mastercard (MA; USD 0.02-0.26mn), UnitedHealth (UNH; USD 0.09-0.25mn) and Apple (AAPL; up to USD 0.03mn). The largest net sales were Microsoft (MSFT; USD 6.1-30.9mn) and Amazon (AMZN; USD 5.2-25.5mn), both of which are our Core Recommendations.
President Trump’s net reported trading activities for July 2026
Stock / ETF Name | Ticker | GICS Sector | Buy Trades | Aggregate Buy range | Sell Trades | Aggregate Sell range | Net direction | Possible net range |
Vanguard Dividend Appreciation ETF | VIG | — | 1 | USD 1.0–5.0 mn | 0 | — | Net buy | USD 1.0–5.0 mn |
iShares Russell 1000 ETF | IWB | — | 1 | USD 1.0–5.0 mn | 0 | — | Net buy | USD 1.0–5.0 mn |
Home Depot | HD | Consumer Discretionary | 3 | USD 0.27–0.56 mn | 1 | USD 0.00–0.01 mn | Net buy | USD 0.25–0.56 mn |
Mastercard | MA | Financials | 3 | USD 0.12–0.32 mn | 1 | USD 0.05–0.10 mn | Net buy | USD 0.02–0.26 mn |
UnitedHealth | UNH | Health Care | 1 | USD 0.10–0.25 mn | 1 | USD 0.00–0.01 mn | Net buy | USD 0.09–0.25 mn |
Apple | AAPL | Information Technology | 2 | USD 0.00–0.03 mn | 0 | — | Net buy | USD 0.00–0.03 mn |
Meta | META | Communication Services | 3 | USD 0.12–0.32 mn | 5 | USD 0.25–0.63 mn | Need exact transaction amount | Net sell USD 0.51mn to net buy USD 0.06mn |
Visa | V | Financials | 2 | USD 0.20–0.50 mn | 1 | USD 0.25–0.50 mn | Need exact transaction amount | Net sell USD 0.30mn to net buy USD 0.25mn |
Palantir | PLTR | Information Technology | 2 | USD 0.02–0.07 mn | 3 | USD 0.02–0.08 mn | Need exact transaction amount | Net sell USD 0.06mn to net buy USD 0.05mn |
Microsoft | MSFT | Information Technology | 3 | USD 0.17–0.40 mn | 6 | USD 6.5–31.1 mn | Net sell | USD 6.1–30.9 mn |
Amazon | AMZN | Consumer Discretionary | 2 | USD 0.00–0.03 mn | 3 | USD 5.3–25.5 mn | Net sell | USD 5.2–25.5 mn |
Modine Manufacturing | MOD | Consumer Discretionary | 0 | — | 0 | — | No trades | — |
Vanguard S&P 500 ETF | VOO | — | 0 | — | 0 | — | No trades | — |
Source: OGE. Aggregate ranges are calculated by summing the lower and upper bounds of the reported transactions. The possible net range compares minimum purchases with maximum sales and maximum purchases with minimum sales. A net direction is assigned only when the entire resulting range is either positive or negative
Best 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLK.P | Information Technology | 4.7% | 36.8% | Arista Networks, Inc. (ANET) +3.5%, Keysight Technologies, Inc. (KEYS) +6.9%, Servicenow, Inc. (NOW) +2.3% |
XLV.P | Health Care | 3.6% | 11.6% | Eli Lilly And Company (LLY) +6.1%, Thermo Fisher Scientific Inc. (TMO) +10.8%, Danaher Corporation (DHR) +12.2% |
XLC.P | Communication Services | 0.7% | -3.2% | Live Nation Entertainment, Inc. (LYV) +0.4%, The Walt Disney Company (DIS) -0.4%, Tko Group Holdings, Inc. (TKO) -3.6% |
Source: UOB Kay Hian and iFinD, as of September 28, 2026.
- Information Technology led with a 4.7% gain over the last two weeks, lifting its YTD return to 36.8%. Arista Networks (ANET) rose 3.5%, Keysight Technologies (KEYS) gained 6.9% and ServiceNow (NOW) advanced 2.3%. Gains across networking, electronic testing and enterprise software suggest continued optimism in AI-related names beyond semiconductors. The upcoming 3Q earnings seasons will help determine whether such gains are sustainable.
- Health Care gained 3.6% in two weeks, lifting its YTD return to 11.6%. Eli Lilly (LLY) rose 6.1%, as its new research collaboration and manufacturing investment support longer-term pipeline and supply outlook. Thermo Fisher Scientific (TMO) and Danaher (DHR) surged 10.8% and 12.2%, respectively. Stronger performance of these two life-science tools stocks warrants a separate test of whether customer orders are recovering. Lilly remains our Core Recommendation, while the Health Care Select Sector SPDR Fund (XLV.P) is a Trading Buy.
- Communication Services edged up 0.7% over the past two weeks, narrowing its YTD decline to 3.2%. Live Nation Entertainment (LYV) gained 0.4%, while Walt Disney (DIS) slipped 0.4% and TKO Group (TKO) fell 3.6%. Disney’s streaming price increases could improve revenue per subscriber, although viewer retention remains a key risk.
Worst 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLF.P | Financials | -3.9% | 1.4% | Bank Of America Corporation (BAC) -9.6%, Jpmorgan Chase & Co. (JPM) -3.7%, The Goldman Sachs Group, Inc. (GS) -9.1% |
XLE.P | Energy | -4.2% | 41.5% | Chevron Corporation (CVX) -4.5%, Exxonmobil Holdings Corporation (XOM) -3.3%, Conocophillips (COP) -7.3% |
XLU.P | Utilities | -6.1% | -5.5% | Nextera Energy, Inc. (NEE) -7.6%, The Southern Company (SO) -4.9%, Duke Energy Corporation (DUK) -5.1% |
Source: UOB Kay Hian and iFinD, as of September 28, 2026.
- Financials fell 3.9% in two weeks, reducing its YTD gain to 1.4%. Amid AI disruption fears, Bank of America (BAC) dropped 9.6%, JPMorgan Chase (JPM) declined 3.7% and Goldman Sachs (GS) lost 9.1%. Bank of America signaled weaker investment-banking fees and broadly flat trading revenue, while Goldman Sachs pointed to softer fixed-income trading and higher expenses.
- Energy declined 4.2% over two weeks, trimming its YTD gain to 41.5%. Chevron (CVX) fell 4.5%, Exxon Mobil (XOM) declined 3.3% and ConocoPhillips (COP) lost 7.3%. Softer crude prices weighed on producers after the sector’s strong YTD advance. Oil-price direction is now the clearest near-term test for producer cash flows. The Energy Select Sector SPDR Fund (XLE.P) remains our Core Recommendation.
- Utilities was the worst-performing sector, down 6.1% over two weeks and down another 5.5% YTD. NextEra Energy (NEE) lost 7.6%, Southern Company (SO) fell 4.9% and Duke Energy (DUK) declined 5.1%. Rising Treasury yields has reduced the appeal of dividend-paying utility stocks while raised concerns about their financing costs. Stable electricity demand and AI-driven growth offered little protection against this rate-based repricing.
Stocks: Potential Movers and Shakers
Stock | Sector | Type of Events | Our Take |
AbbVie Inc. (ABBV) | Health Care | Corporate Action | Slightly Positive |
- Parkinson’s FDA Approval. The FDA approved AbbVie’s once-daily Parkinson’s treatment Juvmo (tavapadon), acquired through its USD 8.7bn Cerevel acquisition. Late-stage trials showed improved symptoms, while AbbVie continues to target over USD 5bn in combined Parkinson’s sales, although initial uptake may be gradual as Medicare coverage is negotiated.
- Singapore Manufacturing Expansion. AbbVie’s USD 223mn Singapore expansion adds 24,000 liters of biologics drug-substance capacity, supporting existing products and its immunology and oncology pipeline. The facility is expected to become operational in 2026, strengthening AbbVie’s Asian manufacturing footprint and global biologics capacity.
- Key Takeaways. Juvmo’s approval validates AbbVie’s strategy of using acquisitions to diversify beyond its core immunology franchise and strengthens its exposure to neuroscience, a key growth pillar. Separately, the Singapore expansion provides additional capacity to support future biologics launches, helping reduce supply constraints as AbbVie advances a broader pipeline across immunology and oncology.
- Constructive Outlook. We become increasingly constructive on AbbVie as new product approvals broaden its growth drivers, while expanded biologics capacity supports future pipeline commercialisation and longer-term earnings growth. (Tang Kai Jie)
Stock | Sector | Type of Events | Our Take |
Berkshire Hathaway Class B (BRK/B) | Multiple Industries | Channel Checks | Positive |
- BRK could further increase investments in Japan’s five major trading houses: Mitsubishi, Mitsui, Itochu, Marubeni and Sumitomo. CEO Greg Abel signalled that additional purchases were under consideration in Sep 2026, reinforcing the long-term strategy established by Warren Buffett. Existing agreements allow BRK to exceed the 10% ownership ceiling. The holdings were worth USD 35.4b as of end-2025 against a cost of USD 15.4b and generated USD 862m in annual dividends. Its yen borrowings broadly match the investment cost and carry an average interest rate of just 1.2%.
- Proactive approach to deploy the enormous cash reserves. Under new CEO Greg Abel, BRK has accelerated capital allocation through a combination of equity purchases, acquisitions, and share repurchases. The most notable investment was a substantial increase in its Alphabet position to 106m shares as of June 2026, which is now the third-largest equity position estimated at USD 38bn. BRK has resumed share repurchases in 2Q2026, spending USD 4.5b on buybacks. The acceleration in buybacks coincided with BRK becoming a net buyer of equities at USD 20bn for the first time in 14 quarters.
- BRK’s subsidiary Precision Castparts produces intricate components for the high-temperature sections of aircraft engines and industrial gas turbines using nickel- and cobalt-based alloys. The subsidiary was recently acquired by GE Aerospace for USD 11.8b (26x projected 2027 EBITDA). The deal highlights the strategic value of Precision Castparts’ specialised aerospace casting capacity. Precision Castparts is a growing contributor to BRK’s manufacturing earnings. Its pre-tax earnings rose 34.2% in 2025 and 33.6% yoy in 1H2026.
- Defensive shelter from market volatility amid macro uncertainty. BRK/B trades at 2026 PE of 24.5x and P/B of 1.45x. Buy BRK due to its diversified earnings and cash-rich balance sheet. The stock remains our Core Recommendation amid the uncertain macro environment. (Jonathan Koh)
Stock | Sector | Type of Events | Our Take |
Eli Lilly & Co. (LLY) | Health Care | Corporate Action | Positive |
- China R&D Collaboration. Eli Lilly entered into a research collaboration with InnoCare Pharma worth up to USD 3.35bn. InnoCare will leverage its drug discovery platform to identify and advance compounds against up to five targets, with Lilly gaining access to potential new assets across areas including oncology and autoimmune diseases.
- US Manufacturing Expansion. Lilly broke ground on a USD 6.5bn manufacturing facility in Houston, forming part of its broader USD 50bn domestic manufacturing investment programme. The plant will manufacture APIs for Foundayo (orforglipron), its oral GLP-1 obesity treatment, alongside other small-molecule medicines and advanced therapeutics.
- Strengthening Pipeline and Supply Capacity. The InnoCare partnership expands Lilly’s early-stage discovery pipeline without requiring the company to build all capabilities internally, while the Houston facility strengthens manufacturing capacity ahead of expected growth across its obesity and broader pharmaceutical portfolio. The highly automated plant should also support manufacturing efficiency and supply-chain resilience.
- Constructive Long-Term Outlook. We remain constructive on LLY as pipeline diversification and continued manufacturing investment support longer-term growth beyond its existing GLP-1 franchise. LLY is our Core Recommendation. (Tang Kai Jie)
Stock | Sector | Type of Events | Our Take |
Louis Vuitton Moët Hennessy (MC FP/LVMUY US) | Consumer Discretionary | Corporate Action | Neutral |
- LVMH set to join Armani minority stake talks. Armani is scheduled to hold formal talks in late Sept or early Oct with LVMH, L'Oreal and EssilorLuxottica over the sale of an initial 15% stake, as instructed in the will of the late Giorgio Armani. One option discussed informally would split the stake across all three, according to the Financial Times.
- LVMH has expressed interest, but people familiar with the matter said it is not an obvious fit, as Armani generates a significant share of sales at lower price points than LVMH's core brands and is weighted more towards fashion than higher-margin accessories. Longstanding ties between the Arnault family and the late designer remain an important factor.
- Valuation may prove a stumbling block, with Armani-side parties floating about EUR 10bn against investors’ assessment of EUR 3-7bn. Armani's revenue fell 2.8% yoy to EUR 2.19bn in 2025, following a 5% decline in 2024. A stock market listing remains the fallback option. (Ejann Hiew)
Stock | Sector | Type of Events | Our Take |
McDonald’s (MCD US) | Consumer Discretionary | Investor Roadshow | Negative |
- Expects inflation and flat traffic to persist. At its investor day on Sep 23, CEO Chris Kempczinski told CNBC that management should stop describing the environment as difficult and accept it as the norm, adding that no change is expected. He noted that inflation is sticky globally and that beef costs have nearly doubled over five years in its largest markets. Price increases by McDonald’s will likely be considered, but the company will be careful not to drive diners away, having acknowledged the mistake of raising prices too quickly after the pandemic.
- Heavy capex to support franchisee upgrades. The company plans to spend up to USD 8.5bn through 2036 to accelerate franchisee investment, including USD1.5-2bn of incremental capex in 2027-2030 on top of about USD 3bn of annual capex. Franchisees face incremental costs of roughly USD 800,000 per restaurant on top of a USD 400,000-450,000 standard remodel, while beef and labour costs already weigh on profits. Looking ahead, management targets an operating margin in the low-to-mid 50% range by 2030 (vs 46.1% in 2025) and a payback of about four years for franchisees.
- McDonald's targets share gains in chicken and beverages. In chicken, the company holds about 20% of the USD130 bn global category, while in beverages it holds roughly 10% of the USD 230bn global category and is the second-largest coffee player worldwide. Looking ahead, management aims to raise its global shares in both chicken and beverages by about 1.5ppt each by 2030, supported by US pilots of hand-breaded chicken, new grilled chicken sandwiches and wraps, and new McNuggets flavours and sauces, along with new espresso machines and alternative milk options coming to US restaurants and more new drinks internationally. Beef remains a core focus, with about 40% share of the USD 50bn global category and fresh beef Quarter Pounders to be extended to more markets outside the US.
- Valuation supports long-term accumulation despite near-term caution. Following the news, the shares fell 5% and the Bloomberg consensus price target fell 4% to USD 302.36. McDonald's next-twelve-month forward PE of 17.36x is below the S&P 500's 19.17x, and its PE relative to the SPY is at a 10-year low. We see this as a long-term accumulation opportunity for a quality stock affected by current macro headwinds. (Ejann Hiew)
Stock | Sector | Type of Events | Our Take |
Meta (META) AMD (AMD) Intel (INTC) | Information Technology | Sales / Products | Positive |
- Meta’s personal AI agent Muse claimed the No. 1 spot among free apps on Apple's US App Store, overtaking OpenAI’s ChatGPT. Muse’s early success validates Meta’s structural advantages in consumer AI, powered by its unparalleled social media platform and distribution network.
- While near-term financial impact is limited, Muse unlocks a massive new addressable market, with the potential to deliver ~USD 29bn in incremental revenue by 2030 (~12% of Meta's 2026 revenue). Competition also remains intense, as OpenAI will introduce its agentic product this week, followed by similar products from Google and others.
- Muse has sparked a strong rally in CPU-related names (AMD, ARM, Intel), as faster AI agent adoption drives incremental demand for CPUs. However, we recommend caution on the CPU industry, as AI agent development is still nascent and recent share price gains may be running ahead of fundamentals (see below).
- Assuming that 500mn users globally would adopt Muse-like AI agents in the medium term, the incremental CPU demand amounts to only USD 4bn in value, roughly 4% of the overall USD 100bn TAM. Meanwhile, the combined market cap of CPU stocks has already increased by USD 300-400bn in the last two weeks, suggesting the market may be overly optimistic. (Garrick Li)
Stock | Sector | Type of Events | Our Take |
Micron (MU US) | Information Technology | Earnings | Positive |
- Micron reports Aug quarter earnings on September 30 EST (October 1 Hong Kong time). Visible Alpha estimates its revenue to grow 349.5% yoy and 22.7% qoq to USD 51bn, while consensus looks for gross margin to expand 42.1ppt yoy and 2.2ppt qoq to 86.8%, and EPS to grow 1,002.1% yoy and 24.3% qoq to USD 31.52.
- For the Nov quarter, Visible Alpha expects revenue to grow another 319.7% yoy and 12.6% qoq to USD 57bn. Consensus has gross margin expanding 31.5ppt yoy and 0.7ppt qoq to 87.5%, and EPS growing 675.9% yoy and 11.8% qoq to USD 35.15.
- The sell side brokers expect Micron's DRAM ASPs to increase 20-25% qoq and NAND ASP 22.5-34% qoq in the Aug quarter, moderating to around 13% and 15% respectively in the Nov quarter. This compares to TrendForce’s estimates for 3Q2026 at +13-18% for conventional DRAM and +10-15% for NAND.
- Four items that could move MU shares: (1) pricing levels on any new strategic customer agreements, (2) share repurchase plans now that the CHIPS Act restrictions lift on December 9, (3) gross margins guidance in 2027 (preferably at mid-80s), and (4) the HBM roadmap covering market share, HBM4 shipments and yields, as well as HBM4E sampling. Market may also look for comments on competition from China. Micron is our Trading Buy. (Johnny Yum)
Stock | Sector | Type of Events | Our Take |
Netflix Inc (NFLX) | Communication Services | Sales / Products | Positive |
- Advertising expansion strengthens monetisation. Netflix hosted UK Upfront on Sep 24, highlighting that its ad-supported plan has reached over 14m viewers in the country. Netflix also announced that its ad tier will expand to nine additional EMEA markets starting March 2027, while planning to enhance its Ads Suite with broader demographic targeting Pause Ads. The larger addressable audience and improving ad-tech capabilities should support continued Netflix’s advertising revenue growth.
- Live programming broadens Netflix’s entertainment offering. Netflix has the exclusive right to live-stream STARTO ENTERTAINMENT’s New Year’s Eve countdown concert worldwide on Dec 31, and confirmed the Tyson Fury–Anthony Joshua boxing match in December 2026. The continued expansion into live music and sports should help differentiate its platform, increase viewing and create new advertising and sponsorship opportunities.
- Children’s content expansion strengthens family appeal. Netflix also announced an extension of its “Sesame Street” agreement through Season 62, with a new film in development, alongside additional series from the “Gabby’s Dollhouse” franchise. With kids and family content now accounting for 15% of total viewing hours in 1H2026, expanding familiar titles should encourage repeat viewing and strengthen Netflix’s value to family subscribers, supporting retention.
- Positive on long-term earnings growth. We remain positive on Netflix as continued expansion of its advertising capabilities, growing live programming slate and investment in family content should support engagement and monetisation. A broader ad-supported audience and improving ad-tech tools provide further upside to advertising revenue, while differentiated live events should strengthen retention. These drivers should help drive long-term earnings growth and margin expansion. (Shaina Mahtani)
Stock | Sector | Type of Events | Our Take |
On Holding AG (ONON US) Nike (NKE US) | Consumer Discretionary | Corporate Action | Neutral |
- On Holding signs Kylian Mbappé as it launches into football. On announced its entry into football on Sep 18, signing French superstar Kylian Mbappé after Nike chose not to renew his contract upon its expiry in July, according to CNBC. Mbappé will work directly with On's product teams to develop and test future football footwear and apparel, while also serving as a global brand ambassador whose role will extend beyond football into movement, performance and design. On also plans to apply its proprietary LightSpray robotic manufacturing technology, first introduced in 2024, to the development of elite football footwear.
- Short-term catalyst, but we remain cautious. On Holding shares rose 8% from a low of USD 27 following the news, while Nike shares were unchanged. Meanwhile, macro conditions have progressively worsened, with a second Fed rate hike expected in Oct and a prolonged Middle East conflict. While the signing has had an immediate impact on ON shares, we expect any material contribution to its outlook to emerge only at a later date. We therefore expect the shares to remain range-bound at USD 27-37 over the medium term, supporting our cautious view on the stock given the challenging macro environment for consumers. (Ejann Hiew)
Stock | Sector | Type of Events | Our Take |
Tesla (TSLA US) | Consumer Discretionary | Sales / Products | Neutral |
- Tesla's Semi entered volume production seven years late; autonomy moved backwards.
- Positives: The Sparks, Nevada plant opened on Sep 24 with capacity of 50,000 trucks a year, and deliveries began for PepsiCo, DHL and US Foods. Alliance ZET SCALE named Tesla primary supplier for 2,500 trucks, nearly doubling the US electric Class 8 fleet. Optimus output rose roughly tenfold from 2Q2026 to several hundred a week, targeting over 1,000 by year-end. As a result, TSLA gained 1.8% to USD 372.11.
- Negatives: Only eight of the 476 robotaxis registered in Texas were active in Austin last week. The last issue's 200 referred to registrations, not deployment figures. NHTSA ordered Tesla on Sep 10 to show under oath that the Cybercab is legal to sell, and the EU postponed its Full Self-Driving vote to December. Optimus assembly still shows fragile hands and supplier quality problems. China discounting resumed on Sep 25, with price reductions of RMB 5,000 on Model 3 and RMB 7,000 on selected Model Y, the second cut in a month.
- We remain Neutral on Tesla. The Semi adds a second product line with orders behind it. However, autonomy, which has been supporting the valuation, went backwards on deployment and approval. Watch 3Q2026 deliveries, the October 1 Roadster reveal and China’s Sep retail numbers as potential stock catalysts. (Ken Lee)
Stock | Sector | Type of Events | Our Take |
Verizon Communications Inc (VZ) | Communication Services | Sales / Products | Neutral |
- New device promotions support subscriber acquisition and retention. Verizon expanded its premium device offering during the period, with the iPhone 18 Pro lineup becoming widely available, alongside new Motorola foldable devices. Promotions include annual iPhone upgrades under its Simplicity plan and trade-in discounts of up to USD 1,100 on selected plans. Competitive offers should support customer additions and retention, although subsidies could weigh on near-term margins.
- AI investment expands support for workers and small businesses. Verizon announced a USD 70m AI skills initiative on Sep 23, comprising USD 50m in new funding and an existing USD 20m fund for departing employees. The programme provides free training through technology and community partners. The initiative could strengthen relationships with small businesses and communities, although its direct contribution to near-term revenue and earnings is likely to be limited.
- Neutral as subscriber support is balanced by limited near-term earnings upside. We remain neutral on Verizon as competitive device promotions should support customer acquisition and retention, while its AI skills initiative may strengthen engagement with small businesses. However, the direct earnings contribution from these initiatives is likely to be modest, while promotional costs, competitive pressures and elevated investment requirements continue to limit near-term upside. (Shaina Mahtani)
Stock | Sector | Type of Events | Our Take |
Walt Disney (DIS) | Communication Services | Sales / Products | Positive |
- Streaming price increases support monetisation. Disney’s US pricing changes reported on Sep 23 raise standalone ad-free Disney+ and Hulu subscriptions by USD 2.50 to USD 21.49 per month. The ad-free bundle has also increased to USD 21.99, while the ad-supported bundle remains at USD 12.99. Higher pricing should support revenue per subscriber and encourage bundle adoption, although affordability concerns could weigh on retention.
- Marvel re-release demonstrates continued franchise appeal. Disney reported that “Avengers Endgame: Encore” opened at No.1 globally with an estimated USD 86mn, including USD 26mn domestically and USD 60mn internationally. The release pushed Marvel Studios’ cumulative box-office takings above USD 35bn across 38 films. Strong demand for established titles highlights opportunities to generate additional theatrical revenue and build interest ahead of “Avengers: Doomsday”.
- Expanded podcast offering supports streaming engagement. Disney announced on Sep 22 that its Disney+ and Hulu video podcast library would double in the coming months, spanning comedy, true crime, news, sports and companion shows. New additions include “Best Friends” and “Perfect Person”, alongside podcasts linked to Disney’s popular franchises. A broader offering should encourage repeat viewing and deepen audience engagement, supporting subscriber retention.
- Positive on Disney’s long-term earnings outlook despite pricing concerns. We remain positive on Disney, although higher streaming prices could weigh on affordability and subscriber retention in the near term. However, continued strength across its core franchises and expansion into broader content formats should support engagement and monetisation over time. These strengths should support growth, although subscriber responses to higher pricing warrant monitoring. (Shaina Mahtani)
Type of Events | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Leading investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
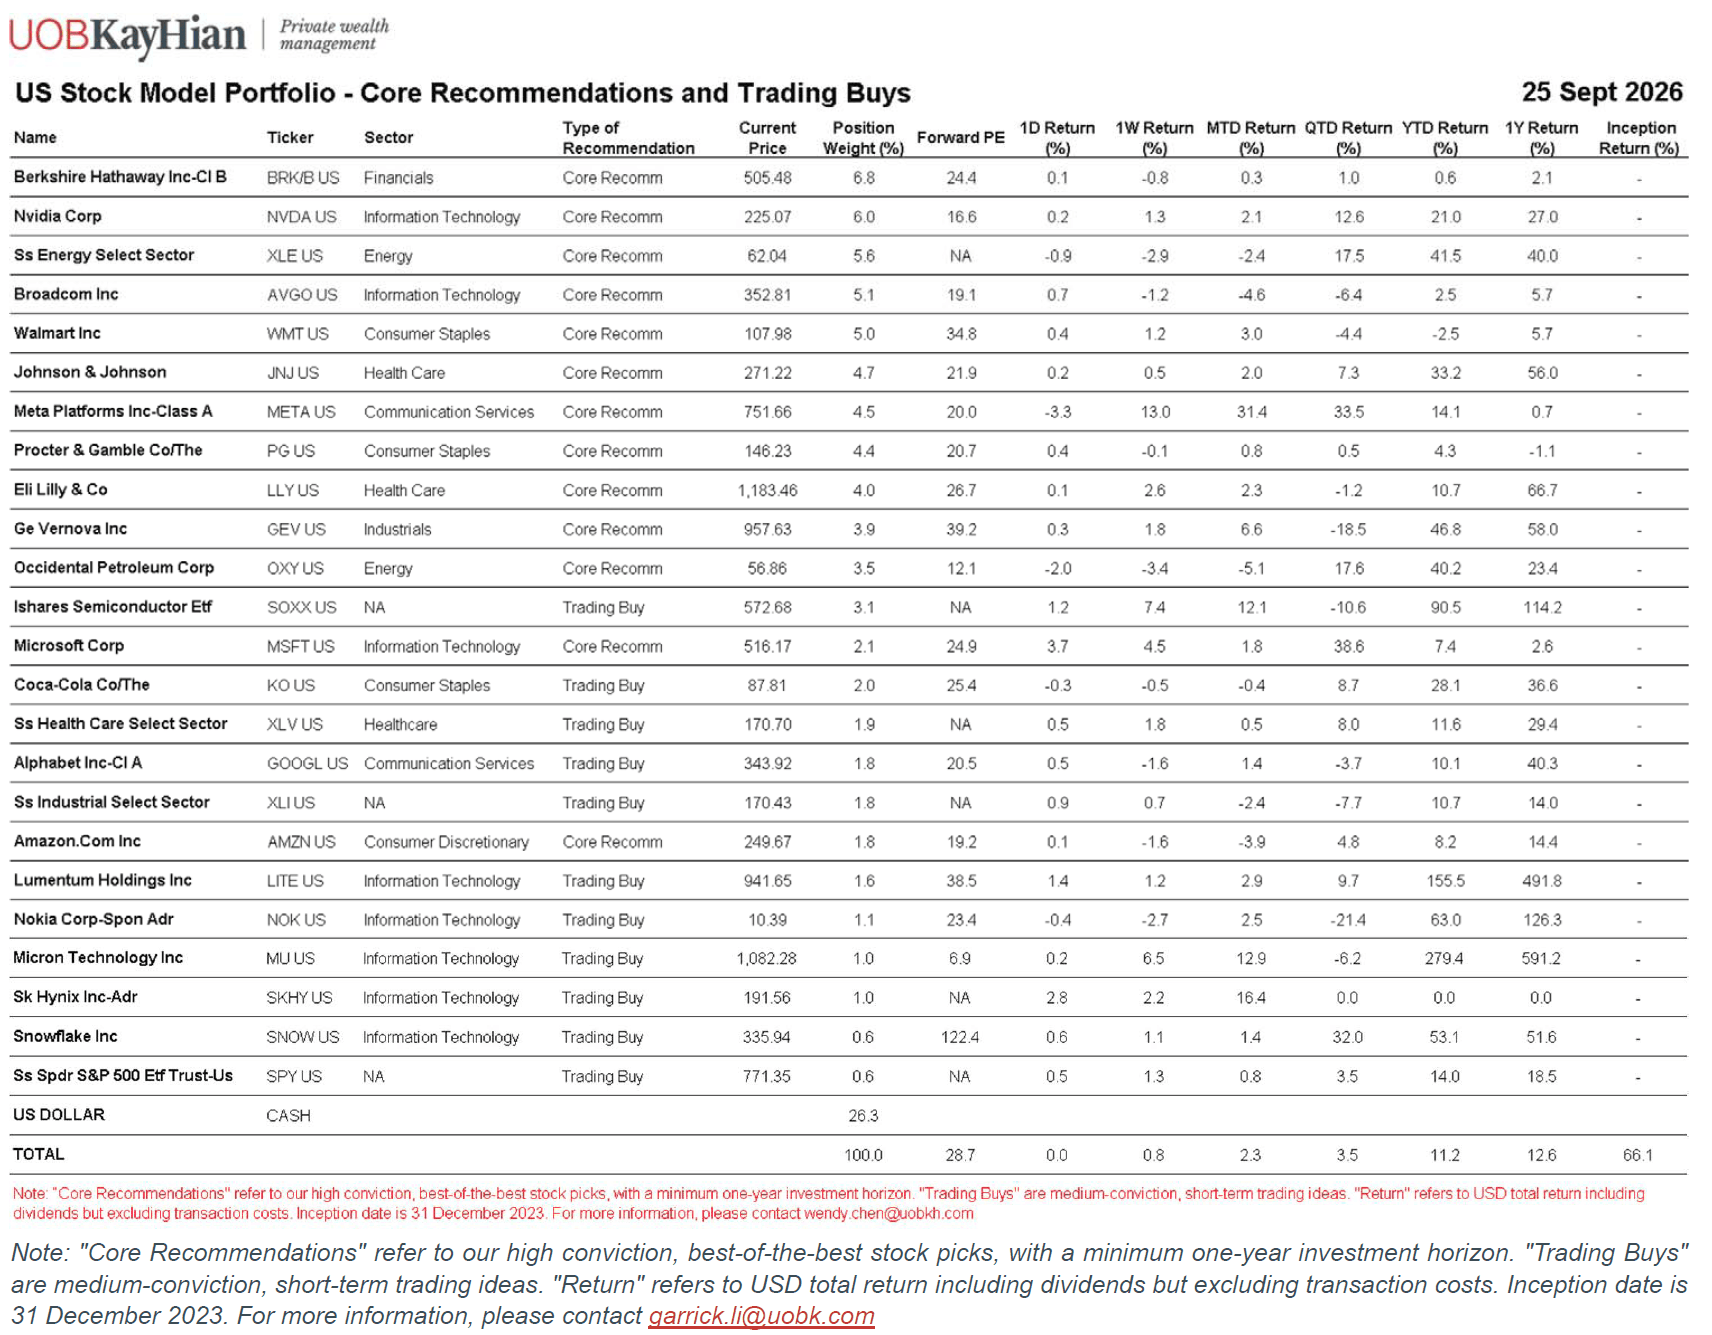
Appendix A – US Stock Model Portfolio
Key US Market Indices
Index | Price | Past 2-Week Return | YTD Return |
S&P 500 | 7,743 | 1.1% | 13.1% |
Dow Jones Industrial Average | 51,829 | -1.4% | 7.8% |
Nasdaq Composite | 27,069 | 2.8% | 16.5% |
Source: UOB Kay Hian and iFinD, as of September 28, 2026.
- First rate hike in three years. Post hotter-than-expected CPI inflation and employment print for August, the Fed raised rates by 25bps in September – its first hike in over three years, validating our top prediction of the Fed Wildcard in 2026. The FOMC’s hawkish stance underscores Chair Warsh's determination to restore Fed credibility amid persistent inflation and market complacency.
- Focus on the terminal rate. The stock market response has been volatile yet relatively measured (see below). Now the shoe has dropped, investors have likely shifted their focus to the length of the tightening cycle, namely the terminal rate and how long the Fed will remain restrictive. Inflation, particularly oil-driven inflation, will be key to answering both questions. We’ll therefore continue to monitor the oil-Iran nexus closely.
- Nasdaq leads; market divergence widens. Following the Fed rate hike, US equities posted mixed performance over the past two weeks. The tech-heavy Nasdaq Composite led with a 2.8% gain, while the Dow Jones retreated 1.4%. The S&P 500 managed a modest 1.1% gain, pushing its YTD return to 13.1%. This divergence reflects the ongoing rotation back into AI-driven megacaps and growth names, while higher rates weigh on value and cyclical stocks. It seems that strong AI-related earnings are overriding macro headwinds – at least for now – effectively acting as a “sorting mechanism”.
- 3Q earnings season: the sorting mechanism at work. Despite S&P’s double-digit YTD return, its forward P/E multiple has compressed from 22x to 19x this year. This multiple contraction reflects higher costs of capital (10Y yields touching 5.2%), AI disruption fears (lower valuation for software), and robust earnings growth among core AI companies. The sorting mechanism mentioned above could become even more evident during the upcoming earnings season, as investors increasingly reward perceived AI winners and companies with strong earnings momentum.
- Must-read: Our Leading Investor Signals cover Trump’s latest trades on page 4.
- Best performing sectors: Info Tech (XLK) +4.7%, Health Care (XLV) +3.6%, Communication Services (XLC) +0.7%.
- Potential movers and shakers:
Positive | Meta (META), AMD (AMD), Intel (INTC), Netflix Inc (NFLX), Walt Disney (DIS), Eli Lilly & Co. (LLY), AbbVie Inc. (ABBV), Berkshire Hathaway Class B (BRK/B), Micron (MU US) |
Neutral | Verizon Communications Inc (VZ), Tesla (TSLA US), Louis Vuitton Moët Hennessy (MC FP/LVMUY US), On Holding AG (ONON US), Nike (NKE US) |
Negative | McDonald’s (MCD US) |
- Must Watch Events: US Sep Labour Data (Oct 2), US Sep CPI/PPI data (Oct 14). Earnings: MU (Sep 30), JPM (Oct 13), ASML (Oct 14), TSM (Oct 16), MSFT (est Oct 29), META (est Oct 29), GOOGL (est Oct 29), LLY (Oct 29). Details below.
Date | Macro Data | Sector / Company Events |
Sep 30 |
| Earnings: MU |
Oct 1 | Initial Jobless Claims, S&P Sep PMI-Mfg Final | Earnings: NKE |
Oct 2 | US Sep Labor data (NFP/ Unemployment Rate), |
|
Oct 5 | S&P Sep PMI-Svcs Final |
|
Oct 6 | US Aug Exports & Imports |
|
Oct 8 | Initial Jobless Claims | TSMC September Monthly Sales. |
Oct 13 |
| Semicon West (till Oct 15). |
Oct 14 | US Sep CPI | Earnings: BAC, ASML NA |
Oct 15 | Initial Jobless Claims, US Sep PPI, US Sep Retail Sales, New Yuan Loans, Outstanding Loan Growth, Total Social Financing, |
|
Oct 16 | US Sep Capacity Utilisation | Earnings: TSM est |
Oct 20 |
| Earnings: NFLX, VZ est |
Oct 21 |
| Earnings: IBM, KO est, |
Oct 22 | Initial Jobless Claims | Earnings: NOK, PG est, TSLA est |
Oct 23 | S&P Global PMI-Mfg & Svcs Flash. | Oracle AI World Tour (till Oct 28). |
Oct 26 |
|
|
Oct 27 | US Aug House Price Index | Earnings: PYPL, UPS est |
Oct 28 |
| European Central Bank interest rate decisions (till Oct 29). |
Oct 29 | Initial Jobless Claims, Fed Interest Rate Decision, US 3Q GDP, US Sep Personal Income/Spending, US Sep PCE | Bank of Japan rate decision (till Oct 30). |
Leading Investor Signals
One of our key messages is that Trump moves markets, and so do influential leaders such as Nvidia CEO Jensen Huang and Tesla’s Elon Musk. Their words and actions often draw attention to specific investments, shape investor sentiment and drive short-term price swings across markets. It is important to track such signals to understand where investor focus is shifting, how market narratives may evolve, and what potential risks and opportunities lie ahead. We hope you find such insights useful.
President Trump’s Trade Disclosures
Trump’s July 2026 disclosures showed the largest net purchases in the Vanguard Dividend Appreciation ETF (VIG) and iShares Russell 1000 ETF (IWB), at USD 1.0-5.0mn each. Other net buys include Home Depot (HD; USD 0.25–0.56mn), Mastercard (MA; USD 0.02-0.26mn), UnitedHealth (UNH; USD 0.09-0.25mn) and Apple (AAPL; up to USD 0.03mn). The largest net sales were Microsoft (MSFT; USD 6.1-30.9mn) and Amazon (AMZN; USD 5.2-25.5mn), both of which are our Core Recommendations.
President Trump’s net reported trading activities for July 2026
Stock / ETF Name | Ticker | GICS Sector | Buy Trades | Aggregate Buy range | Sell Trades | Aggregate Sell range | Net direction | Possible net range |
Vanguard Dividend Appreciation ETF | VIG | — | 1 | USD 1.0–5.0 mn | 0 | — | Net buy | USD 1.0–5.0 mn |
iShares Russell 1000 ETF | IWB | — | 1 | USD 1.0–5.0 mn | 0 | — | Net buy | USD 1.0–5.0 mn |
Home Depot | HD | Consumer Discretionary | 3 | USD 0.27–0.56 mn | 1 | USD 0.00–0.01 mn | Net buy | USD 0.25–0.56 mn |
Mastercard | MA | Financials | 3 | USD 0.12–0.32 mn | 1 | USD 0.05–0.10 mn | Net buy | USD 0.02–0.26 mn |
UnitedHealth | UNH | Health Care | 1 | USD 0.10–0.25 mn | 1 | USD 0.00–0.01 mn | Net buy | USD 0.09–0.25 mn |
Apple | AAPL | Information Technology | 2 | USD 0.00–0.03 mn | 0 | — | Net buy | USD 0.00–0.03 mn |
Meta | META | Communication Services | 3 | USD 0.12–0.32 mn | 5 | USD 0.25–0.63 mn | Need exact transaction amount | Net sell USD 0.51mn to net buy USD 0.06mn |
Visa | V | Financials | 2 | USD 0.20–0.50 mn | 1 | USD 0.25–0.50 mn | Need exact transaction amount | Net sell USD 0.30mn to net buy USD 0.25mn |
Palantir | PLTR | Information Technology | 2 | USD 0.02–0.07 mn | 3 | USD 0.02–0.08 mn | Need exact transaction amount | Net sell USD 0.06mn to net buy USD 0.05mn |
Microsoft | MSFT | Information Technology | 3 | USD 0.17–0.40 mn | 6 | USD 6.5–31.1 mn | Net sell | USD 6.1–30.9 mn |
Amazon | AMZN | Consumer Discretionary | 2 | USD 0.00–0.03 mn | 3 | USD 5.3–25.5 mn | Net sell | USD 5.2–25.5 mn |
Modine Manufacturing | MOD | Consumer Discretionary | 0 | — | 0 | — | No trades | — |
Vanguard S&P 500 ETF | VOO | — | 0 | — | 0 | — | No trades | — |
Source: OGE. Aggregate ranges are calculated by summing the lower and upper bounds of the reported transactions. The possible net range compares minimum purchases with maximum sales and maximum purchases with minimum sales. A net direction is assigned only when the entire resulting range is either positive or negative
Best 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLK.P | Information Technology | 4.7% | 36.8% | Arista Networks, Inc. (ANET) +3.5%, Keysight Technologies, Inc. (KEYS) +6.9%, Servicenow, Inc. (NOW) +2.3% |
XLV.P | Health Care | 3.6% | 11.6% | Eli Lilly And Company (LLY) +6.1%, Thermo Fisher Scientific Inc. (TMO) +10.8%, Danaher Corporation (DHR) +12.2% |
XLC.P | Communication Services | 0.7% | -3.2% | Live Nation Entertainment, Inc. (LYV) +0.4%, The Walt Disney Company (DIS) -0.4%, Tko Group Holdings, Inc. (TKO) -3.6% |
Source: UOB Kay Hian and iFinD, as of September 28, 2026.
- Information Technology led with a 4.7% gain over the last two weeks, lifting its YTD return to 36.8%. Arista Networks (ANET) rose 3.5%, Keysight Technologies (KEYS) gained 6.9% and ServiceNow (NOW) advanced 2.3%. Gains across networking, electronic testing and enterprise software suggest continued optimism in AI-related names beyond semiconductors. The upcoming 3Q earnings seasons will help determine whether such gains are sustainable.
- Health Care gained 3.6% in two weeks, lifting its YTD return to 11.6%. Eli Lilly (LLY) rose 6.1%, as its new research collaboration and manufacturing investment support longer-term pipeline and supply outlook. Thermo Fisher Scientific (TMO) and Danaher (DHR) surged 10.8% and 12.2%, respectively. Stronger performance of these two life-science tools stocks warrants a separate test of whether customer orders are recovering. Lilly remains our Core Recommendation, while the Health Care Select Sector SPDR Fund (XLV.P) is a Trading Buy.
- Communication Services edged up 0.7% over the past two weeks, narrowing its YTD decline to 3.2%. Live Nation Entertainment (LYV) gained 0.4%, while Walt Disney (DIS) slipped 0.4% and TKO Group (TKO) fell 3.6%. Disney’s streaming price increases could improve revenue per subscriber, although viewer retention remains a key risk.
Worst 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLF.P | Financials | -3.9% | 1.4% | Bank Of America Corporation (BAC) -9.6%, Jpmorgan Chase & Co. (JPM) -3.7%, The Goldman Sachs Group, Inc. (GS) -9.1% |
XLE.P | Energy | -4.2% | 41.5% | Chevron Corporation (CVX) -4.5%, Exxonmobil Holdings Corporation (XOM) -3.3%, Conocophillips (COP) -7.3% |
XLU.P | Utilities | -6.1% | -5.5% | Nextera Energy, Inc. (NEE) -7.6%, The Southern Company (SO) -4.9%, Duke Energy Corporation (DUK) -5.1% |
Source: UOB Kay Hian and iFinD, as of September 28, 2026.
- Financials fell 3.9% in two weeks, reducing its YTD gain to 1.4%. Amid AI disruption fears, Bank of America (BAC) dropped 9.6%, JPMorgan Chase (JPM) declined 3.7% and Goldman Sachs (GS) lost 9.1%. Bank of America signaled weaker investment-banking fees and broadly flat trading revenue, while Goldman Sachs pointed to softer fixed-income trading and higher expenses.
- Energy declined 4.2% over two weeks, trimming its YTD gain to 41.5%. Chevron (CVX) fell 4.5%, Exxon Mobil (XOM) declined 3.3% and ConocoPhillips (COP) lost 7.3%. Softer crude prices weighed on producers after the sector’s strong YTD advance. Oil-price direction is now the clearest near-term test for producer cash flows. The Energy Select Sector SPDR Fund (XLE.P) remains our Core Recommendation.
- Utilities was the worst-performing sector, down 6.1% over two weeks and down another 5.5% YTD. NextEra Energy (NEE) lost 7.6%, Southern Company (SO) fell 4.9% and Duke Energy (DUK) declined 5.1%. Rising Treasury yields has reduced the appeal of dividend-paying utility stocks while raised concerns about their financing costs. Stable electricity demand and AI-driven growth offered little protection against this rate-based repricing.
Stocks: Potential Movers and Shakers
Stock | Sector | Type of Events | Our Take |
AbbVie Inc. (ABBV) | Health Care | Corporate Action | Slightly Positive |
- Parkinson’s FDA Approval. The FDA approved AbbVie’s once-daily Parkinson’s treatment Juvmo (tavapadon), acquired through its USD 8.7bn Cerevel acquisition. Late-stage trials showed improved symptoms, while AbbVie continues to target over USD 5bn in combined Parkinson’s sales, although initial uptake may be gradual as Medicare coverage is negotiated.
- Singapore Manufacturing Expansion. AbbVie’s USD 223mn Singapore expansion adds 24,000 liters of biologics drug-substance capacity, supporting existing products and its immunology and oncology pipeline. The facility is expected to become operational in 2026, strengthening AbbVie’s Asian manufacturing footprint and global biologics capacity.
- Key Takeaways. Juvmo’s approval validates AbbVie’s strategy of using acquisitions to diversify beyond its core immunology franchise and strengthens its exposure to neuroscience, a key growth pillar. Separately, the Singapore expansion provides additional capacity to support future biologics launches, helping reduce supply constraints as AbbVie advances a broader pipeline across immunology and oncology.
- Constructive Outlook. We become increasingly constructive on AbbVie as new product approvals broaden its growth drivers, while expanded biologics capacity supports future pipeline commercialisation and longer-term earnings growth. (Tang Kai Jie)
Stock | Sector | Type of Events | Our Take |
Berkshire Hathaway Class B (BRK/B) | Multiple Industries | Channel Checks | Positive |
- BRK could further increase investments in Japan’s five major trading houses: Mitsubishi, Mitsui, Itochu, Marubeni and Sumitomo. CEO Greg Abel signalled that additional purchases were under consideration in Sep 2026, reinforcing the long-term strategy established by Warren Buffett. Existing agreements allow BRK to exceed the 10% ownership ceiling. The holdings were worth USD 35.4b as of end-2025 against a cost of USD 15.4b and generated USD 862m in annual dividends. Its yen borrowings broadly match the investment cost and carry an average interest rate of just 1.2%.
- Proactive approach to deploy the enormous cash reserves. Under new CEO Greg Abel, BRK has accelerated capital allocation through a combination of equity purchases, acquisitions, and share repurchases. The most notable investment was a substantial increase in its Alphabet position to 106m shares as of June 2026, which is now the third-largest equity position estimated at USD 38bn. BRK has resumed share repurchases in 2Q2026, spending USD 4.5b on buybacks. The acceleration in buybacks coincided with BRK becoming a net buyer of equities at USD 20bn for the first time in 14 quarters.
- BRK’s subsidiary Precision Castparts produces intricate components for the high-temperature sections of aircraft engines and industrial gas turbines using nickel- and cobalt-based alloys. The subsidiary was recently acquired by GE Aerospace for USD 11.8b (26x projected 2027 EBITDA). The deal highlights the strategic value of Precision Castparts’ specialised aerospace casting capacity. Precision Castparts is a growing contributor to BRK’s manufacturing earnings. Its pre-tax earnings rose 34.2% in 2025 and 33.6% yoy in 1H2026.
- Defensive shelter from market volatility amid macro uncertainty. BRK/B trades at 2026 PE of 24.5x and P/B of 1.45x. Buy BRK due to its diversified earnings and cash-rich balance sheet. The stock remains our Core Recommendation amid the uncertain macro environment. (Jonathan Koh)
Stock | Sector | Type of Events | Our Take |
Eli Lilly & Co. (LLY) | Health Care | Corporate Action | Positive |
- China R&D Collaboration. Eli Lilly entered into a research collaboration with InnoCare Pharma worth up to USD 3.35bn. InnoCare will leverage its drug discovery platform to identify and advance compounds against up to five targets, with Lilly gaining access to potential new assets across areas including oncology and autoimmune diseases.
- US Manufacturing Expansion. Lilly broke ground on a USD 6.5bn manufacturing facility in Houston, forming part of its broader USD 50bn domestic manufacturing investment programme. The plant will manufacture APIs for Foundayo (orforglipron), its oral GLP-1 obesity treatment, alongside other small-molecule medicines and advanced therapeutics.
- Strengthening Pipeline and Supply Capacity. The InnoCare partnership expands Lilly’s early-stage discovery pipeline without requiring the company to build all capabilities internally, while the Houston facility strengthens manufacturing capacity ahead of expected growth across its obesity and broader pharmaceutical portfolio. The highly automated plant should also support manufacturing efficiency and supply-chain resilience.
- Constructive Long-Term Outlook. We remain constructive on LLY as pipeline diversification and continued manufacturing investment support longer-term growth beyond its existing GLP-1 franchise. LLY is our Core Recommendation. (Tang Kai Jie)
Stock | Sector | Type of Events | Our Take |
Louis Vuitton Moët Hennessy (MC FP/LVMUY US) | Consumer Discretionary | Corporate Action | Neutral |
- LVMH set to join Armani minority stake talks. Armani is scheduled to hold formal talks in late Sept or early Oct with LVMH, L'Oreal and EssilorLuxottica over the sale of an initial 15% stake, as instructed in the will of the late Giorgio Armani. One option discussed informally would split the stake across all three, according to the Financial Times.
- LVMH has expressed interest, but people familiar with the matter said it is not an obvious fit, as Armani generates a significant share of sales at lower price points than LVMH's core brands and is weighted more towards fashion than higher-margin accessories. Longstanding ties between the Arnault family and the late designer remain an important factor.
- Valuation may prove a stumbling block, with Armani-side parties floating about EUR 10bn against investors’ assessment of EUR 3-7bn. Armani's revenue fell 2.8% yoy to EUR 2.19bn in 2025, following a 5% decline in 2024. A stock market listing remains the fallback option. (Ejann Hiew)
Stock | Sector | Type of Events | Our Take |
McDonald’s (MCD US) | Consumer Discretionary | Investor Roadshow | Negative |
- Expects inflation and flat traffic to persist. At its investor day on Sep 23, CEO Chris Kempczinski told CNBC that management should stop describing the environment as difficult and accept it as the norm, adding that no change is expected. He noted that inflation is sticky globally and that beef costs have nearly doubled over five years in its largest markets. Price increases by McDonald’s will likely be considered, but the company will be careful not to drive diners away, having acknowledged the mistake of raising prices too quickly after the pandemic.
- Heavy capex to support franchisee upgrades. The company plans to spend up to USD 8.5bn through 2036 to accelerate franchisee investment, including USD1.5-2bn of incremental capex in 2027-2030 on top of about USD 3bn of annual capex. Franchisees face incremental costs of roughly USD 800,000 per restaurant on top of a USD 400,000-450,000 standard remodel, while beef and labour costs already weigh on profits. Looking ahead, management targets an operating margin in the low-to-mid 50% range by 2030 (vs 46.1% in 2025) and a payback of about four years for franchisees.
- McDonald's targets share gains in chicken and beverages. In chicken, the company holds about 20% of the USD130 bn global category, while in beverages it holds roughly 10% of the USD 230bn global category and is the second-largest coffee player worldwide. Looking ahead, management aims to raise its global shares in both chicken and beverages by about 1.5ppt each by 2030, supported by US pilots of hand-breaded chicken, new grilled chicken sandwiches and wraps, and new McNuggets flavours and sauces, along with new espresso machines and alternative milk options coming to US restaurants and more new drinks internationally. Beef remains a core focus, with about 40% share of the USD 50bn global category and fresh beef Quarter Pounders to be extended to more markets outside the US.
- Valuation supports long-term accumulation despite near-term caution. Following the news, the shares fell 5% and the Bloomberg consensus price target fell 4% to USD 302.36. McDonald's next-twelve-month forward PE of 17.36x is below the S&P 500's 19.17x, and its PE relative to the SPY is at a 10-year low. We see this as a long-term accumulation opportunity for a quality stock affected by current macro headwinds. (Ejann Hiew)
Stock | Sector | Type of Events | Our Take |
Meta (META) AMD (AMD) Intel (INTC) | Information Technology | Sales / Products | Positive |
- Meta’s personal AI agent Muse claimed the No. 1 spot among free apps on Apple's US App Store, overtaking OpenAI’s ChatGPT. Muse’s early success validates Meta’s structural advantages in consumer AI, powered by its unparalleled social media platform and distribution network.
- While near-term financial impact is limited, Muse unlocks a massive new addressable market, with the potential to deliver ~USD 29bn in incremental revenue by 2030 (~12% of Meta's 2026 revenue). Competition also remains intense, as OpenAI will introduce its agentic product this week, followed by similar products from Google and others.
- Muse has sparked a strong rally in CPU-related names (AMD, ARM, Intel), as faster AI agent adoption drives incremental demand for CPUs. However, we recommend caution on the CPU industry, as AI agent development is still nascent and recent share price gains may be running ahead of fundamentals (see below).
- Assuming that 500mn users globally would adopt Muse-like AI agents in the medium term, the incremental CPU demand amounts to only USD 4bn in value, roughly 4% of the overall USD 100bn TAM. Meanwhile, the combined market cap of CPU stocks has already increased by USD 300-400bn in the last two weeks, suggesting the market may be overly optimistic. (Garrick Li)
Stock | Sector | Type of Events | Our Take |
Micron (MU US) | Information Technology | Earnings | Positive |
- Micron reports Aug quarter earnings on September 30 EST (October 1 Hong Kong time). Visible Alpha estimates its revenue to grow 349.5% yoy and 22.7% qoq to USD 51bn, while consensus looks for gross margin to expand 42.1ppt yoy and 2.2ppt qoq to 86.8%, and EPS to grow 1,002.1% yoy and 24.3% qoq to USD 31.52.
- For the Nov quarter, Visible Alpha expects revenue to grow another 319.7% yoy and 12.6% qoq to USD 57bn. Consensus has gross margin expanding 31.5ppt yoy and 0.7ppt qoq to 87.5%, and EPS growing 675.9% yoy and 11.8% qoq to USD 35.15.
- The sell side brokers expect Micron's DRAM ASPs to increase 20-25% qoq and NAND ASP 22.5-34% qoq in the Aug quarter, moderating to around 13% and 15% respectively in the Nov quarter. This compares to TrendForce’s estimates for 3Q2026 at +13-18% for conventional DRAM and +10-15% for NAND.
- Four items that could move MU shares: (1) pricing levels on any new strategic customer agreements, (2) share repurchase plans now that the CHIPS Act restrictions lift on December 9, (3) gross margins guidance in 2027 (preferably at mid-80s), and (4) the HBM roadmap covering market share, HBM4 shipments and yields, as well as HBM4E sampling. Market may also look for comments on competition from China. Micron is our Trading Buy. (Johnny Yum)
Stock | Sector | Type of Events | Our Take |
Netflix Inc (NFLX) | Communication Services | Sales / Products | Positive |
- Advertising expansion strengthens monetisation. Netflix hosted UK Upfront on Sep 24, highlighting that its ad-supported plan has reached over 14m viewers in the country. Netflix also announced that its ad tier will expand to nine additional EMEA markets starting March 2027, while planning to enhance its Ads Suite with broader demographic targeting Pause Ads. The larger addressable audience and improving ad-tech capabilities should support continued Netflix’s advertising revenue growth.
- Live programming broadens Netflix’s entertainment offering. Netflix has the exclusive right to live-stream STARTO ENTERTAINMENT’s New Year’s Eve countdown concert worldwide on Dec 31, and confirmed the Tyson Fury–Anthony Joshua boxing match in December 2026. The continued expansion into live music and sports should help differentiate its platform, increase viewing and create new advertising and sponsorship opportunities.
- Children’s content expansion strengthens family appeal. Netflix also announced an extension of its “Sesame Street” agreement through Season 62, with a new film in development, alongside additional series from the “Gabby’s Dollhouse” franchise. With kids and family content now accounting for 15% of total viewing hours in 1H2026, expanding familiar titles should encourage repeat viewing and strengthen Netflix’s value to family subscribers, supporting retention.
- Positive on long-term earnings growth. We remain positive on Netflix as continued expansion of its advertising capabilities, growing live programming slate and investment in family content should support engagement and monetisation. A broader ad-supported audience and improving ad-tech tools provide further upside to advertising revenue, while differentiated live events should strengthen retention. These drivers should help drive long-term earnings growth and margin expansion. (Shaina Mahtani)
Stock | Sector | Type of Events | Our Take |
On Holding AG (ONON US) Nike (NKE US) | Consumer Discretionary | Corporate Action | Neutral |
- On Holding signs Kylian Mbappé as it launches into football. On announced its entry into football on Sep 18, signing French superstar Kylian Mbappé after Nike chose not to renew his contract upon its expiry in July, according to CNBC. Mbappé will work directly with On's product teams to develop and test future football footwear and apparel, while also serving as a global brand ambassador whose role will extend beyond football into movement, performance and design. On also plans to apply its proprietary LightSpray robotic manufacturing technology, first introduced in 2024, to the development of elite football footwear.
- Short-term catalyst, but we remain cautious. On Holding shares rose 8% from a low of USD 27 following the news, while Nike shares were unchanged. Meanwhile, macro conditions have progressively worsened, with a second Fed rate hike expected in Oct and a prolonged Middle East conflict. While the signing has had an immediate impact on ON shares, we expect any material contribution to its outlook to emerge only at a later date. We therefore expect the shares to remain range-bound at USD 27-37 over the medium term, supporting our cautious view on the stock given the challenging macro environment for consumers. (Ejann Hiew)
Stock | Sector | Type of Events | Our Take |
Tesla (TSLA US) | Consumer Discretionary | Sales / Products | Neutral |
- Tesla's Semi entered volume production seven years late; autonomy moved backwards.
- Positives: The Sparks, Nevada plant opened on Sep 24 with capacity of 50,000 trucks a year, and deliveries began for PepsiCo, DHL and US Foods. Alliance ZET SCALE named Tesla primary supplier for 2,500 trucks, nearly doubling the US electric Class 8 fleet. Optimus output rose roughly tenfold from 2Q2026 to several hundred a week, targeting over 1,000 by year-end. As a result, TSLA gained 1.8% to USD 372.11.
- Negatives: Only eight of the 476 robotaxis registered in Texas were active in Austin last week. The last issue's 200 referred to registrations, not deployment figures. NHTSA ordered Tesla on Sep 10 to show under oath that the Cybercab is legal to sell, and the EU postponed its Full Self-Driving vote to December. Optimus assembly still shows fragile hands and supplier quality problems. China discounting resumed on Sep 25, with price reductions of RMB 5,000 on Model 3 and RMB 7,000 on selected Model Y, the second cut in a month.
- We remain Neutral on Tesla. The Semi adds a second product line with orders behind it. However, autonomy, which has been supporting the valuation, went backwards on deployment and approval. Watch 3Q2026 deliveries, the October 1 Roadster reveal and China’s Sep retail numbers as potential stock catalysts. (Ken Lee)
Stock | Sector | Type of Events | Our Take |
Verizon Communications Inc (VZ) | Communication Services | Sales / Products | Neutral |
- New device promotions support subscriber acquisition and retention. Verizon expanded its premium device offering during the period, with the iPhone 18 Pro lineup becoming widely available, alongside new Motorola foldable devices. Promotions include annual iPhone upgrades under its Simplicity plan and trade-in discounts of up to USD 1,100 on selected plans. Competitive offers should support customer additions and retention, although subsidies could weigh on near-term margins.
- AI investment expands support for workers and small businesses. Verizon announced a USD 70m AI skills initiative on Sep 23, comprising USD 50m in new funding and an existing USD 20m fund for departing employees. The programme provides free training through technology and community partners. The initiative could strengthen relationships with small businesses and communities, although its direct contribution to near-term revenue and earnings is likely to be limited.
- Neutral as subscriber support is balanced by limited near-term earnings upside. We remain neutral on Verizon as competitive device promotions should support customer acquisition and retention, while its AI skills initiative may strengthen engagement with small businesses. However, the direct earnings contribution from these initiatives is likely to be modest, while promotional costs, competitive pressures and elevated investment requirements continue to limit near-term upside. (Shaina Mahtani)
Stock | Sector | Type of Events | Our Take |
Walt Disney (DIS) | Communication Services | Sales / Products | Positive |
- Streaming price increases support monetisation. Disney’s US pricing changes reported on Sep 23 raise standalone ad-free Disney+ and Hulu subscriptions by USD 2.50 to USD 21.49 per month. The ad-free bundle has also increased to USD 21.99, while the ad-supported bundle remains at USD 12.99. Higher pricing should support revenue per subscriber and encourage bundle adoption, although affordability concerns could weigh on retention.
- Marvel re-release demonstrates continued franchise appeal. Disney reported that “Avengers Endgame: Encore” opened at No.1 globally with an estimated USD 86mn, including USD 26mn domestically and USD 60mn internationally. The release pushed Marvel Studios’ cumulative box-office takings above USD 35bn across 38 films. Strong demand for established titles highlights opportunities to generate additional theatrical revenue and build interest ahead of “Avengers: Doomsday”.
- Expanded podcast offering supports streaming engagement. Disney announced on Sep 22 that its Disney+ and Hulu video podcast library would double in the coming months, spanning comedy, true crime, news, sports and companion shows. New additions include “Best Friends” and “Perfect Person”, alongside podcasts linked to Disney’s popular franchises. A broader offering should encourage repeat viewing and deepen audience engagement, supporting subscriber retention.
- Positive on Disney’s long-term earnings outlook despite pricing concerns. We remain positive on Disney, although higher streaming prices could weigh on affordability and subscriber retention in the near term. However, continued strength across its core franchises and expansion into broader content formats should support engagement and monetisation over time. These strengths should support growth, although subscriber responses to higher pricing warrant monitoring. (Shaina Mahtani)
Type of Events | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Leading investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
Appendix A – US Stock Model Portfolio
Analyst
Wendy Chen
wendy.chen@uobkh.comAnalyst
Wang Qi, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


