

Periodic/Sector reports
Industrial Estate: Riding Thailand’s Tech Investment Cycle
OVERWEIGHT (Maintained)
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
- Land sales and transfers should accelerate in 2H26, supported by strong FDI inflows and technology-related demand.
- FDI applications and approvals should sustain Thailand’s industrial investment cycle.
- Hyperscaler investment and Thailand’s growing role as a regional data-centre hub should support demand for industrial sites over the medium term. Maintain OVERWEIGHT.
Analysis
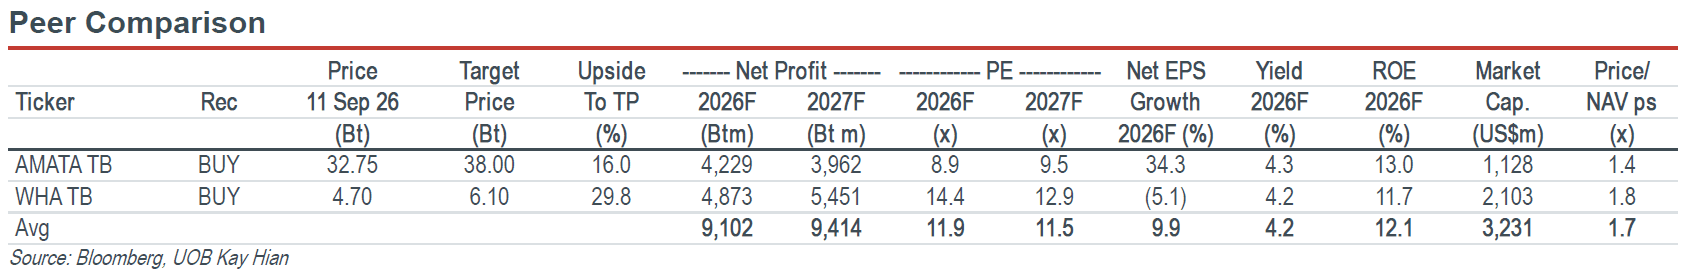
- 2H26 outlook. 1H26 earnings of the industrial estates under our coverage reported aggregate core earnings of Bt3.97b, down 5.7% hoh, mainly due to WHA, which was impacted by the transfer of a low-margin site in its industrial land sales business. Moreover, land transfers fell 33% from 1,614 rai in 1H25 to 1,081 rai in 1H26. 1H26 land sales also dropped 15% hoh, reflecting delays in deal closures rather than deterioration in industrial demand. We expect land sales and transfers to accelerate in 2H26, supported by backlog conversion, continued FDI inflows as well as data centre and advanced manufacturing demand.
- AI and technology cycle support export-led growth. Thailand's economic growth is increasingly supported by the global technology and AI investment cycle. According to the IMF's Jul 26 World Economic Outlook, Thailand ranked among the top four net exporters of AI-related hardware, highlighting the country's growing role in the global technology supply chain. The Bank of Thailand's Jul 26 economic and monetary conditions report also noted that the Thai economy continued to expand, supported by momentum from the global technology and AI cycle. Exports remained a key growth driver, led by electrical and electronic products, particularly computer parts and integrated circuits. We believe the continued expansion of the global AI hardware cycle should support demand for electronics manufacturing and related supply-chain investment in Thailand.
- FDI momentum rally. Thailand’s investment cycle remains strong, with FDI applications and approvals reaching record levels. According to the Board of Investment (BOI), total FDI applications in 1H26 amounted to Bt1.37t, up 80% hoh, led by agriculture, food and biotechnology (+250%) and the digital industry (+150%). Meanwhile, approved FDI projects totalled Bt1.14t, up 81% hoh, driven by the digital, metals and materials, and medical industries, which grew 160%, 62%, and 35%, respectively. Thailand's ambition to become a regional hub for data centres, semiconductor manufacturing, and AI-related supply chains, supported by competitive BOI incentives, should sustain investment momentum. However, FDI is becoming increasingly concentrated in a few high-growth industries, particularly digital and technology-related sectors, rather than being broad-based across the manufacturing sector. This concentration should benefit industrial estate developers with exposure to data centres, electronics, semiconductors, and other technology-intensive industries.
Highlights
- Land sales and transfers should accelerate in 2H26, supported by strong FDI inflows and technology-related demand.
- FDI applications and approvals should sustain Thailand’s industrial investment cycle.
- Hyperscaler investment and Thailand’s growing role as a regional data-centre hub should support demand for industrial sites over the medium term. Maintain OVERWEIGHT.
Analysis
- 2H26 outlook. 1H26 earnings of the industrial estates under our coverage reported aggregate core earnings of Bt3.97b, down 5.7% hoh, mainly due to WHA, which was impacted by the transfer of a low-margin site in its industrial land sales business. Moreover, land transfers fell 33% from 1,614 rai in 1H25 to 1,081 rai in 1H26. 1H26 land sales also dropped 15% hoh, reflecting delays in deal closures rather than deterioration in industrial demand. We expect land sales and transfers to accelerate in 2H26, supported by backlog conversion, continued FDI inflows as well as data centre and advanced manufacturing demand.
- AI and technology cycle support export-led growth. Thailand's economic growth is increasingly supported by the global technology and AI investment cycle. According to the IMF's Jul 26 World Economic Outlook, Thailand ranked among the top four net exporters of AI-related hardware, highlighting the country's growing role in the global technology supply chain. The Bank of Thailand's Jul 26 economic and monetary conditions report also noted that the Thai economy continued to expand, supported by momentum from the global technology and AI cycle. Exports remained a key growth driver, led by electrical and electronic products, particularly computer parts and integrated circuits. We believe the continued expansion of the global AI hardware cycle should support demand for electronics manufacturing and related supply-chain investment in Thailand.
- FDI momentum rally. Thailand’s investment cycle remains strong, with FDI applications and approvals reaching record levels. According to the Board of Investment (BOI), total FDI applications in 1H26 amounted to Bt1.37t, up 80% hoh, led by agriculture, food and biotechnology (+250%) and the digital industry (+150%). Meanwhile, approved FDI projects totalled Bt1.14t, up 81% hoh, driven by the digital, metals and materials, and medical industries, which grew 160%, 62%, and 35%, respectively. Thailand's ambition to become a regional hub for data centres, semiconductor manufacturing, and AI-related supply chains, supported by competitive BOI incentives, should sustain investment momentum. However, FDI is becoming increasingly concentrated in a few high-growth industries, particularly digital and technology-related sectors, rather than being broad-based across the manufacturing sector. This concentration should benefit industrial estate developers with exposure to data centres, electronics, semiconductors, and other technology-intensive industries.
OVERWEIGHT (Maintained)
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


