

Periodic/Sector reports
IT Hardware - Handset: Apple-linked And Premium Suppliers To Widen Their Lead Amid The Downcycle
OVERWEIGHT (Maintained)
Analyst
Analyst
Highlights
- Companies with Apple and premium exposure remained relatively more resilient than those with Android mass-market and low-end/mid-range exposure, although earnings outcomes still depended on product mix and execution. Cowell reported in-line revenue but a 37.6% net profit beat versus consensus; Lens’ revenue fell 7.4% yoy but net profit beat consensus by 48.7%; BYDE’s revenue beat consensus by 6.3% but net profit missed by 46.4%.
- OEM commentary remains less negative than supplier guidance. Xiaomi expects the pace of memory cost increases to slow in 4Q26, whereas AAC, Sunny and Q Tech continue to flag handset pressure, with Sunny expecting OEM order cuts through 2027. This divergence keeps us cautious about the 2027 Android shipment outlook.
- Diversification into AI devices and infrastructure components is providing a meaningful buffer. Sunny and Q Tech’s AIoT products are starting to contribute to a meaningful portion of their top- and bottom lines. Lens, BYDE and AAC are also expecting AI server components contribution to pick up from 2H26.
- We prefer Apple suppliers over Android suppliers on stronger relative shipments, more resilient margins and a multi-year specification upgrade cycle. Within this framework, we favour Cowell for its iPhone camera-content and share gains, HL for its current AI-PCB growth and potential Apple capex upside, and Sunny Optical for its premium handset positioning and fast-growing AIoT businesses.
Analysis
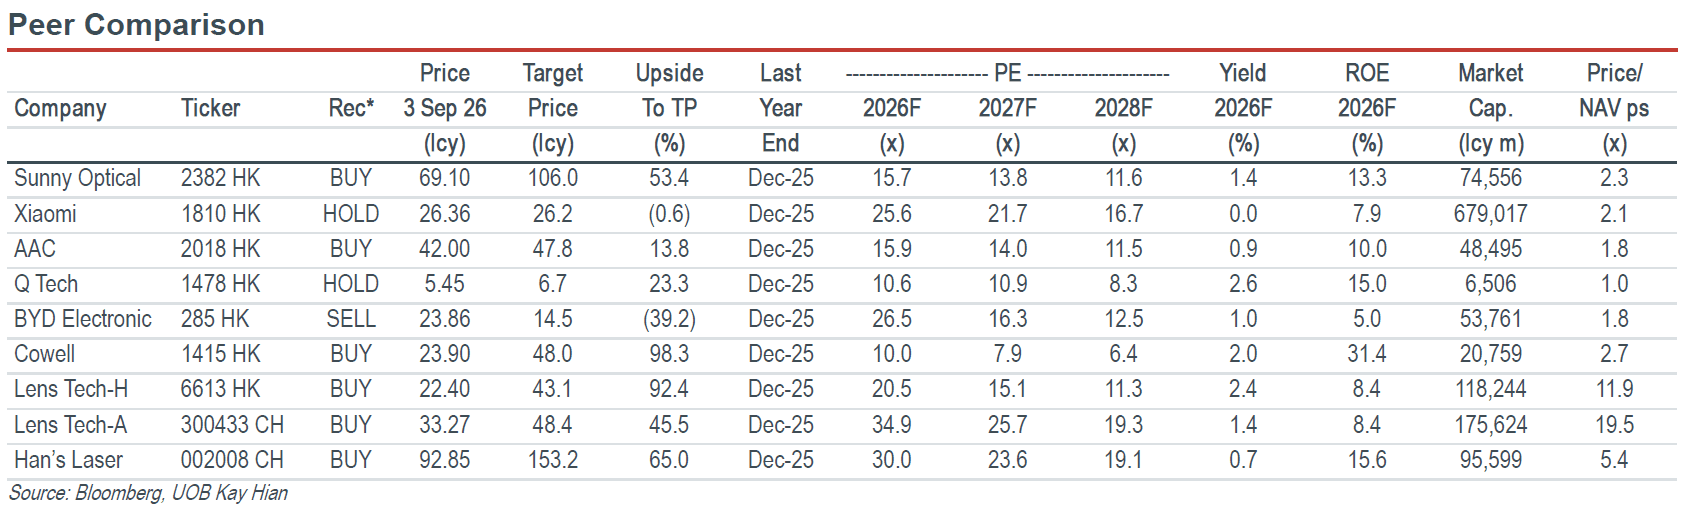
Performance of handset supply chain diverged. Within our coverage, Sunny Optical (Sunny), Cowell, and Han’s Laser (HL) registered strong earnings growth while beating market’s expectations; Lens Tech (Lens) and Xiaomi saw meaningful yoy declines in earnings but earnings were better than feared; AAC registered a decent yoy growth but growth was materially below expectations; while Q Tech and BYD Electronic (BYDE) missed expectations with sluggish yoy growth. Overall, we identified that: a) players with exposure to premium smartphone segments are generally better off; b) players with exposure to the iPhone supply chain are also significantly more resilient than pure Android players; c) almost all supply chain players are accelerating its efforts to diversify out of smartphones, and are treating AI infra and AI device related-products as the next growth driver; and d) with the exception of Apple, OEMs remained in a much worse situation than their suppliers as they are most directly hit by the cost hikes.
Highlights
- Companies with Apple and premium exposure remained relatively more resilient than those with Android mass-market and low-end/mid-range exposure, although earnings outcomes still depended on product mix and execution. Cowell reported in-line revenue but a 37.6% net profit beat versus consensus; Lens’ revenue fell 7.4% yoy but net profit beat consensus by 48.7%; BYDE’s revenue beat consensus by 6.3% but net profit missed by 46.4%.
- OEM commentary remains less negative than supplier guidance. Xiaomi expects the pace of memory cost increases to slow in 4Q26, whereas AAC, Sunny and Q Tech continue to flag handset pressure, with Sunny expecting OEM order cuts through 2027. This divergence keeps us cautious about the 2027 Android shipment outlook.
- Diversification into AI devices and infrastructure components is providing a meaningful buffer. Sunny and Q Tech’s AIoT products are starting to contribute to a meaningful portion of their top- and bottom lines. Lens, BYDE and AAC are also expecting AI server components contribution to pick up from 2H26.
- We prefer Apple suppliers over Android suppliers on stronger relative shipments, more resilient margins and a multi-year specification upgrade cycle. Within this framework, we favour Cowell for its iPhone camera-content and share gains, HL for its current AI-PCB growth and potential Apple capex upside, and Sunny Optical for its premium handset positioning and fast-growing AIoT businesses.
Analysis
Performance of handset supply chain diverged. Within our coverage, Sunny Optical (Sunny), Cowell, and Han’s Laser (HL) registered strong earnings growth while beating market’s expectations; Lens Tech (Lens) and Xiaomi saw meaningful yoy declines in earnings but earnings were better than feared; AAC registered a decent yoy growth but growth was materially below expectations; while Q Tech and BYD Electronic (BYDE) missed expectations with sluggish yoy growth. Overall, we identified that: a) players with exposure to premium smartphone segments are generally better off; b) players with exposure to the iPhone supply chain are also significantly more resilient than pure Android players; c) almost all supply chain players are accelerating its efforts to diversify out of smartphones, and are treating AI infra and AI device related-products as the next growth driver; and d) with the exception of Apple, OEMs remained in a much worse situation than their suppliers as they are most directly hit by the cost hikes.
OVERWEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

7 Sept 2026
IT Hardware: 2Q26 Results: With Sector-wide Shortages Now, Buy Execution Over Bottlenecks

4 Sept 2026
Internet - 2Q26 Results Recap: AI Cloud Accelerates; E-Commerce Still Soft; Gaming Resilient

3 Sept 2026
Internet: AI Capex: Returns Remain Attractive, Funding Risk Diverging
Our latest research

11 Sept 2026
Automobile: Weekly: 60-Day Payment Policy Reinforced; September’s New Model Launch Calendar Busier Than That Of Chengdu Auto Show

10 Sept 2026
Consumer: China Consumer: 2Q/1H26 Results Wrap-up

8 Sept 2026