Periodic/Sector reports
China Healthcare: Innovation And Globalisation: The Twin Engines For Growth
MARKET WEIGHT (Maintained)
Analyst
Analyst
Highlights
Most healthcare companies beat 1H26 expectations, led by drug innovators and CRDMOs on strong sales and licensing revenue.
Medical device firms face ongoing VBP and anti-corruption pressure in China, but globalisation fuels growth through 2026 and beyond.
Maintain MARKET WEIGHT; our top picks are Innovent, BeOne, Hansoh Pharma, WuXi AppTec, WuXi Bio and Edge Medical.
Analysis
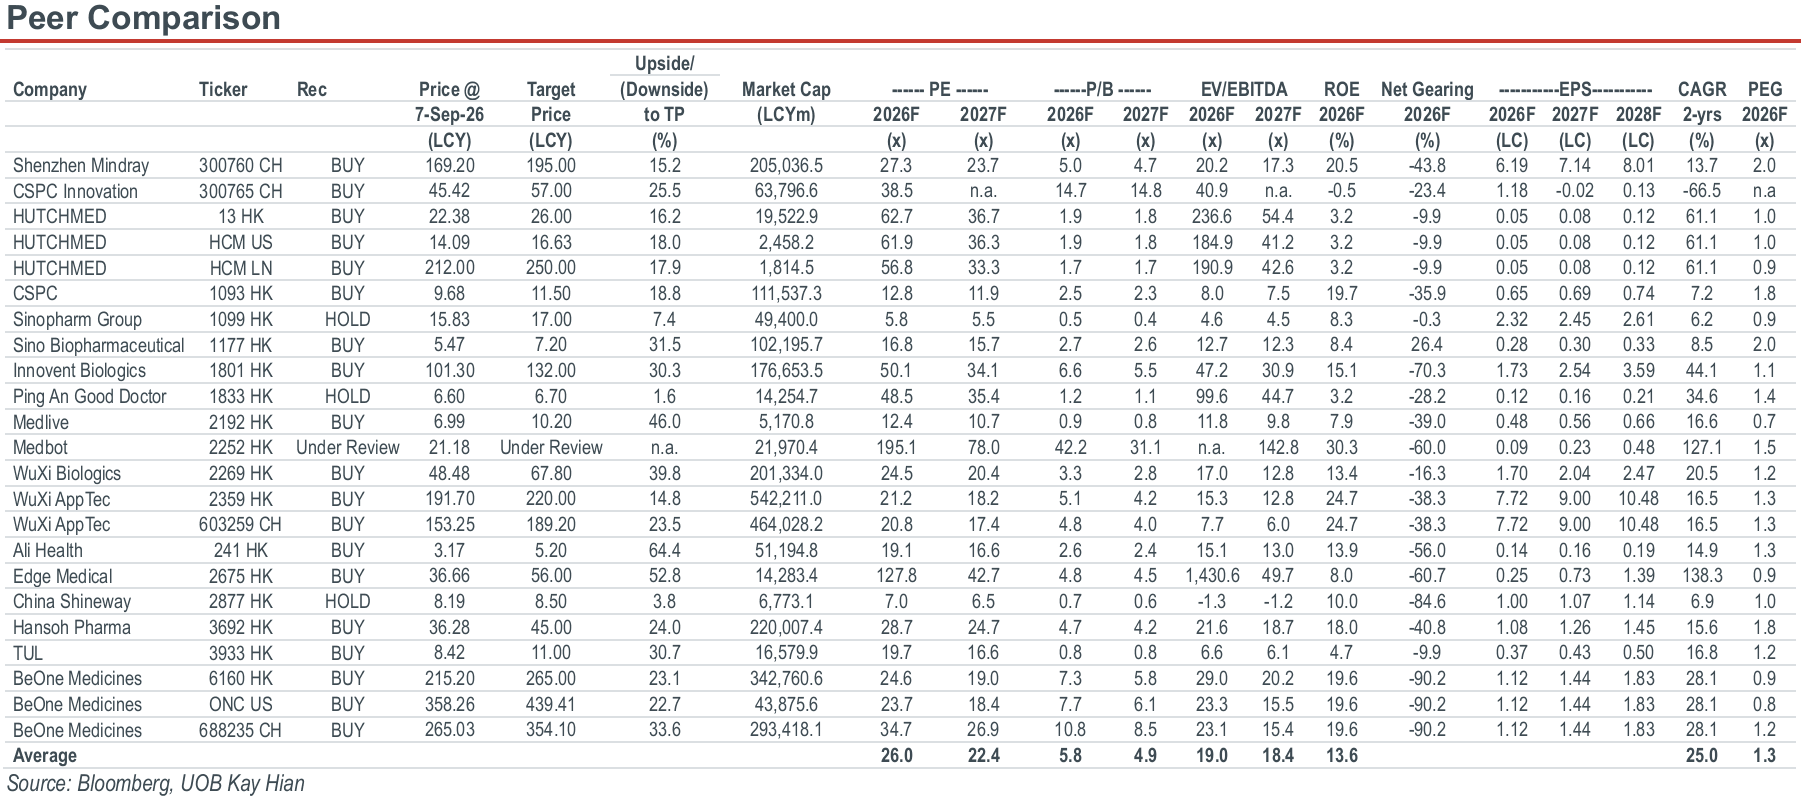
Drug innovators continue to outperform with robust product sales growth and strong licence income. Leading biopharmaceutical companies, Innovent, BeOne Medicines and Hansoh Pharma, have achieved stronger-than-expected 1H26 results. They remain on track to sustain robust revenue growth in 2026, driven by a steady pipeline of new product launches, successful global expansion, and rising licensing income. Further improving operating efficiency will also boost earnings. Innovent is confident in delivering domestic revenue of Rmb20b in 2027 and has set a new target for 2030 – total revenue to reach Rmb35b-40b. BeOne Medicines further raised 2026 revenue guidance by US$300m to US$6.6b-6.8b. Hansoh Pharma and Sino Biopharm continued to guide for double-digit revenue growth in 2026. CSPC saw licensing revenue boost revenue and expects positive revenue growth for the next five years. Among biopharma majors, we prefer Innovent, BeOne, and Hansoh Pharma, and expect continued new product launches and globalisation efforts to underpin strong revenue for 2026 and beyond.
CRO/CDMO leaders: Improving growth outlook. Supported by strong service demand and relentless efforts in pursuing service excellence and business expansion, leading contract research, development and manufacturing organisations (CRDMO) WuXi AppTec and WuXi Bio witnessed accelerated revenue growth at 38.9% and 18.4% yoy, respectively, in 1H26. Moreover, significant margin improvement led to substantial increases in net earnings. Both companies have raised revenue growth targets and guided for steadily improving margins in 2H26 as they further improve the utilisation rate of their new global facilities. WuXi AppTec and WuXi Bio remain our top BUY picks in the CRDMO segment.
Highlights
Most healthcare companies beat 1H26 expectations, led by drug innovators and CRDMOs on strong sales and licensing revenue.
Medical device firms face ongoing VBP and anti-corruption pressure in China, but globalisation fuels growth through 2026 and beyond.
Maintain MARKET WEIGHT; our top picks are Innovent, BeOne, Hansoh Pharma, WuXi AppTec, WuXi Bio and Edge Medical.
Analysis
Drug innovators continue to outperform with robust product sales growth and strong licence income. Leading biopharmaceutical companies, Innovent, BeOne Medicines and Hansoh Pharma, have achieved stronger-than-expected 1H26 results. They remain on track to sustain robust revenue growth in 2026, driven by a steady pipeline of new product launches, successful global expansion, and rising licensing income. Further improving operating efficiency will also boost earnings. Innovent is confident in delivering domestic revenue of Rmb20b in 2027 and has set a new target for 2030 – total revenue to reach Rmb35b-40b. BeOne Medicines further raised 2026 revenue guidance by US$300m to US$6.6b-6.8b. Hansoh Pharma and Sino Biopharm continued to guide for double-digit revenue growth in 2026. CSPC saw licensing revenue boost revenue and expects positive revenue growth for the next five years. Among biopharma majors, we prefer Innovent, BeOne, and Hansoh Pharma, and expect continued new product launches and globalisation efforts to underpin strong revenue for 2026 and beyond.
CRO/CDMO leaders: Improving growth outlook. Supported by strong service demand and relentless efforts in pursuing service excellence and business expansion, leading contract research, development and manufacturing organisations (CRDMO) WuXi AppTec and WuXi Bio witnessed accelerated revenue growth at 38.9% and 18.4% yoy, respectively, in 1H26. Moreover, significant margin improvement led to substantial increases in net earnings. Both companies have raised revenue growth targets and guided for steadily improving margins in 2H26 as they further improve the utilisation rate of their new global facilities. WuXi AppTec and WuXi Bio remain our top BUY picks in the CRDMO segment.
MARKET WEIGHT (Maintained)
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Oct 2026
China Healthcare: Bi-Weekly: China's 15th Five-Year Pharma Plan Signals Long-Term Support For Biopharma And AI Drug R&D

9 Oct 2026
Automobile: China Auto Sector Weekly (26 Sep-8 Oct 26)

16 Oct 2026
China Healthcare - Bi-Weekly: Profit-taking Drags HSHCI; ESMO Data Brightens Biopharma Outlook
Our latest research

23 Oct 2026
Automobile: China Auto Sector Weekly (23 Oct 26)

20 Oct 2026
China Property: NBS: New-home Sales Decline Deepens To 22.6% yoy In Sep 26; Second-Hand Market Continues To Outperform
16 Oct 2026